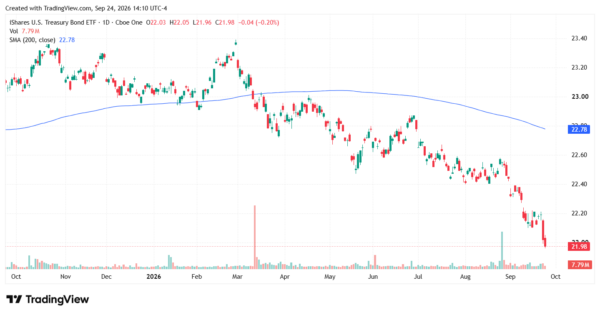
A jump in Treasury yields can sound like a problem for bond traders and the federal government. For households, the effects are easier to recognize: a higher mortgage payment, a more expensive car loan or a credit card balance that takes longer to pay off.
Those costs are back in focus after Treasury yields rocketed higher. The 10-year yield briefly reached 5.125%, while the two-year yield climbed above 4.9%. Investors were weighing fresh inflation pressure, the possibility of another Federal Reserve rate hike in October and signs of weak demand at a five-year Treasury auction.
Why Treasury Yields Matter
The 10-year Treasury yield is a key reference point for longer-term loans, especially mortgages. Mortgage rates do not move in lockstep with it, but a sustained rise in Treasury yields can push home financing costs higher.
That is already a concern for buyers. Mortgage News Daily put its average 30-year fixed rate at 7.26% on September 23, up from 7.17% the day before and 6.37% a year earlier.
Even a small rate change matters when it lasts for 30 years. On a $400,000 mortgage, a move from 7% to 7.25% adds roughly $67 to the monthly principal and interest payment. That may seem manageable on its own. Add property taxes, insurance and other household bills, and it can be enough to put a home out of reach.
Higher rates can also discourage existing owners from moving. Someone with a much cheaper mortgage may hesitate to sell if buying another home means taking out a new loan at today’s rate. That can leave buyers with fewer homes to choose from.
The two-year Treasury yield tells a somewhat different story. It tends to respond more closely to expectations for Fed policy. Its rise suggests investors see a greater chance that short-term interest rates will remain high or climb further.
Credit Cards and Car Loans Could Get Pricier
When the Fed raises its benchmark rate, banks commonly raise their prime rate. Many variable-rate credit cards and home equity lines of credit are tied to prime, so another Fed hike could make existing balances more expensive.
That is especially painful for people who carry a credit card balance from month to month. Their required payment may change only a little, while more of it goes toward interest instead of reducing what they owe.
Car buyers face a similar squeeze, although auto loan rates depend on more than Fed policy. If monthly payments rise, some shoppers will choose a less expensive vehicle, keep their current car longer or delay buying altogether.
Those individual decisions add up. Slower spending can eventually affect car dealers, homebuilders, retailers and the workers they employ. Higher borrowing costs are one way that interest rates cool an economy, but they can also put pressure on families already managing tight budgets.
Will Savers Finally Benefit?
Higher interest rates do offer an upside: people buying newly issued Treasury securities may earn more, and some banks may offer better rates on deposits.
The benefit depends heavily on where savers keep their money. Rates on ordinary savings accounts can lag behind changes in market yields. Someone earning a modest return on a bank account may see little improvement, even as the rates on a mortgage or credit card rise quickly.
Banks face a mixed picture as well. They may earn more on some loans and investments, particularly if the rates they pay depositors rise more slowly. But higher borrowing costs can reduce demand for new loans. They can also make existing bonds held by banks less valuable and increase the risk that financially stretched borrowers fall behind.
Stocks To Watch as Treasury Yields Rise
Higher Treasury yields do not affect every stock the same way. Financial companies can have more opportunities to earn income on loans and interest-bearing assets, although the benefit depends on deposit costs, loan demand and the shape of the yield curve.
Large banks such as JPMorgan Chase (NYSE: JPM), Bank of America (NYSE: BAC) and Citigroup (NYSE: C) have significant exposure to changing interest rates through their lending and securities businesses. Goldman Sachs (NYSE: GS) can also be affected by the broader interest-rate environment through its investment banking, trading and asset-management operations.
For investors focused more directly on the benefits of higher rates to insurers, Chubb (NYSE: CB) is another name worth watching. Insurers invest the premiums they collect, meaning higher yields can eventually provide more income on their investment portfolios as assets mature and are reinvested.
That does not mean higher yields automatically make financial stocks attractive. The impact depends on how quickly rates rise, whether the yield curve remains favorable and whether higher borrowing costs begin to weaken economic activity. Investors therefore need to consider both the potential benefits of higher rates and the pressure they can put on credit quality and demand.
The Economy Faces a Balancing Act
The recent rise in yields has come while the economy still appears strong. The Atlanta Fed’s GDP Now model estimated third-quarter growth at a 5.1% annualized rate in its September 17 update. That is a forecast, not a final reading, and it can change as new data arrives.
Strong growth can help households and businesses handle higher rates for a while. The question is how long they can do so if borrowing costs keep rising.