CoreWeave (NASDAQ: CRWV) sits at the center of two big Wall Street debates. Investors are excited about the demand for artificial intelligence (AI) computing power. They are also worried about how much money CoreWeave must borrow and raise to meet that demand.
Unfortunately, the worries won, sending the stock down about 18% over the last three months. However, according to analysts at UBS, the pullback has created an opportunity. It’s why the firm just initiated a buy rating with a $120 price target on the stock.
This debate is not unique to CoreWeave. Other AI-focused cloud companies, including Nebius Group (NASDAQ: NBIS), IREN (NASDAQ: IREN) and Applied Digital (NASDAQ: APLD), are also attracting investor attention as demand for specialized AI infrastructure expands. Their different business models give investors another way to assess the potential—and risks—of the neocloud market.
UBS analyst Karl Keirstead acknowledges the concern about CoreWeave’s debt. His view is that investors may be paying too much attention to the financing risk and too little attention to the demand for the company’s services.
What Does CoreWeave Actually Do?
CoreWeave rents out the computing power companies need to develop and run AI. Its cloud platform gives customers access to specialized infrastructure built around powerful graphics processing units, or GPUs.
Think of it this way: An AI company may need substantial computing capacity, but building and operating its own data centers takes time, money, equipment and electricity. CoreWeave does that work and sells access to the resulting capacity.
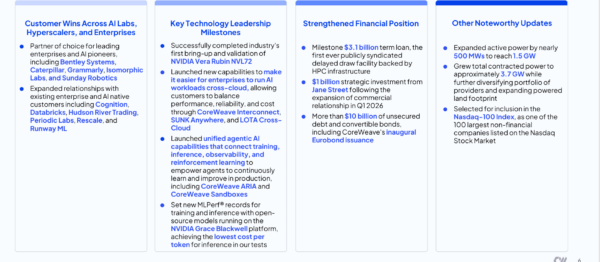
The more companies train AI models or put AI tools to work, the greater the potential demand for computing services. UBS believes that demand extends beyond the best-known AI labs. Businesses across other industries could become a growing source of customers as they adopt AI.
That puts CoreWeave in the same broader investment conversation as other so-called neocloud providers. Nebius, IREN and Applied Digital are pursuing opportunities tied to the rapidly expanding need for AI computing capacity, although their infrastructure footprints, customer bases and financing strategies differ. For investors, the comparison highlights a central question across the group: how much revenue and cash flow can each company generate from the expensive infrastructure it is building?
Why Has the Stock Pulled Back?
Meeting that demand is expensive. CoreWeave needs to secure data centers, power and computing equipment before it can deliver capacity to customers. That means spending heavily today in hopes of collecting substantial revenue later.
Its latest financing plans brought the issue back into focus. On September 17, CoreWeave proposed a $3 billion convertible debt offering. The company subsequently priced an upsized $3.7 billion offering. Convertible debt is borrowing that may, under its terms, be converted into shares. It can help a company raise capital, but it also raises questions about future dilution for existing shareholders.
Why UBS Is Still Bullish
Keirstead believes the market may be underestimating how durable AI computing demand could be. In the UBS comments provided, he also points to stronger GPU pricing, the prospect of generating more revenue from each gigawatt of capacity, and CoreWeave’s reputation for performance. UBS estimates that CoreWeave could eventually lift that figure from roughly $11 billion to more than $15 billion.
That is an analyst projection, not a result CoreWeave has already achieved. Still, it explains the bullish case: If the company can earn more from the infrastructure it builds, today’s spending may look more attractive over time.
UBS is essentially betting that demand and pricing will strengthen enough to outweigh investors’ current financing concerns. The $120 target reflects that outlook; it is not a guarantee that the stock will reach it.
CRWV Reclaims Its 50-Day Moving Average
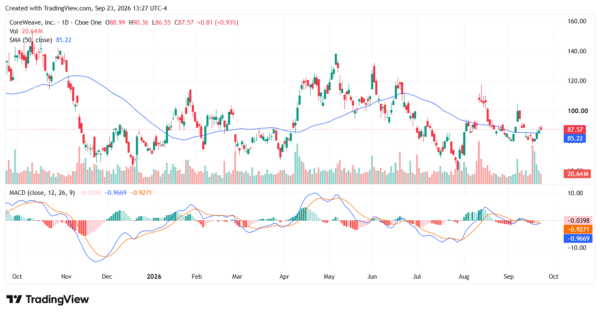
CoreWeave stock is showing some signs of stabilization after its recent decline. As of September 23, CRWV was trading around $87.57, slightly above its 50-day simple moving average of $85.22. That puts the stock back above an important intermediate-term trend indicator, although it has not yet established a decisive move higher.
The chart also shows near-term resistance around $90 to $95, followed by a more significant hurdle around $100. On the downside, the 50-day moving average near $85 could provide initial support, while the recent August and September lows create additional support zones in the upper-$70s to low-$80s.
The MACD remains close to the zero line, suggesting that momentum has not yet developed a strong directional signal. For CRWV, a sustained move above recent resistance could strengthen the technical picture, while a break back below the 50-day average would put the recent stabilization into question.
What Investors Should Watch Next
The next few quarters should help clarify which side of the debate has the stronger case.
Start with customer demand. Is CoreWeave continuing to sign contracts at attractive prices? Then look at execution. Can it bring new capacity online when promised and turn those commitments into revenue?
Finally, watch the cost of growth. Additional borrowing, interest payments and share sales all affect what shareholders ultimately receive from the AI opportunity.
CoreWeave offers exposure to a fast-growing market, and UBS sees its recent decline as a chance to buy into that growth. The stock’s future, however, depends on more than enthusiasm for AI. CoreWeave has to show that building more capacity creates enough value to cover the substantial bill.

