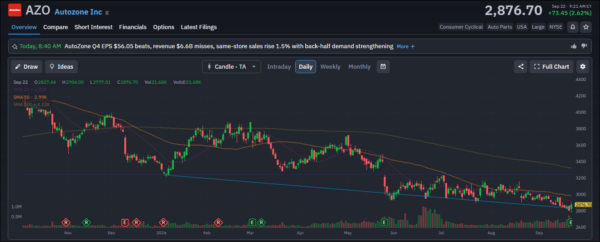
AutoZone Inc. (NYSE: AZO) spent $2 billion in Q4 buying back its own stock during fiscal 2026 at an average price of $3,496 a share. The stock is now sitting around $2,877.I started there instead of the $56.05 EPS beat or the $6.6 billion revenue number because that gap tells us something about where the market stands today.
See, AZO is still generating growth, still buying back stock aggressively and still expanding its store network, yet the shares are trading roughly 18% below the average price management paid for its own stock during the year.
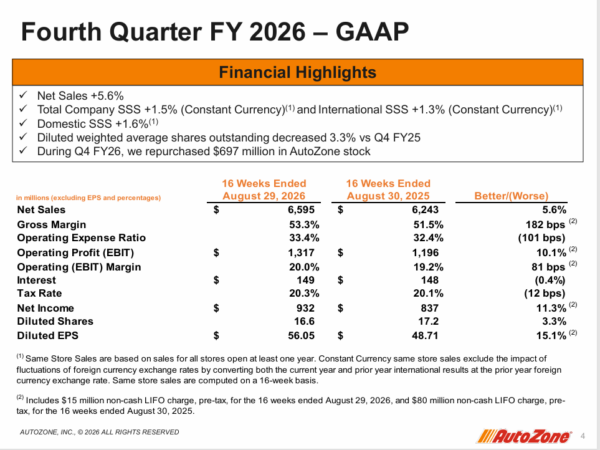
Now under the hood, Q4 sales rose 5.6% to $6.59 billion, net income reached $931.6 million, and diluted EPS jumped to $56.05 from $48.71. At the same time, domestic same-store sales came in at 1.6%, while total-company constant-currency comps landed at 1.5%. A quarter earlier, those figures were 4.1% and 3.9%.
That gives me a very specific way to read Q4 – the vehicle-preservation thesis is still producing demand, while AutoZone is pouring more capital into capturing that demand. The next part of the trade is figuring out what those investments are earning.
The Repair Economy Is Still Running
The preservation thesis from Q3 has another quarter behind it now, and one part of the business is making the case even harder to dismiss.
Domestic commercial sales jumped 8.6% to $1.91 billion in Q4, taking full-year commercial sales growth to 10.6%.
I like that number because commercial customers are professional repair shops, dealers, service stations, fleet owners and other businesses that need parts to keep vehicles working. The consumer comp may have slowed, but the professional side is still pulling hard. That gives AutoZone a nice demand setup heading into FY2027. Management said the first eight weeks of Q4 were difficult before sales strengthened during the final eight weeks, and it expects sales in all three countries to accelerate in the new fiscal year.
Now I want to see that acceleration show up in the comp numbers. A stronger commercial business gives AutoZone another source of growth, while the aging-vehicle thesis keeps feeding the broader replacement-parts market. If that combination pushes domestic comps back toward the levels seen earlier in FY2026, the stock gets a very different fundamental backdrop.
AutoZone Is Putting More Money Behind The Thesis
Management isn’t sitting around waiting for demand to arrive as AZO opened 374 stores during FY2026, taking the network to 8,031 locations. Inventory increased 10.1%, compared with 7.4% growth in annual sales, while capital spending rose to $1.50 billion from $1.37 billion.
That’s a meaningful capital commitment to a thesis that management clearly expects to keep working. Then adjusted after-tax ROIC fell from 41.3% to 35.8%, a 550-basis-point decline. That changes how I look at those 374 new stores. Store growth gives AutoZone more physical reach. Inventory gives customers a better chance of finding the part they need. Distribution investments can improve delivery speed. Commercial expansion can pull more repair-shop business into the network.
And all of those investments can create future earnings, but I want to see the return on that capital stabilize as the revenue catches up. If FY2027 brings the acceleration management expects and ROIC starts recovering, the investment cycle begins to look much more productive. If sales accelerate while returns continue sliding, the market has a different set of numbers to work with.
The Margin Bridge Tells Us Where The EPS Came From
Q4 gross margin expanded 182 basis points to 53.3%, and management gave us a clean bridge for the improvement: tariff refunds contributed 145 basis points, and a net non-cash LIFO benefit added another 105 basis points, while a higher commercial mix pulled in the other direction. That tells me how much weight to put on the margin expansion.
Those two disclosed benefits contributed 250 basis points of the 182-basis-point reported improvement. Strip them out mechanically, and the underlying bridge points to roughly 68 basis points of pressure.
I wouldn’t forecast future margins by simply removing those items. I’d use the bridge to separate operational improvement from quarter-specific assistance. Operating expenses also moved to 33.4% of sales from 32.4%, with AutoZone attributing the increase primarily to deleverage from its growth initiatives.
So the FY2027 setup becomes pretty clear: stronger sales need to start carrying more of the expense load from the expansion program.
AZO’s Buyback Now Has A Price Tag
This brings me back to where we started. AZO repurchased 579,000 shares during FY2026 for $2.0 billion, paying an average of $3,496 per share. It finished the year with another $1.61 billion available under its authorization. With AZO around $2,877 on your chart, the market has placed the shares substantially below the company’s FY2026 average repurchase price.
That’s a benchmark I can actually trade around. The chart has already broken the $3,250-$3,300 support zone that repeatedly held through 2026. AZO now sits below the 20-day average near $2,920, the 50-day near $2,990 and the 200-day near $3,330, with the long-term descending trendline still overhead.
For me, the next signal is straightforward: can improving FY2027 comps and commercial growth start pulling those returns higher while the stock works back through its moving averages? The business is still getting paid to keep America’s cars alive.
Now AZO has to show that the next billion dollars it puts behind that business can earn its way back into the stock.