ajax loader

Loading...


Ride-the-Wave Strategy – Best for Stock Traders

Ride-the-Wave targets multi-day price momentum following a company’s earnings announcement (EA). With this strategy:

  1. Buy a stock one day post-EA if a stock reacts positively post-earnings:
    1. Near the close of trading the EA-day for a pre-market-EA
    2. Near the close of the following day for a post-market-EA
  2. Sell-to-close after 7-10 days, or possibly earlier if a desired price target is reached

Similarly,

  1. short a stock one day post-EA if a stock reacts negatively post-earnings:
    1. near the close of trading the EA-day for a premarket-EA
    2. near the close of the following day for a post-market-EA
  2. then buy-to-close after 7-10 days, or possibly earlier if a desired price target is reached

Important: Ride-the-Wave is predicated on significant price momentum triggered by an EA. The 7-10 day scenario is the maximum trade hold-time. If you see post EA-momentum is halted or reversed by a significant opposite move, re-evaluate your presence in the trade.

This popular StockEarnings screen below will give you a list of stocks that historically exhibit significant price momentum following an EA for the next seven days:

  1. Stocks exhibiting positive post-EA price moves are buy-candidates
  2. Stocks exhibiting negative post-EA price moves are sell/short-candidates

The screen includes those stocks whose Earnings just came out in last two days.

Screen criteria:

  1. Earnings Date Start Date : Current Date + -1 Day
  2. Earnings Date End Date : Current Date + -2 Days
  3. Predicted Move (Next Day) Max : 7%
  4. Predicted Move (On 7th Day) Min : 7%

Strategy Guideline:

  1. Buy the stock if stock has reacted positively. Short the stock if stock has reacted negatively (see above).
  2. Close the position in 7-10 days, or possibly earlier based on price move.

Volatility Crush Strategy - Best for Options Traders

The Volatility Crush strategy is used with stocks that typically experience relatively low-to-moderate price moves (≤4%) following their Earnings Announcements (EA). The basic trade idea is to sell put or call options right before the EA, collecting a credit when options premium is very high due to elevated implied volatility (IV). You then close the position right after the EA by buying the option back much cheaper due to the significant drop in IV that occurs after the mystery of the EA disappears. In assessing this trade, you need to do your homework to ensure you collect sufficient premium to make the trade worthwhile.

This trade is practical due to the low-to-moderate price-move after the EA, which generally won’t significantly affect the options price, unlike an “action” stock, which experience great price moves post-EA. With these symbols, if you’re on the right side of the price move, that’s a great thing. But if you’re on the wrong side of the move, not so great. Consequently, by minimizing the effect of the post-EA price move, you have a much better chance to profit from the reduction in IV without it being ruined by a violent price move.

For this trade, open the position either (1) the night before the EA when the company announces earnings or (2) during the EA day when it announces post-market, generally capturing IV at or close to its peak.

For this trade, open the position either (1) the night before the EA when the company announces earnings or (2) during the EA day when it announces post-market, generally capturing IV at or close to its peak.

This popular stockearnings screen will give you a list of stocks which do not react more than 4% fpost-EA. It includes only those stocks whose earnings are releasing next day.

Screen criteria:

  1. Earnings Date Start Date : Current Date + 1
  2. Earnings Date End Date : Current Date + 1
  3. Predicted Move (Next Day) Max : 4%
  4. Options Type: Weekly

Strategy Guideline:

  1. Options Strategy: Sell Call and Put
  2. Options Strike Price: Current Stock Price – (% Predicated Move x 2)
  3. Expiration Date: It should generally be the closest expiry immediately after the EA.
  4. Buy Insurance: Buying back Call and Put at Strike price which 10% lower than Sell Strike Price is optional but recommended.

Watch Video for More Detail

Volatility Rush Strategy - Best for Options Traders

The Volatility Rush takes advantage of increasing options premiums into earnings announcements (EA) caused by an anticipated rise in Implied Volatility (IV). With this strategy, Buy a Call and Put at-the-money (a long straddle) 2-3 weeks before the EA when IV is lower. Sell the position either (1) the night before the EA when the company announces earnings pre-market, or (2) during the EA day when it announces post-market, generally capturing IV at or close to its peak.

This popular screen will give you a list of stocks whose Options premiums tend to rise into Earnings. It includes only those stocks whose Earnings are at least two weeks away from today.

Screen criteria:

  1. Earnings Date Start Date : Current Date + 15 Days
  2. Earnings Date End Date : Current Date + 30 Days
  3. Predicted Move (Next Day) Min : 5%
  4. Options Type: Weekly or Monthly if that lines up with the two to three-week lead-time for entering the trade

Strategy Guideline:

  1. Buy a Straddle at or close to the money two to three weeks pre-EA.
  2. Sell the position either the night before the EA when the company announces earnings pre-market, or during the EA day when it announces post-market.
  3. Expiration date should generally be the closest expiry immediately after the EA.
  4. Straddle price should not be more 60% of predicted move.

Predicted Move (Volatility)

Similar to Implied Volatility in Options. Expected volatility % based on our Proprietary Volatility Predication Model. We are expecting that stock price will likely to reach % in either direction by the end of next trading session after Earnings are released and not necessarily the closing volatility %.

Why is it important?

    This indicator helps

  1. Knowing expected volatility in stocks after Earnings helps to decide trading stocks before Earnings Announcement.
  2. Taking Advantage of volatility collapse following Earnings Results by using Advance Options strategies such as Spread and Straddles.

Since Last Earnings

Change in share price since last Earnings release.

Why is it Important?

When share has gained more than 10% since it's last Earning release, it tends to over react to minor bad news and give up some gains if not all. So, it contains more downside volatility than upside When share has dropped more than 10% since it's last Earning release, it tends to over react to minor good news and recover some drops if not all. So, it contains more upside volatility than downside.

EPS Surprise (%)

Occurs when a company's reported quarterly or annual profits are above or below analysts' expectations. Here is the formula to derive % EPS Surprice:

Actual EPS - Estimated EPS
------------------------------------- x 100
Estimated EPS

Why is it Important?

Earnings surprises can have a huge impact on a company's stock price. Several studies suggest that positive earnings surprises not only lead to an immediate hike in a stock's price, but also to a gradual increase over time. Hence, it's not surprising that some companies are known for routinely beating earning projections. A negative earnings surprise will usually result in a decline in share price.

Next Day Price Change (%)

Next Regular trading session Closing price following Earnings result.

For After Market Close Earnings, It is a next trading day closing price. For Before Market Open Earnings, It is the same trading day closing price.

Why is it Important?

Next Day price change is a reaction of Earnings result.

KB Home Finds a Bright Spot as Its Backlog Starts Growing Again

Posted on Sep 23, 2026 by Grayson Cavern

KB Home Finds a Bright Spot as Its Backlog Starts Growing Again

KB Home’s backlog just grew for the first time in four years, even as the company sold fewer homes, delivered fewer homes and watched buyers become more cautious.

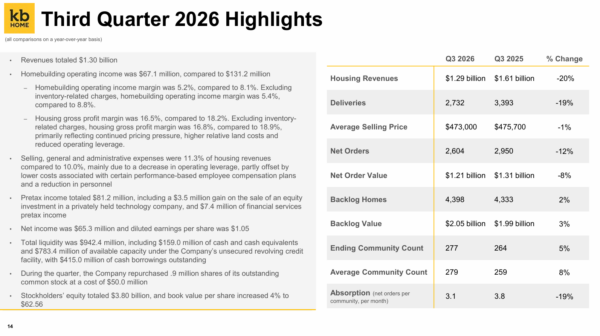
That combination tells me more about KB Home (NYSE: KBH) than the $1.05 in diluted EPS because it shows exactly where the business is improving and where the housing market is still pushing back. Third-quarter revenue fell 20% to $1.30 billion, deliveries fell 19% to 2,732 homes and net orders fell 12% to 2,604, yet ending backlog increased 2% to 4,398 homes worth $2.05 billion, up 3%.

You’ll discover that KBH is rebuilding visibility through its Built-to-Order model, but the backlog grew because deliveries fell faster than orders, not because demand suddenly accelerated.

The Backlog Is Growing Because the Business Is Moving Slower


The order numbers make the first part of this story clear. KBH generated 2,604 net orders during the quarter versus 2,950 a year earlier, while monthly net orders per community dropped to 3.1 from 3.8 and cancellations increased to 18% from 17%. At the same time, the company delivered 2,732 homes, 661 fewer than the 3,393 delivered in last year’s third quarter, allowing the remaining backlog to expand even with fewer new orders coming in.

That changes how I read the 4,398-home backlog. It gives KBH more homes already contracted and waiting to become revenue, but it does not show that buyers suddenly returned to the market. KBH said housing conditions weakened since its June earnings report as higher mortgage rates pressured affordability and broader economic and geopolitical uncertainty made prospective buyers more cautious.
kb home - StockEarnings

There is also a clear regional split inside that backlog. The West Coast finished the quarter with 1,589 homes worth $1.02 billion, compared with 1,294 homes worth $834 million a year earlier, while the Southwest, Central and Southeast all carried fewer backlog homes than they did last year.

All of which makes the backlog more useful as a visibility metric than as a demand signal, and it leads directly to the part of KBH’s business that is changing the quality of that visibility.

BTO Is Giving KBH More Control Over Its Capital

Nearly three-quarters of third-quarter deliveries came from Built-to-Order homes, and management said the higher BTO mix contributed to sequential improvement in housing gross profit margin. KBH has also expanded its community footprint, with average communities up 8% to 279 and ending communities up 5% to 277, giving the company more places to sell even while demand remains soft.

BTO also changes when KB Home commits capital relative to when it gets a buyer. With more homes sold before construction, the company can match construction activity more closely to actual orders instead of building as aggressively ahead of demand. The balance sheet shows some evidence of that shift: inventory increased 5% to $5.98 billion, while lots owned or under contract declined 5% to 61,581. KBH did spend $722.3 million on land and land development during the quarter, 40% more than a year earlier, but nine-month land-related investment still fell 8% to $1.79 billion.

That leaves KBH carrying more backlog without simply loading up on land and inventory, which is the kind of operating change a homebuilder needs when buyers remain cautious. The catch is that better capital control has not yet repaired the economics of each home.

Pricing Pressure Is Still Eating Into The Margin

Third-quarter housing gross profit margin fell to 16.5% from 18.2%, or 16.8% from 18.9% after excluding inventory-related charges, with KBH pointing to continued pricing pressure, higher relative land costs and reduced operating leverage. SG&A also rose to 11.3% of housing revenue from 10.0%, leaving homebuilding operating income at $67.1 million versus $131.2 million a year earlier.

The nine-month figures show how deep that pressure has run. Revenue fell to $3.49 billion from $4.54 billion, deliveries declined 19% to 7,497, average selling price dropped 5% to $462,900, and net income fell to $126.1 million from $327.3 million. Diluted EPS came in at $2.00 versus $4.60.

KBH expects the fourth quarter to improve sequentially, with 3,000 to 3,500 deliveries and $1.45 billion to $1.65 billion of housing revenue, but the gross margin guide of 16.0% to 16.6% still leaves profitability below where it stood a year ago. Full-year housing gross margin should land at 16.0% to 16.2%, alongside $4.90 billion to $5.10 billion of housing revenue.

That leaves KBH with a specific job: turn the better BTO mix and larger backlog into higher-quality revenue before pricing pressure erodes the benefit.

KBH Needs the Numbers to Catch Up

The chart adds another layer to the setup. KBH sits around $47.91, below its 20-day moving average near $50.62, its 50-day near $54.10 and its 200-day near $55.65, after falling from roughly $62 in July and breaking the rising support line that had carried the shares higher from the spring.

Yet KBH reported book value of $62.56 per share at August 31, up 4% year over year, while repurchasing $175 million of stock during the first nine months, including $50 million during the third quarter. The company still had $725 million available under its current repurchase authorization.

I would watch the operating numbers rather than try to call the bottom from the chart. The backlog has started growing again, BTO now dominates deliveries and inventory growth remains contained, but orders per community, cancellations, pricing and margins still show a housing market making growth expensive.

KBH has rebuilt some visibility into the business. The next step is proving that those 4,398 homes can become profitable revenue without giving the margin back along the way.

Join over 1.2M+ investors/traders who receive daily and weekly notable earnings alerts with predicted move
