Berkshire Hathaway (NYSE: BRK-B) is buying more of Lennar (NYSE: LEN) at an uncomfortable time for homebuilders. Mortgage rates are rising, many buyers are struggling with monthly payments, and Lennar just reported a difficult quarter. Yet Berkshire bought approximately 2.7 million of the company’s Class A shares over three trading days.
So, what does Berkshire see in a stock that has taken such a beating? The appeal may be the very thing making other investors nervous: a housing slowdown. If Berkshire believes today’s pressures will eventually ease, it can buy a large homebuilder while expectations are low. That is a long-term argument, though. Lennar’s near-term problems are real.
Why Homebuilders Are Under Pressure
For a potential buyer, the challenge is straightforward. A higher mortgage rate means a higher monthly payment, even if the price of the house stays the same. Freddie Mac reported that the average 30-year fixed mortgage rate reached 6.95% for the week of September 17. That was up from 6.76% the previous week and 6.26% a year earlier. Those changes can determine whether a household qualifies for a loan or decides to keep renting.
Builders have ways to respond. They can offer mortgage rate incentives, adjust prices or build smaller homes. But those measures cost money. A builder may keep sales moving while earning less on each home it delivers.
That tension showed up in Lennar’s latest results.
In its fiscal third quarter, the company delivered 20,840 homes, down 3% from a year earlier. New orders fell 9% to 20,879 homes, while total revenue came in at $8.0 billion. Lennar’s gross margin on home sales was 15.8%.
The company said higher mortgage rates and weaker confidence were causing more customers to delay a purchase. That is a tough environment for any builder trying to plan construction, manage costs and protect profit margins.
Why Berkshire’s Purchase Stands Out
Berkshire already has substantial ties to housing. In July, it completed its acquisition of Taylor Morrison, adding a national homebuilder to its existing site-built operations. Its Clayton businesses also give it experience across other parts of the housing market. Buying Lennar shares adds another investment in the sector, although owning stock is different from running a company. The Lennar purchase also shows a willingness to look past a weak quarter.
Investors can still see the possible logic. Lennar is a large, established builder. If mortgage rates eventually ease and more buyers return, it could be better placed to benefit than a smaller rival with fewer resources. In the meantime, Berkshire appears comfortable increasing its exposure while the market focuses on the downturn.
There is a reason to be cautious about that argument. Lower rates are not guaranteed, and affordability involves more than borrowing costs. Home prices, wages, insurance and the supply of available homes all affect what buyers can manage. Lennar may need to keep offering incentives to close sales, which could continue to squeeze margins.
LEN Stock Technical Analysis: Can Berkshire’s Buying Spark a Rebound?
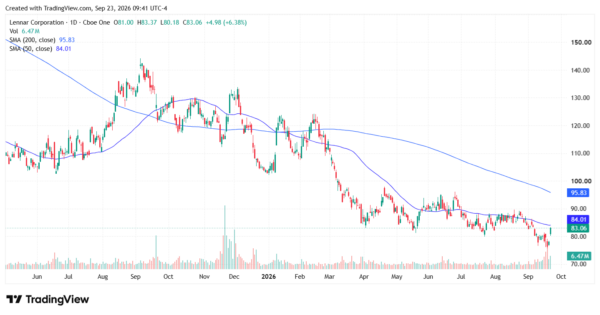
LEN stock closed at $83.06 on September 22, rebounding 6.38% after Berkshire’s purchase was disclosed. The move pushed LEN back above its 20-day moving average, but the stock remains below its 50-day moving average near $84.01 and well below its 200-day moving average near $95.83. That leaves the longer-term chart under pressure despite the sharp one-day rally.
Near-term resistance appears around $84 to $85, while technical levels identify support around $81, $79 and the recent 52-week low near $75.70. RSI around 51 is close to neutral, suggesting the latest rally has improved momentum without pushing the stock into technically overbought territory. A sustained move above the 50-day average would provide a more meaningful test of whether LEN can extend its rebound.
How Lennar Compares With Other Homebuilders
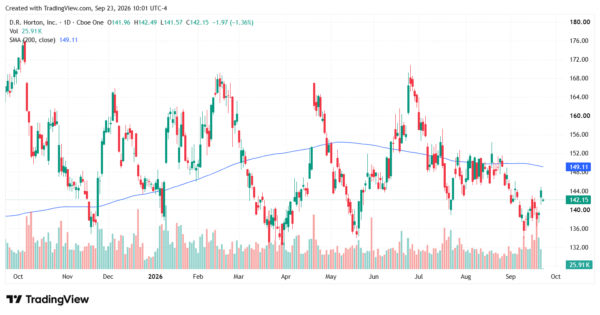
Lennar isn’t facing these challenges alone. PulteGroup (NYSE: PHM) and D.R. Horton (NYSE: DHI) are also dealing with an environment shaped by elevated mortgage rates and affordability pressures. PulteGroup shares were still about 18% below their 52-week high as of September 17, while D.R. Horton shares were also trading below their recent peak.
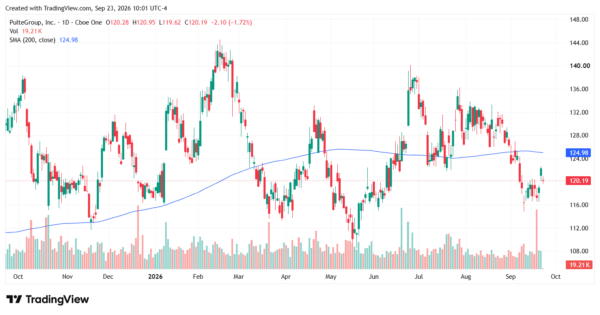
The broader pressure on homebuilders has included weaker demand and rising cancellations, making Lennar’s struggles part of a larger industry story rather than an isolated problem. That makes Berkshire’s Lennar purchase particularly notable: the company is increasing its housing exposure while the industry’s operating environment remains challenging.
What Investors Should Watch Next
The most useful sign may be new orders. If more buyers begin signing contracts without Lennar having to offer costly incentives, it would suggest demand is improving in a way that can support earnings.
Berkshire’s buying gives Lennar a notable vote of confidence. It does not make the housing slowdown disappear or settle when conditions will improve. For now, the story is simple: Berkshire sees enough potential to buy during a difficult stretch, while the company still has to show that it can turn housing demand into stronger profits.

