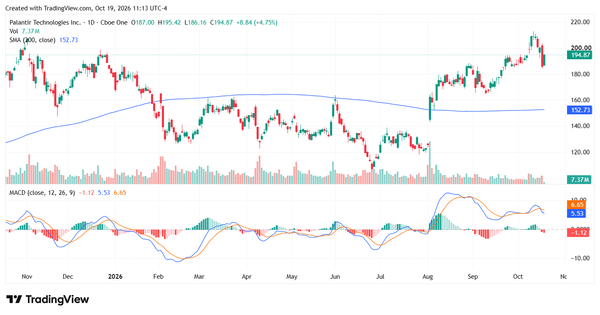
Palantir Technologies (NASDAQ: PLTR) will release its third-quarter results on November 2, after the market closes, followed by a conference call at 5 p.m. Eastern. For shareholders, the question is whether demand for its artificial intelligence software can support another strong quarter and an even better outlook.
Estimates call for earnings of about 42 cents per share on revenue of $2.22 billion. That would represent roughly double the earnings and approximately 88% revenue growth compared with the same quarter last year. Palantir’s own third-quarter revenue forecast is between $2.160 billion and $2.164 billion. That puts both published revenue estimates above management’s outlook, suggesting analysts are already looking for the company to outperform its guidance.
Analysts Love PLTR Stock Heading into Earnings
Heading into its earnings call, analysts at Barclays have an overweight rating on the stock, noting that it has a competitive moat that allows for growth and respectable margins. The firm also has a price target of $265 a share on Palantir.
Goldman Sachs also has a buy rating on the stock, with a price target of $230.
According to the firm, as quoted by Seeking Alpha: “The two key debates we hear from investors at Palantir’s current $8B revenue run rate and ~100% growth rate are 1) has the best part of Palantir’s AI opportunity already been realized, or is the market deep enough for another set of higher revisions? And 2) how sustainable is the FDE model? Our primary takeaway from our most recent set of industry conversations is that the stock is setting up for another phase of outperformance into 2027.”
D.A. Davidson also lifted its price target from $200 to $250. The firm sees an opportunity as more customers seek greater control over their AI systems and data, pointing to the company’s ability to help businesses manage both.
“Palantir’s push into data sovereignty is resonating with customers,” said D.A. Davidson analyst Gil Luria, as quoted by Seeking Alpha. “Customers are getting savvier about what AI model they need and how to work with a range of models, and Palantir is capitalizing on that trend. Trust means Palantir is naturally positioned to become the control plane, orchestration layer, and harness provider for a wide range of customers. Palantir is creating those layers for customers and solving the problem of choosing models and managing token costs.”
Can Commercial Customers Keep Driving Palantir’s Growth?
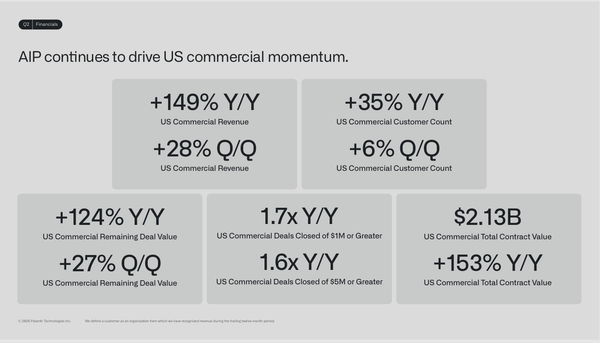
One of the biggest areas to watch is Palantir’s U.S. commercial business, which serves companies rather than government agencies. In the second quarter, U.S. commercial revenue increased 149% from a year earlier. Management raised its full-year forecast for that business to more than $3.424 billion, representing growth of at least 134%. Those figures set a demanding standard for the upcoming report.
The commercial business may attract much of the attention, but government customers remain important. Palantir’s U.S. government revenue increased 90% to $809 million in the second quarter, according to Reuters. That gives investors another substantial business to watch alongside corporate AI spending.
Profits and the Outlook Could Decide the Reaction
Palantir reported a 62% adjusted operating margin in the second quarter, compared with a 47% margin under standard accounting rules. Its third-quarter guidance calls for adjusted operating income of $1.292 billion to $1.296 billion.
The question is whether the company can maintain strong profitability while hiring, supporting customers, and expanding deployments.
Then comes guidance. Palantir’s existing full-year revenue forecast is $8.150 billion to $8.158 billion. Any revision will help investors judge management’s confidence heading into year-end.
My view is that the most persuasive report would combine a meaningful revenue beat, continued customer expansion, and a stronger outlook.