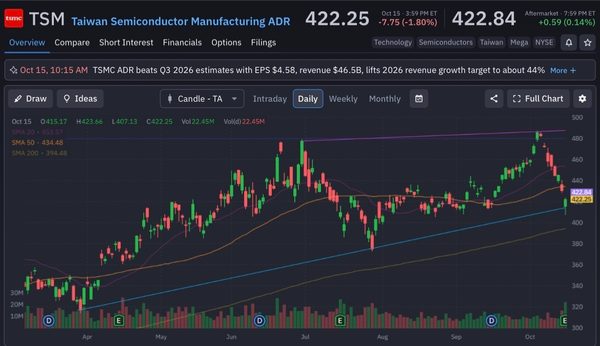
Taiwan Semiconductor Manufacturing (NYSE: TSM) just posted its Q3 earnings with 41.2% year-over-year revenue growth, raised its next-quarter revenue outlook to as much as $54.3 billion, and is ramping its next-generation 2nm process. Yet TSMC stock closed October 15 at $422.25, nearly $60 below its recent high around $480.
That gap takes us back to the question in our earnings preview: can TSMC turn relentless AI demand into sustained growth while keeping its margins intact? The Q3 numbers strengthen the growth case. The margin trend and stock chart are still things the company has to prove to investors.
The Revenue Beat Was Real
TSMC reported Q3 revenue of $46.72 billion, up 41.2% year over year and 16.2% sequentially, beating its own forecast of $44.6 billion to $45.8 billion. Net income rose 68.7% year over year to NT$ 763.06 billion, while diluted EPS increased 68.7% to NT$29.43, equivalent to $4.60 per ADR.
The sequential acceleration stands out. Q2 revenue was $40.20 billion, up 33.7% year over year, so the growth rate picked up again in Q3. TSMC is converting demand from its customers into reported sales at a faster clip, and the latest quarter came in above management’s own range.
For semiconductor investors, that is a stronger signal than a beat against analyst estimates alone. Management set the bar, then cleared it. But the next question is whether the revenue ramp can keep delivering without the cost of bringing new capacity online eating into profitability.
The 2nm Ramp Is Starting to Show
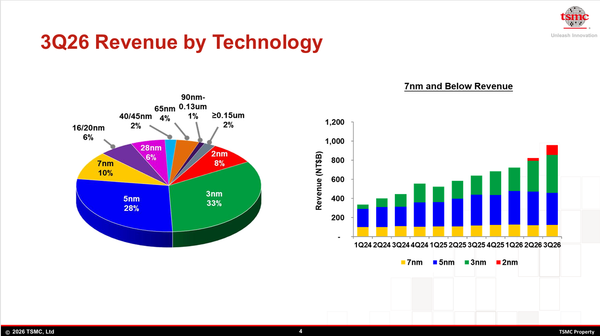
The wafer mix provides another piece of evidence. Technologies at 7nm and below accounted for 79% of wafer revenue in Q3, up from 77% in Q2. Within that mix, 2nm rose from 3% to 8%, while 3nm increased from 30% to 33%. Five-nanometer technology declined from 33% to 28%.
The 2nm contribution is particularly worth tracking. It is growing from a small base, while 3nm remains a major part of the business. As TSMC ramps newer process technologies, the company is moving more wafer revenue through its leading-edge manufacturing portfolio. That gives investors a measurable way to track the advanced-chip demand behind the AI trade, rather than relying on broad promises about data-center spending.
There is a catch in the profitability figures. Gross margin fell to 66.4% in Q3 from 67.7% in Q2, while operating margin declined to 58.7% from 60.3%. Both metrics remained high, but the sequential decline means revenue growth has not been accompanied by expanding margins. I’d keep an eye on this. TSMC is shipping more, and newer nodes are taking a larger share of wafer revenue. The margin line still needs to show how efficiently the company can scale that production.
Q4 Guidance Raises the Bar Again
Management forecast Q4 revenue of $52.3 billion to $54.3 billion, with gross margin of 65% to 67% and operating margin of 56.5% to 58.5%. It also pointed to continued demand for leading-edge process technologies and a steep ramp-up of 2nm.
At the midpoint, the revenue forecast implies approximately 14% sequential growth from Q3’s $46.72 billion. That is another substantial step up in sales, while the projected gross-margin range sits around Q3 levels. Operating margin could improve modestly, but guidance does not point to an immediate return to Q2’s 60.3%.
The next quarter therefore puts two metrics in direct competition: how much revenue TSMC can bring through the door, and how much profit it retains as the 2nm ramp gathers pace. A revenue beat would extend the growth trend. Better-than-guided margins would add evidence that the ramp can scale efficiently.
TSM Needs to Reclaim $434
The chart has weakened since the preview’s $480 resistance test. TSM closed October 15 at $422.25, below its 20-day moving average at $453.57 and 50-day average at $434.48, while remaining above its 200-day average at $394.48.
The retreat from the highs has put the stock beneath short- and medium-term trend gauges, despite the strong operating results.
The first hurdle is $434–$435, around the 50-day moving average. A reclaim would put the stock back above that near-term resistance. The 20-day average near $454 comes next, with $480 remaining the major ceiling from the prior peak. On the downside, the rising trendline around the low $410s and the 200-day average near $394 are the levels to watch.
Our preview focused on whether TSMC could deliver growth while protecting margins. Q3 answered the first half emphatically; Q4 guidance points to another revenue jump. The margin trend is still the unresolved part. I like the business, but after the rejection near $480, I would want to see TSM reclaim $434 before treating the pullback as finished.