Amazon’s (NASDAQ: AMZN) upcoming earnings report will give investors a fresh look at growing demand for artificial intelligence and the cost of keeping up with it.
Several analysts have recently raised their price targets, while Goldman Sachs added Amazon to its conviction list of preferred stocks. But turning that optimism into another move higher could require more than just one earnings beat. Investors will want evidence that Amazon’s spending is translating into lasting, profitable growth. The company is expected to report third-quarter results on Oct. 29, after the closing bell.
What Wall Street Expects
Wall Street expects Amazon to deliver another quarter of higher sales, although earnings forecasts vary across data providers. Right now, there are estimates of EPS of $1.96 per share on revenue of about $202.1 billion.
Management projected third-quarter revenue between $197 billion and $202 billion, or growth of 9% to 12%. It also forecast operating income between $22.5 billion and $26.5 billion, compared with $17.4 billion a year earlier.
Investors should also account for the timing of Prime Day. Amazon said that excluding the event’s impact in both years would make projected third-quarter sales growth nearly four percentage points higher. Simply comparing quarterly growth rates could therefore give an incomplete picture of demand.
AWS Has a High Bar to Clear
Amazon Web Services (AWS), the company’s cloud-computing division, will likely be central to the earnings reaction. In the second quarter, AWS revenue increased 37% to $42.2 billion, its fastest growth in 18 quarters. The division generated $16.6 billion in operating income, accounting for roughly 60% of Amazon’s total.
Those numbers explain why investors watch AWS so closely. Stronger cloud demand can have an outsized effect on the company’s overall profits. The question now is whether that momentum continued through September. Investors will be looking for evidence that customers are expanding their cloud workloads and spending more on AI services.
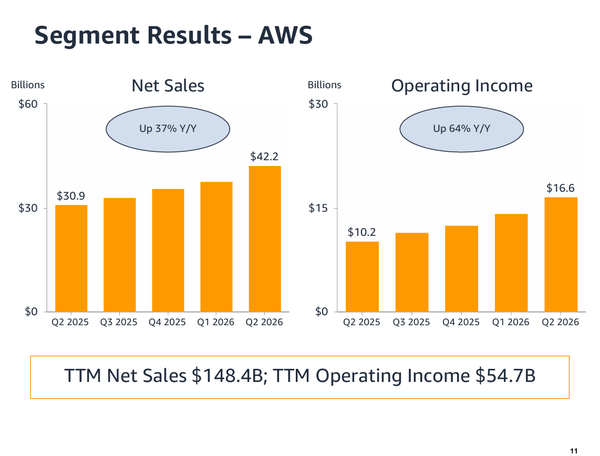 Source: Amazon
Recent Analyst Target Increases Add Optimism
Several recent analyst actions have strengthened the bullish case.
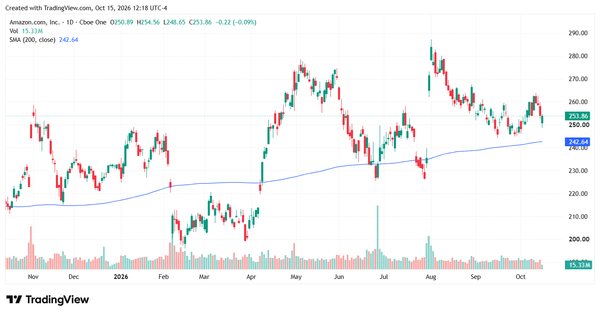
On Oct. 6, Tigress Financial raised its AMZN price target to $385 from $315 while maintaining a Buy rating. That represents a substantial increase in the firm’s valuation outlook.
Rosenblatt also raised its target, lifting it to $360 from $335 on September 30 and maintaining a Buy rating. The firm argued that concerns about AI shopping assistants disrupting the company’s advertising business were overstated. Its view is that Amazon can adapt as shopping habits evolve. Meanwhile, Goldman Sachs added Amazon to its conviction list on October 1 with a $375 price target, giving the stock another prominent endorsement.
The Spending Question Could Decide the Reaction
Amazon’s growth opportunity comes with a considerable bill.
Management’s 2026 capital-spending estimate reached approximately $220 billion, according to reporting on its second-quarter earnings call. Meanwhile, Amazon reported negative free cash flow of $7.6 billion over the twelve months through June, largely reflecting increased investment in AI infrastructure. Investors will want a clearer sense of when that investment can produce stronger cash generation.
Ultimately, Amazon needs to connect three things: healthy customer demand, profitable growth, and a credible return on spending. Strong AWS results and an encouraging holiday outlook could reinforce the recent bullish analyst calls. Another increase in spending without comparable progress could leave investors asking harder questions.
For AMZN investors, this earnings report comes down to a fairly simple question: Is all that spending starting to pay off? Higher sales would be encouraging, but stronger profits and a clearer path to generating cash would give shareholders more reason to feel confident. The recent analyst target increases suggest there’s optimism heading into the report. Now the company needs to back it up and show that it can keep growing without the bill growing faster.

