ajax loader

Loading...


Ride-the-Wave Strategy – Best for Stock Traders

Ride-the-Wave targets multi-day price momentum following a company’s earnings announcement (EA). With this strategy:

  1. Buy a stock one day post-EA if a stock reacts positively post-earnings:
    1. Near the close of trading the EA-day for a pre-market-EA
    2. Near the close of the following day for a post-market-EA
  2. Sell-to-close after 7-10 days, or possibly earlier if a desired price target is reached

Similarly,

  1. short a stock one day post-EA if a stock reacts negatively post-earnings:
    1. near the close of trading the EA-day for a premarket-EA
    2. near the close of the following day for a post-market-EA
  2. then buy-to-close after 7-10 days, or possibly earlier if a desired price target is reached

Important: Ride-the-Wave is predicated on significant price momentum triggered by an EA. The 7-10 day scenario is the maximum trade hold-time. If you see post EA-momentum is halted or reversed by a significant opposite move, re-evaluate your presence in the trade.

This popular StockEarnings screen below will give you a list of stocks that historically exhibit significant price momentum following an EA for the next seven days:

  1. Stocks exhibiting positive post-EA price moves are buy-candidates
  2. Stocks exhibiting negative post-EA price moves are sell/short-candidates

The screen includes those stocks whose Earnings just came out in last two days.

Screen criteria:

  1. Earnings Date Start Date : Current Date + -1 Day
  2. Earnings Date End Date : Current Date + -2 Days
  3. Predicted Move (Next Day) Max : 7%
  4. Predicted Move (On 7th Day) Min : 7%

Strategy Guideline:

  1. Buy the stock if stock has reacted positively. Short the stock if stock has reacted negatively (see above).
  2. Close the position in 7-10 days, or possibly earlier based on price move.

Volatility Crush Strategy - Best for Options Traders

The Volatility Crush strategy is used with stocks that typically experience relatively low-to-moderate price moves (≤4%) following their Earnings Announcements (EA). The basic trade idea is to sell put or call options right before the EA, collecting a credit when options premium is very high due to elevated implied volatility (IV). You then close the position right after the EA by buying the option back much cheaper due to the significant drop in IV that occurs after the mystery of the EA disappears. In assessing this trade, you need to do your homework to ensure you collect sufficient premium to make the trade worthwhile.

This trade is practical due to the low-to-moderate price-move after the EA, which generally won’t significantly affect the options price, unlike an “action” stock, which experience great price moves post-EA. With these symbols, if you’re on the right side of the price move, that’s a great thing. But if you’re on the wrong side of the move, not so great. Consequently, by minimizing the effect of the post-EA price move, you have a much better chance to profit from the reduction in IV without it being ruined by a violent price move.

For this trade, open the position either (1) the night before the EA when the company announces earnings or (2) during the EA day when it announces post-market, generally capturing IV at or close to its peak.

For this trade, open the position either (1) the night before the EA when the company announces earnings or (2) during the EA day when it announces post-market, generally capturing IV at or close to its peak.

This popular stockearnings screen will give you a list of stocks which do not react more than 4% fpost-EA. It includes only those stocks whose earnings are releasing next day.

Screen criteria:

  1. Earnings Date Start Date : Current Date + 1
  2. Earnings Date End Date : Current Date + 1
  3. Predicted Move (Next Day) Max : 4%
  4. Options Type: Weekly

Strategy Guideline:

  1. Options Strategy: Sell Call and Put
  2. Options Strike Price: Current Stock Price – (% Predicated Move x 2)
  3. Expiration Date: It should generally be the closest expiry immediately after the EA.
  4. Buy Insurance: Buying back Call and Put at Strike price which 10% lower than Sell Strike Price is optional but recommended.

Watch Video for More Detail

Volatility Rush Strategy - Best for Options Traders

The Volatility Rush takes advantage of increasing options premiums into earnings announcements (EA) caused by an anticipated rise in Implied Volatility (IV). With this strategy, Buy a Call and Put at-the-money (a long straddle) 2-3 weeks before the EA when IV is lower. Sell the position either (1) the night before the EA when the company announces earnings pre-market, or (2) during the EA day when it announces post-market, generally capturing IV at or close to its peak.

This popular screen will give you a list of stocks whose Options premiums tend to rise into Earnings. It includes only those stocks whose Earnings are at least two weeks away from today.

Screen criteria:

  1. Earnings Date Start Date : Current Date + 15 Days
  2. Earnings Date End Date : Current Date + 30 Days
  3. Predicted Move (Next Day) Min : 5%
  4. Options Type: Weekly or Monthly if that lines up with the two to three-week lead-time for entering the trade

Strategy Guideline:

  1. Buy a Straddle at or close to the money two to three weeks pre-EA.
  2. Sell the position either the night before the EA when the company announces earnings pre-market, or during the EA day when it announces post-market.
  3. Expiration date should generally be the closest expiry immediately after the EA.
  4. Straddle price should not be more 60% of predicted move.

Predicted Move (Volatility)

Similar to Implied Volatility in Options. Expected volatility % based on our Proprietary Volatility Predication Model. We are expecting that stock price will likely to reach % in either direction by the end of next trading session after Earnings are released and not necessarily the closing volatility %.

Why is it important?

    This indicator helps

  1. Knowing expected volatility in stocks after Earnings helps to decide trading stocks before Earnings Announcement.
  2. Taking Advantage of volatility collapse following Earnings Results by using Advance Options strategies such as Spread and Straddles.

Since Last Earnings

Change in share price since last Earnings release.

Why is it Important?

When share has gained more than 10% since it's last Earning release, it tends to over react to minor bad news and give up some gains if not all. So, it contains more downside volatility than upside When share has dropped more than 10% since it's last Earning release, it tends to over react to minor good news and recover some drops if not all. So, it contains more upside volatility than downside.

EPS Surprise (%)

Occurs when a company's reported quarterly or annual profits are above or below analysts' expectations. Here is the formula to derive % EPS Surprice:

Actual EPS - Estimated EPS
------------------------------------- x 100
Estimated EPS

Why is it Important?

Earnings surprises can have a huge impact on a company's stock price. Several studies suggest that positive earnings surprises not only lead to an immediate hike in a stock's price, but also to a gradual increase over time. Hence, it's not surprising that some companies are known for routinely beating earning projections. A negative earnings surprise will usually result in a decline in share price.

Next Day Price Change (%)

Next Regular trading session Closing price following Earnings result.

For After Market Close Earnings, It is a next trading day closing price. For Before Market Open Earnings, It is the same trading day closing price.

Why is it Important?

Next Day price change is a reaction of Earnings result.

When It Comes to Return on Capital, CarMax (KMX) Stock Could Be Unbeatable

Posted on Oct 15, 2026 by Joshua Enomoto

When It Comes to Return on Capital, CarMax (KMX) Stock Could Be Unbeatable

With the economy taking a beating, used-auto dealership CarMax (NYSE: KMX) looks unappetizing, to say the least. Yes, KMX stock is up 31.5% on a year-to-date basis, but that serves to obscure the near-term picture. In the trailing month, investors have been rushing for the exits, enough so that the ticker has lost roughly 18% of value.

Again, you can blame the economy along with the Federal Reserve. Higher borrowing costs obviously aren’t helpful for the real estate market, but these days, many consumers are also struggling with vehicle purchases. It’s rough out there — it’s no surprise that KMX stock has floundered.

At the same time, the U.S. isn’t Europe — and by that, I simply mean that we’re really not a public-transportation-type of country overall. In many regions, it’s absolutely critical to have your own ride, and that’s where CarMax stock could potentially be interesting, especially following the latest series of drawdowns.

I get it: at prior lofty valuations, the premium associated with KMX stock simply didn’t make sense to most investors. CarMax is obviously worth billions of dollars, but it also needed a trimming if the current economic environment wanted such a reduction.

Still, as is sometimes the case, there’s always a possibility that the market overcorrects. Further, the news cycle is constantly shifting. Should positive developments materialize in the near future, CarMax stock could easily witness a contrarian sentiment boost.

And that’s really the argument at hand. No one’s denying that KMX stock presently looks like a terrible name — it’s awful, and it’s worrying. But as a debit-side options trader, we’re likely not going to profit from an observation apparent to everyone.

In other words, the question isn’t whether CarMax stock is in a bearish state. Rather, it’s whether the equity continues to be in this state or transitions to a bullish one.

Why the $55 Strike Price for KMX Stock Could Be in Play


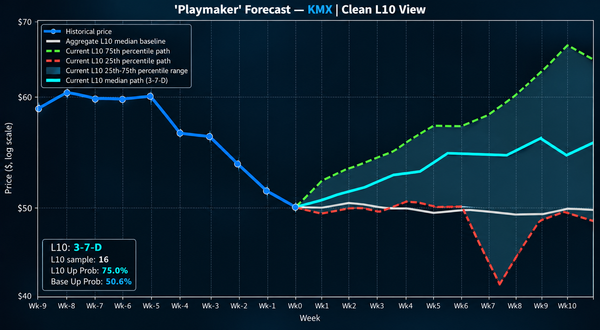
In the last two months, CarMax stock has printed 10 weekly candlesticks on the technical chart. Within this series, only three of the candlesticks saw positive price action, meaning that most of the activity centered on drawdowns. Naturally, this fact will have an impact on the immediate perception of KMX, irrespective of its broader history.

Significantly, though, we also know through past analogs of this exact quantitative sequence (using data over the trailing five years) that when this event materializes in the technical chart, KMX stock tends to rise higher, especially over the next five to six weeks. Indeed, the median uplift resulting from this analog would be around a 10.2% move.

If we apply this assumption to the current CarMax stock price ($50.81), we may infer a median terminal target of around $56 on Nov. 20. That may give us some buffer room to attack the $55 second-leg strike in a debit options spread.

Specifically, I’m looking at the 52.50/55 bull call spread expiring Nov. 20. Here, the net debit is nominally small at only $110. Should KMX stock rise through and trigger the $55 strike on expiration, the maximum payout stands at $140, a payout of nearly 127.3%. Mathematically, this trade features favorable asymmetry, as you potentially would profit more than what you would put in.

Favorable asymmetry also comes into play when discussing the expected return on capital (ROC) for this CarMax stock trade. As circumstances stand, the wager is $110, the American-style odds are 127.27, and the win probability is 26.96% — a figure calculated by KMX’s probability distribution for the November monthly options chain.

Plug these numbers into an expected value calculator, and you get an EV of $42.60 below parity, translating to an ROC of -38.73%. Now, that doesn’t sound great at first glance, but there’s a little trick that could potentially change everything.

Probabilities for CarMax Stock are Up for Grabs

When you’re looking at an EV calculation, there are only two variables (beyond the amount of the initial wager) that are technically capable of improving your debit option trade’s ROC: you can either enhance your payout or your probability of success.

While the former category seems simple enough (by choosing a spread that offers a greater reward), the amount of probabilistic risk you incur will also change. Obviously, that’s because a higher strike target is naturally presumed to suffer from a lower probability of exceedance. Plus, Wall Street isn’t in the business of giving you an extra payout boost just because you asked for it.

So, with begging for a higher payout (while still maintaining the same amount of risk) being completely out of the question, the only other possible solution is to change the probability of the trade. That might seem like an absurd concept because there’s a common myth that probabilities are set in stone.

However, you are not bound by the probabilities that the Wall Street machinery feeds you, which is basically some derivative of the Black-Scholes formula. A key assumption of Black-Scholes is that the target equity will undergo a random walk between now and the expiration date. If KMX stock does end up trading randomly, then yes, we can rely on the aforementioned probabilities.
kmx - StockEarnings

But the important meta question is whether or not that presupposition is justified for the equity at hand. I’m simply making the case that for CarMax stock specifically, this presupposition is not justified.

As I remarked earlier, KMX stock is currently structured in an extremely bearish state. Under this specific state, KMX tends to swing higher, transitioning from stark pessimism to contrarian optimism. Historically, this transition has been of such a magnitude that the November monthly 52.50/55 bull call spread may be realistically in play.

Quantifying the Potentially Coming Optimism

It must be said that the bullish options narrative for KMX stock comes with a warning: I’m basing my analysis on a very small sample size. As it stands, there just aren’t that many times when KMX suffers 70% session-wise drawdowns over a rolling 10-week period.

In fact, in the trailing five years, there have only been 16 such instances. However, CarMax stock has also exceeded the equivalent of the $55 strike on Nov. 20 a total of nine times. From an observational standpoint (within the dataset), we’re looking at a full-profit probability of 56.2%, not 26.96%.

Inserting this percentage changes everything in terms of ROC. Now, the 52.50/55 bull spread would have an EV of +30.50, which then dramatically raises the ROC to +27.73%.

Of course, history isn’t guaranteed to repeat, nor is it guaranteed to rhyme. But if you’re willing to take a shot on a speculative, contrarian opportunity before everyone else catches on, take a long look at CarMax stock.


Joshua Enomoto is a seasoned financial writer with a strong track record of in-depth stock analysis, offering clear, insightful commentary for retail investors across all levels of expertise. Renowned for his ability to blend analytical rigor with engaging wit, Joshua's work has been featured on leading investment platforms, including TipRanks, InvestorPlace, Barchart, Benzinga, and Fintel. He was also handpicked to spearhead high-impact initiatives such as InvestorPlace's "Trade of the Day" and Benzinga’s ETF coverage. As a frequent guest expert for CGTN America, Joshua discusses a wide range of economic, societal, and consumer market trends. A graduate of U.C. San Diego, Joshua brings a thoughtful and fresh perspective to complex financial narratives, helping enterprise clients connect with their audiences. He also composes music in his spare time.

Join over 1.2M+ investors/traders who receive daily and weekly notable earnings alerts with predicted move