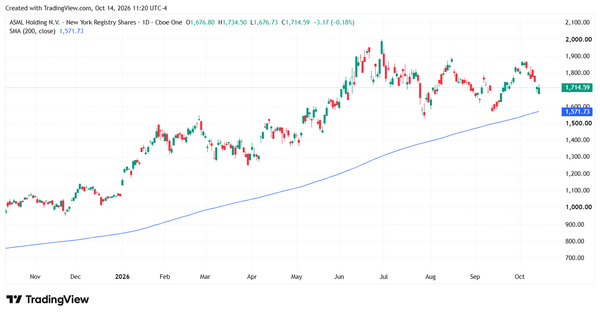
ASML’s (NASDAQ: ASML) latest earnings report gave investors something encouraging to think about, with some customers already looking at equipment orders for 2029 and 2030. That suggests the companies building the next generation of semiconductors see their investment needs stretching well beyond the current artificial intelligence boom.
For ASML, which makes machines essential to producing advanced chips, that could mean years of opportunity. But there is a challenge, too. The company needs to expand production fast enough to keep up. Its third-quarter results offered a closer look at both sides of that story.
Customers Are Planning Years Ahead
Much of the excitement surrounding ASML comes from its unusual position in the semiconductor industry.
The Dutch company is the world’s only supplier of extreme ultraviolet lithography machines, commonly called EUV systems. Chipmakers use these tools to print incredibly small patterns onto silicon, helping them manufacture the advanced chips that power modern technology.
Think of the company as a crucial equipment supplier behind the companies making the chips.
When manufacturers decide to expand advanced chip production, ASML has an opportunity to benefit. According to CEO Christophe Fouquet, customers continue to raise their equipment demand forecasts, largely because of their expectations for AI investment. Some are expressing interest in placing orders for delivery several years from now.
That is encouraging because investors have been asking how long today’s spending surge can last. Still, interest in a future purchase is different from a confirmed order. Customers can revise their plans, and equipment spending depends on whether chip demand develops as expected. The takeaway is that customers are planning further ahead, giving ASML a clearer view of potential business.
Profit Beats Expectations, While Sales Fall Slightly Short
ASML reported third-quarter net sales of €11.66 billion and net profit of €4.96 billion. Sales came in slightly below the €11.72 billion forecast. Profit, however, exceeded expectations of €4.1 billion. For investors, that makes this a mixed report with a strong earnings result.
The sales shortfall was relatively small. More attention is likely to fall on whether customers continue investing and whether the company can turn that demand into higher revenue.
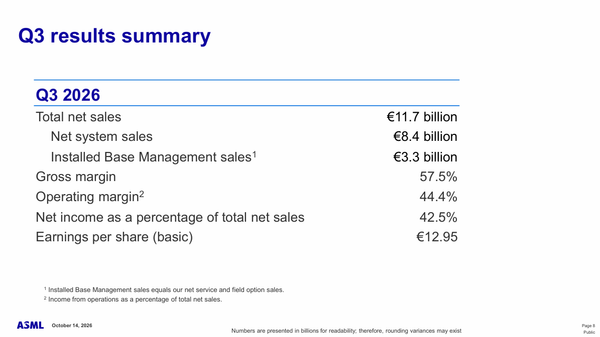
Management’s updated outlook provided some reassurance. ASML now expects full-year sales between €44 billion and €45 billion, raising the bottom of its previous range from €43 billion. It also forecast fourth-quarter sales of €14.2 billion to €15.2 billion.
Keeping Up With Demand Is the Next Challenge
Fouquet said the company’s currently planned supply for 2027 and 2028 would not fully satisfy customer demand. ASML is therefore examining ways to expand capacity further. For shareholders, this points to a substantial opportunity. Customers appear to want more equipment than the company currently expects to provide.
But expanding production takes time. These are complex machines, and increasing output requires coordination across manufacturing operations and suppliers.
There is another potential growth driver: High NA EUV, ASML’s next generation of lithography equipment. These systems are designed to help chipmakers produce even finer features. TSMC and Samsung’s plans to adopt the technology strengthen its commercial prospects, although the timing and scale of purchases will matter.
China Remains an Important Uncertainty
The company’s outlook also comes with challenges in China, where the company still expects roughly 20% of its total business this year. Export restrictions prevent it from selling EUV systems and certain less advanced deep ultraviolet, or DUV, machines to Chinese customers.
Meanwhile, China is working to develop its own semiconductor equipment industry. Reports of progress on domestically produced immersion DUV machines have raised questions about future competition. However, developing a machine and manufacturing reliable systems at commercial scale are separate hurdles.
For ASML investors, the issue deserves attention without assuming its competitive position has already changed.
The broader investment story remains tied to execution. Customer interest stretching toward 2030 is promising, and stronger guidance adds support to management’s outlook.
Now ASML needs to translate that interest into orders, expand capacity, and deliver the machines customers need.
Those are the developments worth watching over the coming quarters. If demand holds up and production grows, ASML could remain a major beneficiary of the spending required to build AI infrastructure. Its latest report gives investors reasons for optimism, while leaving plenty for the company to prove.