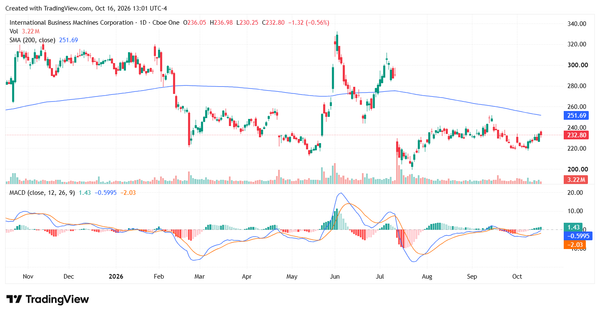
IBM (NYSE: IBM) is getting ready to report earnings. The upcoming report is about more than beating a profit estimate. It’s a chance for Big Blue to show investors that the problems behind its disappointing second quarter are easing and that its artificial intelligence ambitions can translate into more consistent growth.
The company will report third-quarter results on October 21, with its earnings webcast scheduled for 5 p.m. Eastern. Shareholders will want to know if IBM is getting back on track.
What Wall Street Expects
Analysts expect IBM to earn an adjusted $2.87 per share on revenue of $16.84 billion. That would represent earnings growth of about 8.3% and revenue growth of 3.1% from a year earlier. Those expectations suggest improvement, but hardly explosive growth.
Still, IBM does not necessarily need a spectacular quarter to make progress with investors. A solid report, evidence that delayed business is coming through, and a dependable outlook could help rebuild confidence. The quality of any earnings beat will matter, too. Higher profits supported by stronger customer demand would carry a different message than a beat driven mainly by lower expenses. Investors should look at revenue and earnings together before deciding how much has improved.
Did the Delayed Deals Finally Close?
One of the most important issues heading into this report is what happened to business IBM expected to complete earlier this year.
In July, CEO Arvind Krishna explained that customers had redirected some spending toward servers, storage, and memory to secure equipment ahead of anticipated price increases. The company also failed to close numerous large deals on schedule, contributing to its second-quarter shortfall. That creates a practical test for the upcoming results.
If those purchases were simply postponed, some of that business should eventually appear in revenue. If delays keep stretching out, investors may question whether the problem goes beyond timing.
There was an encouraging sign during July’s earnings call. Reuters reported that Krishna said approximately one-third of the delayed large capital-spending deals had already closed in the third quarter. Investors will now want to know how much additional progress followed.
A catch-up quarter would be welcome. But management also needs to explain whether new orders are arriving behind those delayed transactions. Collecting previously expected business helps today’s results; attracting additional demand supports tomorrow’s growth.
Software and Consulting Need to Show Progress
IBM’s software business will be another major focus.
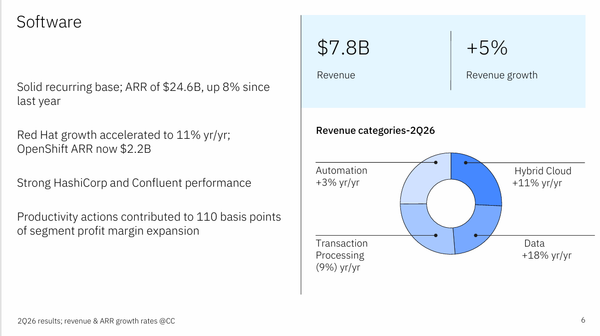
Second-quarter software revenue increased 5%, while Red Hat grew 11% and the data business expanded 19%. Those gains offered some encouragement during an otherwise difficult quarter. Consulting revenue, meanwhile, was essentially unchanged at $5.3 billion.
For investors, the next question is whether that software strength can become broader and more durable. Businesses experimenting with AI eventually have to make decisions about budgets, deployment, and ongoing support. IBM’s opportunity is to turn those decisions into paying relationships that last beyond an initial project.
That is why commentary about actual customer spending matters more than another round of enthusiasm about AI’s potential.
The Outlook Could Matter Most
Even if IBM beats quarterly estimates, management’s forecast could determine how investors interpret the report. In July, the company lowered its full-year revenue growth expectation to 4% to 5%. It maintained its expectation that annual free cash flow would increase by about $1 billion.
That cash outlook is worth watching closely.
Investors also want evidence that the business is producing cash. A maintained forecast would provide some reassurance. Strong results accompanied by greater confidence in demand would be more persuasive. Another reduction, however, would make it harder to argue that the earlier weakness was temporary.
For IBM shareholders, October 21 is an opportunity to get clearer answers.
Are delayed orders turning into sales? Is software growth strengthening? Can consulting contribute more? IBM does not need to solve every challenge in one quarter. But it does need to demonstrate progress that investors can measure. After July’s disappointment, a clear explanation backed by stronger execution could do more for confidence than another ambitious promise about the future.