ajax loader

Loading...


Ride-the-Wave Strategy – Best for Stock Traders

Ride-the-Wave targets multi-day price momentum following a company’s earnings announcement (EA). With this strategy:

  1. Buy a stock one day post-EA if a stock reacts positively post-earnings:
    1. Near the close of trading the EA-day for a pre-market-EA
    2. Near the close of the following day for a post-market-EA
  2. Sell-to-close after 7-10 days, or possibly earlier if a desired price target is reached

Similarly,

  1. short a stock one day post-EA if a stock reacts negatively post-earnings:
    1. near the close of trading the EA-day for a premarket-EA
    2. near the close of the following day for a post-market-EA
  2. then buy-to-close after 7-10 days, or possibly earlier if a desired price target is reached

Important: Ride-the-Wave is predicated on significant price momentum triggered by an EA. The 7-10 day scenario is the maximum trade hold-time. If you see post EA-momentum is halted or reversed by a significant opposite move, re-evaluate your presence in the trade.

This popular StockEarnings screen below will give you a list of stocks that historically exhibit significant price momentum following an EA for the next seven days:

  1. Stocks exhibiting positive post-EA price moves are buy-candidates
  2. Stocks exhibiting negative post-EA price moves are sell/short-candidates

The screen includes those stocks whose Earnings just came out in last two days.

Screen criteria:

  1. Earnings Date Start Date : Current Date + -1 Day
  2. Earnings Date End Date : Current Date + -2 Days
  3. Predicted Move (Next Day) Max : 7%
  4. Predicted Move (On 7th Day) Min : 7%

Strategy Guideline:

  1. Buy the stock if stock has reacted positively. Short the stock if stock has reacted negatively (see above).
  2. Close the position in 7-10 days, or possibly earlier based on price move.

Volatility Crush Strategy - Best for Options Traders

The Volatility Crush strategy is used with stocks that typically experience relatively low-to-moderate price moves (≤4%) following their Earnings Announcements (EA). The basic trade idea is to sell put or call options right before the EA, collecting a credit when options premium is very high due to elevated implied volatility (IV). You then close the position right after the EA by buying the option back much cheaper due to the significant drop in IV that occurs after the mystery of the EA disappears. In assessing this trade, you need to do your homework to ensure you collect sufficient premium to make the trade worthwhile.

This trade is practical due to the low-to-moderate price-move after the EA, which generally won’t significantly affect the options price, unlike an “action” stock, which experience great price moves post-EA. With these symbols, if you’re on the right side of the price move, that’s a great thing. But if you’re on the wrong side of the move, not so great. Consequently, by minimizing the effect of the post-EA price move, you have a much better chance to profit from the reduction in IV without it being ruined by a violent price move.

For this trade, open the position either (1) the night before the EA when the company announces earnings or (2) during the EA day when it announces post-market, generally capturing IV at or close to its peak.

For this trade, open the position either (1) the night before the EA when the company announces earnings or (2) during the EA day when it announces post-market, generally capturing IV at or close to its peak.

This popular stockearnings screen will give you a list of stocks which do not react more than 4% fpost-EA. It includes only those stocks whose earnings are releasing next day.

Screen criteria:

  1. Earnings Date Start Date : Current Date + 1
  2. Earnings Date End Date : Current Date + 1
  3. Predicted Move (Next Day) Max : 4%
  4. Options Type: Weekly

Strategy Guideline:

  1. Options Strategy: Sell Call and Put
  2. Options Strike Price: Current Stock Price – (% Predicated Move x 2)
  3. Expiration Date: It should generally be the closest expiry immediately after the EA.
  4. Buy Insurance: Buying back Call and Put at Strike price which 10% lower than Sell Strike Price is optional but recommended.

Watch Video for More Detail

Volatility Rush Strategy - Best for Options Traders

The Volatility Rush takes advantage of increasing options premiums into earnings announcements (EA) caused by an anticipated rise in Implied Volatility (IV). With this strategy, Buy a Call and Put at-the-money (a long straddle) 2-3 weeks before the EA when IV is lower. Sell the position either (1) the night before the EA when the company announces earnings pre-market, or (2) during the EA day when it announces post-market, generally capturing IV at or close to its peak.

This popular screen will give you a list of stocks whose Options premiums tend to rise into Earnings. It includes only those stocks whose Earnings are at least two weeks away from today.

Screen criteria:

  1. Earnings Date Start Date : Current Date + 15 Days
  2. Earnings Date End Date : Current Date + 30 Days
  3. Predicted Move (Next Day) Min : 5%
  4. Options Type: Weekly or Monthly if that lines up with the two to three-week lead-time for entering the trade

Strategy Guideline:

  1. Buy a Straddle at or close to the money two to three weeks pre-EA.
  2. Sell the position either the night before the EA when the company announces earnings pre-market, or during the EA day when it announces post-market.
  3. Expiration date should generally be the closest expiry immediately after the EA.
  4. Straddle price should not be more 60% of predicted move.

Predicted Move (Volatility)

Similar to Implied Volatility in Options. Expected volatility % based on our Proprietary Volatility Predication Model. We are expecting that stock price will likely to reach % in either direction by the end of next trading session after Earnings are released and not necessarily the closing volatility %.

Why is it important?

    This indicator helps

  1. Knowing expected volatility in stocks after Earnings helps to decide trading stocks before Earnings Announcement.
  2. Taking Advantage of volatility collapse following Earnings Results by using Advance Options strategies such as Spread and Straddles.

Since Last Earnings

Change in share price since last Earnings release.

Why is it Important?

When share has gained more than 10% since it's last Earning release, it tends to over react to minor bad news and give up some gains if not all. So, it contains more downside volatility than upside When share has dropped more than 10% since it's last Earning release, it tends to over react to minor good news and recover some drops if not all. So, it contains more upside volatility than downside.

EPS Surprise (%)

Occurs when a company's reported quarterly or annual profits are above or below analysts' expectations. Here is the formula to derive % EPS Surprice:

Actual EPS - Estimated EPS
------------------------------------- x 100
Estimated EPS

Why is it Important?

Earnings surprises can have a huge impact on a company's stock price. Several studies suggest that positive earnings surprises not only lead to an immediate hike in a stock's price, but also to a gradual increase over time. Hence, it's not surprising that some companies are known for routinely beating earning projections. A negative earnings surprise will usually result in a decline in share price.

Next Day Price Change (%)

Next Regular trading session Closing price following Earnings result.

For After Market Close Earnings, It is a next trading day closing price. For Before Market Open Earnings, It is the same trading day closing price.

Why is it Important?

Next Day price change is a reaction of Earnings result.

Costco Is Squeezing More Profit From A Slowing $94 Billion Sales Machine

Posted on Sep 25, 2026 by Grayson Cavern

Costco Is Squeezing More Profit From A Slowing $94 Billion Sales Machine

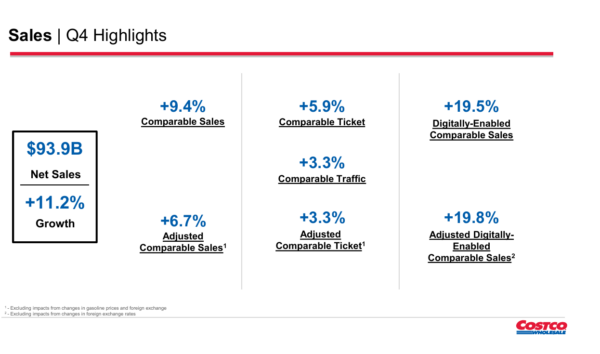
We had the answer to the question I was watching before Costco Wholesale Corporation (NASDAQ: COST announced its fourth quarter and fiscal year earnings, namely that it did make more money and cash out of the $93.9 billion of merchandise it sold in Q4, as operating income climbed 13.8% to $3.80 billion and annual operating cash flow hit $15.83 billion.

The trouble here for stockholders is that sales are still cooling underneath those numbers. That definitely makes for a better contrarian setup than the straightforward $6.75 EPS beat. Costco’s total revenue increased 11.1% to $95.72 billion and diluted EPS rose to $6.75 from $5.87, but Q4 comparable-sales growth came in at 6.7% excluding gasoline and foreign exchange, down from the pace Costco was running earlier in the quarter.

The company continues to grow rapidly and squeeze more profit out of every dollar of sales. Now it’s up to the stock to prove that Costco can keep doing that as the sales engine loses some speed.
costco - StockEarnings

Costco Passed the Profit Test


I was hoping this report would give me some confidence that Costco could get more revenue out of its vast customer base and the income statement did just that.

Q4 net sales increased 11.2% to $93.87 billion, while operating income climbed 13.8% to $3.80 billion. Net income rose 14.9% to $3.00 billion, pushing diluted EPS up roughly 15% to $6.75.

The cost structure explains the acceleration. Merchandise costs increased 11.3%, almost matching the sales increase, while selling, general and administrative expenses rose only 7.9%. Costco therefore kept more of the incremental revenue after paying for the merchandise and overhead required to generate it.

That is exactly what the stock needed to see after the pre-earnings setup: the company isn’t simply growing sales; it is translating that growth into faster operating and earnings growth.

But there is a wrinkle inside the $6.75. Costco said Q4 diluted EPS received a $0.15 benefit from IEEPA tariff refunds, partially offset by reinvestment of those refunds into increased member values.

The quarter still produced strong underlying operating growth, so I wouldn’t reduce the entire earnings result to the refund. But that $0.15 will not simply appear again every quarter, which makes the operating-income growth more useful than the headline EPS number when judging the durability of the result.

The Sales Rate Is Still Moving Lower

This is the thread that connects directly to our pre-earnings article. Before the report, Costco had already told us Q4 sales were strong. The question was whether the company could convert those sales into enough profit and cash to defend the stock’s premium. We now know it did.

What has not changed is the direction of the underlying sales rate. Q4 total comparable sales came in at 9.4%, while adjusted comps excluding gasoline and foreign exchange were 6.7%. Digitally enabled comparable sales remained a standout at 19.5%.

The monthly progression makes the cooling more obvious. Adjusted comps moved from 8.0% in May to 7.0% in June, 6.6% in July and 5.4% in August before the full quarter settled at 6.7%. Costco also said the later Labor Day shift reduced August sales by a little less than 75 basis points, so calendar effects explain part of the August weakness.

Still, the direction is visible even after allowing for that distortion. Costco is therefore doing something investors should pay close attention to: earnings are accelerating faster than the underlying sales rate.

That works beautifully while the company protects its margins. It becomes a different story if sales keep slowing and Costco eventually has less room to squeeze additional profit from each dollar.

Membership Is Growing, Just Not As Fast As Revenue

The membership business was supposed to provide the recurring cushion underneath the merchandise operation, and Q4 showed that cushion remains substantial.

Costco collected $1.85 billion in membership fees, up from $1.724 billion a year earlier. That works out to roughly 7.3% growth, below the 11.1% increase in total revenue.

I don’t see that as a problem by itself. Membership fees are still growing at a healthy pace, and the company finished the year with $20.21 billion in cash and cash equivalents, compared with $14.16 billion a year earlier. Annual operating cash flow also increased to $15.83 billion from $13.34 billion.

But it does change the composition of the story. Merchandise revenue is growing faster than membership fees, while the underlying merchandise comp is cooling. Costco still has a powerful recurring-revenue base underneath the retail operation, but investors shouldn’t expect membership fees alone to compensate indefinitely for slower merchandise growth.

The Stock Has More To Prove Now

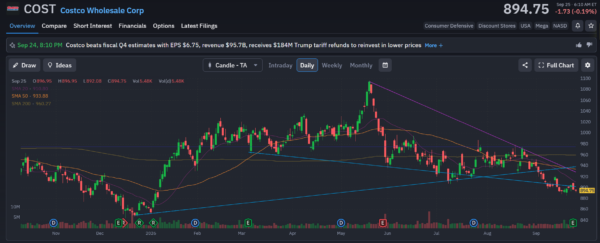
COST sits around $894.75, below its 20-day moving average near $910.80, its 50-day near $933.88 and its 200-day near $960.27. The shares remain well below the roughly $1,096 May peak.

That is a strange backdrop for a company that just reported $3.00 billion of quarterly net income and $15.83 billion of annual operating cash flow.

But the market is looking beyond the quarter now. Costco proved it can grow profit faster than sales. It proved the business can generate enormous cash. It also showed that the underlying sales rate continues to cool and that $0.15 of Q4 EPS came from a non-recurring tariff refund benefit.

That leaves me with a different scoreboard than the one I had before earnings: Can Costco keep expanding earnings faster than sales as the comp rate comes down?

The $93.9 billion sales haul cleared the first hurdle. Now Costco has to show that the profit engine can keep doing the heavy lifting after the sales engine loses more speed.
costco - StockEarnings

Join over 1.2M+ investors/traders who receive daily and weekly notable earnings alerts with predicted move
