Costco (NASDAQ: COST) gave investors plenty to like in its latest earnings report. Shoppers spent more at its warehouses, membership fees grew, and online sales climbed. Revenue also came in above Wall Street’s expectations.
But there is one important detail behind the company’s profit beat: A one-time tariff refund helped lift earnings. That means the sales numbers may be the better place to look when judging how Costco’s business performed.
Shoppers Are Still Showing Up
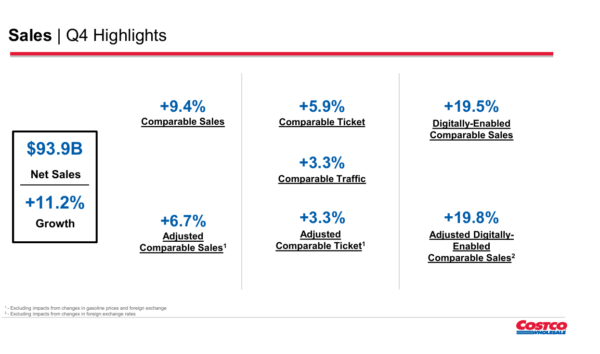
Costco reported $95.72 billion in revenue for its fiscal fourth quarter, up 12% from a year earlier. That was about $830 million more than analysts expected.
Some of that growth came from new warehouses. But Costco also sold more at locations that were already open. In the U.S., adjusted comparable sales rose 7.2%, beating the 6.85% growth analysts expected. Comparable sales also increased in Canada and other international markets.
For the company as a whole, comparable sales rose 6.7% when fuel was excluded, ahead of Wall Street’s 6.44% estimate.
Leaving fuel out helps give a clearer picture of shopping demand because gasoline prices can change the sales total even when customers buy about the same amount of merchandise.
Costco’s online business grew, too. Digital comparable sales increased at a double-digit pace during the 16-week quarter. The warehouses remain the heart of the business, but members are also spending more through Costco’s digital channel.
Membership Fees Added to Growth
Customers pay to shop at Costco, and those fees are an important part of its business. In the latest quarter, membership fee revenue rose 7% to $1.85 billion. Analysts had expected $1.83 billion. That increase is another encouraging sign for Costco.
The company depends on members seeing enough value in its prices and products to keep paying for access. The figures provided do not show exactly how much of the fee growth came from new members, renewals, or upgrades, but membership revenue was higher than Wall Street expected.
Why the Profit Beat Needs a Closer Look
Costco earned $6.57 per share for the quarter, up 15% from a year earlier and five cents above analysts’ estimates. However, that figure included a one-time benefit of 15 cents per share from tariff refunds. Without it, earnings would have been about $6.42 per share.
That does not take away from Costco’s strong sales. It simply means the reported profit beat tells only part of the story. Investors will want to see whether the company can keep growing earnings through its regular business in the quarters ahead.
Costco Keeps Expanding
Costco ended the period with 939 warehouses, eight more than it had at the end of its fiscal third quarter. Most are in the United States and Puerto Rico, where the company has 647 locations. It also has a large presence in Canada, along with warehouses across Mexico, Asia, Europe, Australia, and New Zealand.
For the full fiscal year, the company reported revenue of $303.15 billion, up 10.1%, and earnings of $20.76 per share. Both topped the estimates in the material you provided.
COST Remains Below Its 200-Day SMA
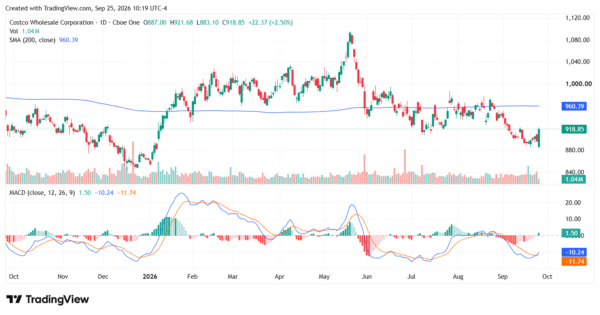
COST stock closed at $918.85 on Sept. 25, according to the chart provided. The stock remains below its 200-day simple moving average of $960.39, keeping the longer-term technical trend under pressure.
The chart does show a potential improvement in short-term momentum. The stock’s MACD histogram has turned positive at 1.50, while the MACD line at -10.24 has moved above its signal line at -11.74. That suggests downside momentum has eased following the stock’s decline through August and September.
However, the MACD lines remain below the zero line, and COST is still roughly 4.3% below its 200-day SMA. That leaves investors with two important technical levels to watch. Around $960 represents a potential test of the 200-day average, while the recent September low near $890 provides a reference point on the downside.
A move back above the 200-day SMA could change the technical picture, while a break below the recent low would indicate that the September decline remains intact. For now, the chart shows improving short-term momentum but a longer-term trend that has yet to recover.
The Takeaway for Costco Investors
Costco gave investors plenty of evidence that its business is still growing. Shoppers spent more at existing warehouses, digital sales rose at a double-digit pace, and membership fees came in ahead of expectations. The company also continued to open new locations, giving it another way to grow sales over time.
Still, the five-cent earnings beat looks different when we account for the one-time tariff refund. Without that 15-cent-per-share benefit, Costco would have earned about $6.42 per share, below Wall Street’s estimate. That does not erase the strong sales quarter, but it does put the profit headline in perspective.
The question now is whether Costco can turn that steady customer demand into stronger earnings from its regular operations. If comparable sales and membership fees keep growing, investors will have good reason to stay interested. They will also want to see profit growth that does not depend on another one-time boost.

