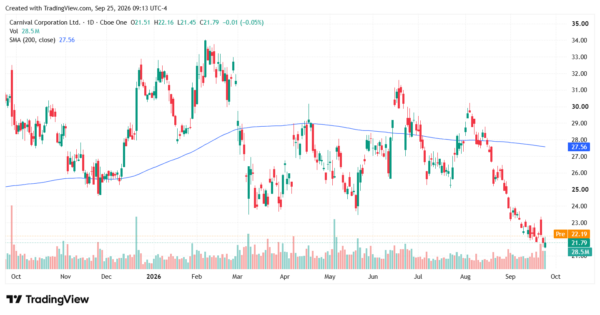
Carnival (NYSE: CCL) is heading into its fiscal third-quarter earnings report with a question hanging over the stock: Are strong cruise bookings enough to overcome higher fuel costs?
The company is scheduled to report on Tuesday, September 29. And analysts expect about $8.4 billion in revenue and $1.36 per share in earnings. Those figures would put revenue above the $8.15 billion Carnival reported a year ago, while earnings would be slightly below last year.
And while Carnival may be bringing in more money from its guests, rising costs could keep some of that growth from reaching the bottom line.
Bookings Are the First Thing to Watch
Cruise demand has been a bright spot for Carnival. When the company reported second-quarter results in June, it said it had already booked 93% of its remaining 2026 sailings. Management also pointed to strong interest in cruises farther into the future.
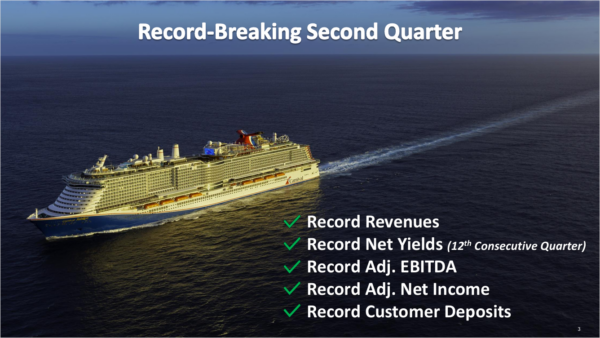
Next week, Wall Street will want an update. Are cabins still filling at attractive prices? Are guests booking well ahead of departure? And is demand for 2027 holding up?
Investors will also listen closely to what executives say about European cruises. In June, Carnival said geopolitical uncertainty had disrupted bookings in Europe, particularly in the Mediterranean. A clearer picture of whether those trends have improved could shape the market’s reaction to the report.
Can Carnival Keep Getting More from Each Cruise?
Wall Street will also focus on net yields, a measure that helps show how much revenue Carnival earns from its available passenger capacity. In plain English, it offers a useful way to see whether the company is making more from the cruises it operates.
Ticket prices are part of that picture. So is what guests spend once they are on board, including purchases such as drinks, specialty dining and excursions.
Carnival has continued to report strong yields, even as some booking markets have faced pressure. Following its second-quarter report, the company projected full-year net yield growth of about 1.75%. Investors will want to know whether summer demand and onboard spending have given management reason to lift that outlook.
There is some optimism heading into the release.
William Blair analysts recently said the company could modestly beat third-quarter earnings expectations if stronger yields more than offset higher fuel costs. That is an analyst view, though, and the company’s results will show whether it played out.
Fuel Costs Could Spoil a Strong Quarter
Fuel is the biggest complication. Ships need a great deal of it, and Carnival does not typically hedge fuel costs the way some other major cruise operators do. That leaves its earnings more exposed when fuel prices rise.
That pressure showed up in the cruise line’s second quarter. Higher fuel expenses squeezed margins, even though the company delivered better-than-expected adjusted earnings. Management’s initial third-quarter forecast called for about $1.35 per share in adjusted earnings, below the analyst estimate at the time.
So, a smaller earnings beat next week may not settle the issue for investors. They will want to hear how much fuel cost Carnival during the quarter and, just as importantly, what management expects to pay in the months ahead.
The Outlook May Matter More Than the Beat
Carnival’s third quarter includes the busy summer travel season, making it an important test of both demand and profitability. Still, the stock’s response may depend more on what executives say about the future than on whether earnings come in a few cents above or below expectations.
Investors will be looking for an updated full-year forecast, details on 2027 bookings and signs that demand remains strong at higher prices. They will also want to know whether fuel costs or weaker demand on certain routes could limit earnings growth.
Carnival could deliver solid revenue and still leave Wall Street uneasy if its outlook weakens. On the other hand, strong yields and reassuring booking trends could give investors more confidence that the company can manage its cost pressures.