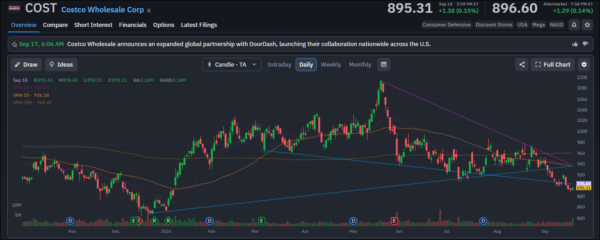
Costco Wholesale Corp. (NASDAQ: COST) has already done the part of this earnings setup that usually gets investors excited by showing that the customer is still spending. But the stock has been doing the opposite. COST closed at $895.31 on Sept. 18, well below the roughly $1,096 May peak, while fiscal Q4 sales came in at $93.9 billion, up 11.3%.
So the setup is pretty simple: the business is still growing hard, but the underlying sales rate has cooled, and now the market has to decide how much premium it wants to keep paying for that growth.
The Sales Tape Is Strong; Look Closer
May was the monster month, with comparable sales up 12.5% and 8.0% after stripping out gasoline and foreign exchange. June slowed to 8.8%, or 7.0% ex-gas and FX; July came in at 8.9%, or 6.6%; and August finished at 8.4%, or 5.4%. The full fiscal Q4 landed at 9.4%, with the cleaner ex-gas/FX number at 6.7%. Digital was still flying, with digitally enabled Q4 comps up 19.5%.
That progression is the number I would keep on the screen going into the print. Headline comps remain high, but the underlying rate moved from 8.0% in May to 5.4% in August. Some August softness was calendar noise because Costco said the later Labor Day reduced August sales by a little less than 75 basis points. Still, the sequence shows a business coming off its spring pace.
And this is where traders can get caught leaning the wrong way. Costco has already told the market that people are spending. Buying the stock because the sales number looks strong after that number is already public is chasing a known fact. The fresh information is what those sales produced for earnings.
The Membership Engine Is The Cushion
Looking at the recurring revenue underneath the merchandise business, earlier fiscal 2026 numbers showed $1.373 billion of quarterly membership fees, up 10.7%, with 82.9 million paid memberships. Renewal rates were 92.2% in the U.S. and Canada and 89.7% worldwide, while Executive memberships reached 41.2 million. Operating cash flow hit $11.133 billion through the first 36 weeks, versus $9.468 billion a year earlier.
I would read that less as another “membership is great” bullet point and more as the cushion underneath the retail machine. If merchandise comps cool, recurring membership revenue and cash generation give Costco another lever to keep the earnings engine moving. But investors already know this part of the story. The earlier valuation work put COST around 48 times trailing earnings and 42 times forward earnings, meaning a lot of durability was already priced in.
So Thursday is less about proving Costco is a great business. The trade is about whether the earnings can keep the premium from getting squeezed as the sales rate cools.
Don’t Let The Earnings Setup Fool You
There are a few classic mistakes sitting all over this setup.
First, anchoring to the 9.4% Q4 comp and ignoring the 6.7% ex-gas/FX figure. Both are useful, but they answer different questions. Gasoline and currency can move the headline; the cleaner figure gives you a better read on the underlying retail machine.
Second, treating the consensus EPS number as the finish line. If COST clears the estimate but margins or the forward tone disappoint, the stock can still get hit because traders are repricing what comes after the quarter. A beat is not a trade thesis by itself.
Third, buying the chart before the chart confirms anything. COST is below its 20-day average of around $924.60, its 50-day average of around $936.54 and its 200-day around $960.42 on the chart provided. That puts roughly $925-$940 in the first recovery zone, with $960 as the bigger test. Buying calls simply because the sales numbers look good is a different trade from waiting to see whether buyers actually show up.
And I’d not build the thesis around a special $15 dividend rumor either. A payout can move sentiment, but it does not fix a cooling sales rate or give the business a cheaper valuation.
What I Want From COST Thursday
My scoreboard going into Thursday is simple: Costco has to show that the $93.9 billion Q4 sales haul converted into enough profit and cash to keep the premium attached to the stock. The sales engine is still running. The issues are the direction of the underlying comp, the ability to protect profitability as the business scales, and whether membership economics continue to provide that cushion. So I would rather see the stock tell me what the market thinks than guess beforehand. A clean reclaim of the moving averages would change the chart. A failure there would keep the May peak firmly in the rearview mirror.

