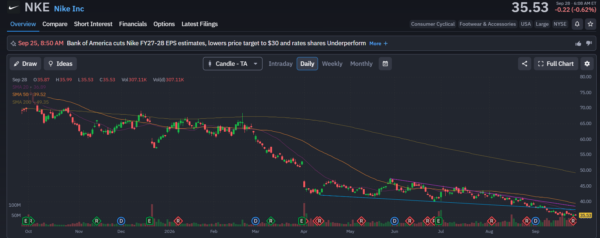
Nike (NYSE: NKE) goes into its Q1 earnings for fiscal year 2027 (FY2027) at $35.53, sitting just above its 52-week low of roughly $35.35. The chart is ugly, estimates are being cut again, and Bank of America Securities recently downgraded Nike to Underperform while cutting its price target from $47 to $30 and reducing its fiscal 2027 and 2028 EPS estimates by 11% and 12%, respectively.
Wall Street is looking for roughly $11.34 billion in first-quarter revenue versus $11.72 billion a year ago, with EPS around $0.44 versus $0.49. Another weak quarter would hardly shock anyone. The unusual part would be seeing Nike’s economics improve while revenue deteriorates.
Nike Is Cutting Sales To Clean Up The Business
Nike finished fiscal 2026 with $46.4 billion in revenue, essentially flat reported and down 2% on a currency-neutral basis. NIKE Direct fell 9% currency-neutral, NIKE Brand Digital dropped 12%, Converse plunged 34%, and Greater China declined 17%.
North America gives the turnaround something to work with. Q4 revenue there increased 3%, footwear rose 4%, and wholesale grew 4% reported and 1% currency-neutral. North America EBIT jumped 91% to $2 billion.
Could the company be deliberately leaning into that split? Maybe. Management said it was tightening buys, reducing future sell-in, and managing inventory as it works through weaker demand, accepting lower near-term revenue in exchange for a healthier product mix and better margins. For Q1, management expects revenue to decline low-to-mid single digits, while gross-margin expansion should turn slightly positive and SG&A dollars remain roughly flat.
That is a strange setup for a stock sitting near its lows because the income statement can start looking better before demand does.
The 49.2% Margin Number Comes With An Asterisk
Nike’s Q4 gross margin was 49.2%, an enormous improvement on paper, but roughly 900 basis points of that increase came from the expected recovery of IEEPA tariffs. Q4 EPS reached $0.72, including a $0.52 tariff benefit. Strip that benefit out and the margin was roughly 40.2%, almost identical to the 40.3% recorded a year earlier.
I want to see that number move on Thursday. Nike has already shown it can print a spectacular headline margin when a $986 million tariff recovery runs through the quarter. Now the business has to expand the underlying margin without another one-off doing the work.
Management has actually pulled the timing forward, saying gross-margin expansion should begin in Q1 rather than Q2, while operating overhead dollars are expected to decline. That gives Nike a clean test because the revenue line is already expected to remain under pressure.
If margin improves while revenue falls, the cleanup is starting to show up where shareholders can actually measure it.
China Is Still The Hole In The Turnaround
Greater China fell 17% currency-neutral in Q4, with footwear down 17%, apparel down 15% and equipment down 21%. North America is doing enough to keep the story alive, but China is large enough to keep dragging on it.
That split is what makes Thursday worth trading around. Nike does not need every part of the business to turn at once. The pieces already improving have to become substantial enough to offset the ones still breaking apart.
With China still bleeding at a double-digit rate while Direct, Sportswear and Jordan remain under pressure, margin repair can start looking like financial housekeeping rather than a demand recovery. Nike needs North America and wholesale to keep getting better while the weaker businesses stop deteriorating.
The stock has already paid a heavy price for waiting.
$35.53 Is Where The Market Wants Proof
The chart leaves very little room for storytelling. Nike is below its $36.89 20-day SMA, $39.52 50-day SMA, and $49.35 200-day SMA, while pressing against the roughly $35.35 52-week low. The 20-day sits below the 50-day, the 50-day sits well below the 200-day, and the broader trend remains down.
The first reclaim I would watch is $36.89. Then comes $39.52. Getting back through both after earnings would at least show buyers are willing to fight for the fundamental improvement rather than sell every bounce.
The other side is cleaner. If revenue misses, underlying gross margin fails to improve, or management pushes the recovery timeline out again, $35.35 becomes the line I care about.
Thursday is therefore bigger than whether Nike can squeeze out a few extra cents of EPS. The stock needs evidence that the cleanup is improving the economics of the business while sales are still shrinking.
I would rather see that evidence before throwing a cent in the ring for a turnaround. And never forget, a $35 stock is not automatically cheap because it used to trade at $70; Nike still has to earn that valuation through better margins first and better demand eventually.