ajax loader

Loading...


Ride-the-Wave Strategy – Best for Stock Traders

Ride-the-Wave targets multi-day price momentum following a company’s earnings announcement (EA). With this strategy:

  1. Buy a stock one day post-EA if a stock reacts positively post-earnings:
    1. Near the close of trading the EA-day for a pre-market-EA
    2. Near the close of the following day for a post-market-EA
  2. Sell-to-close after 7-10 days, or possibly earlier if a desired price target is reached

Similarly,

  1. short a stock one day post-EA if a stock reacts negatively post-earnings:
    1. near the close of trading the EA-day for a premarket-EA
    2. near the close of the following day for a post-market-EA
  2. then buy-to-close after 7-10 days, or possibly earlier if a desired price target is reached

Important: Ride-the-Wave is predicated on significant price momentum triggered by an EA. The 7-10 day scenario is the maximum trade hold-time. If you see post EA-momentum is halted or reversed by a significant opposite move, re-evaluate your presence in the trade.

This popular StockEarnings screen below will give you a list of stocks that historically exhibit significant price momentum following an EA for the next seven days:

  1. Stocks exhibiting positive post-EA price moves are buy-candidates
  2. Stocks exhibiting negative post-EA price moves are sell/short-candidates

The screen includes those stocks whose Earnings just came out in last two days.

Screen criteria:

  1. Earnings Date Start Date : Current Date + -1 Day
  2. Earnings Date End Date : Current Date + -2 Days
  3. Predicted Move (Next Day) Max : 7%
  4. Predicted Move (On 7th Day) Min : 7%

Strategy Guideline:

  1. Buy the stock if stock has reacted positively. Short the stock if stock has reacted negatively (see above).
  2. Close the position in 7-10 days, or possibly earlier based on price move.

Volatility Crush Strategy - Best for Options Traders

The Volatility Crush strategy is used with stocks that typically experience relatively low-to-moderate price moves (≤4%) following their Earnings Announcements (EA). The basic trade idea is to sell put or call options right before the EA, collecting a credit when options premium is very high due to elevated implied volatility (IV). You then close the position right after the EA by buying the option back much cheaper due to the significant drop in IV that occurs after the mystery of the EA disappears. In assessing this trade, you need to do your homework to ensure you collect sufficient premium to make the trade worthwhile.

This trade is practical due to the low-to-moderate price-move after the EA, which generally won’t significantly affect the options price, unlike an “action” stock, which experience great price moves post-EA. With these symbols, if you’re on the right side of the price move, that’s a great thing. But if you’re on the wrong side of the move, not so great. Consequently, by minimizing the effect of the post-EA price move, you have a much better chance to profit from the reduction in IV without it being ruined by a violent price move.

For this trade, open the position either (1) the night before the EA when the company announces earnings or (2) during the EA day when it announces post-market, generally capturing IV at or close to its peak.

For this trade, open the position either (1) the night before the EA when the company announces earnings or (2) during the EA day when it announces post-market, generally capturing IV at or close to its peak.

This popular stockearnings screen will give you a list of stocks which do not react more than 4% fpost-EA. It includes only those stocks whose earnings are releasing next day.

Screen criteria:

  1. Earnings Date Start Date : Current Date + 1
  2. Earnings Date End Date : Current Date + 1
  3. Predicted Move (Next Day) Max : 4%
  4. Options Type: Weekly

Strategy Guideline:

  1. Options Strategy: Sell Call and Put
  2. Options Strike Price: Current Stock Price – (% Predicated Move x 2)
  3. Expiration Date: It should generally be the closest expiry immediately after the EA.
  4. Buy Insurance: Buying back Call and Put at Strike price which 10% lower than Sell Strike Price is optional but recommended.

Watch Video for More Detail

Volatility Rush Strategy - Best for Options Traders

The Volatility Rush takes advantage of increasing options premiums into earnings announcements (EA) caused by an anticipated rise in Implied Volatility (IV). With this strategy, Buy a Call and Put at-the-money (a long straddle) 2-3 weeks before the EA when IV is lower. Sell the position either (1) the night before the EA when the company announces earnings pre-market, or (2) during the EA day when it announces post-market, generally capturing IV at or close to its peak.

This popular screen will give you a list of stocks whose Options premiums tend to rise into Earnings. It includes only those stocks whose Earnings are at least two weeks away from today.

Screen criteria:

  1. Earnings Date Start Date : Current Date + 15 Days
  2. Earnings Date End Date : Current Date + 30 Days
  3. Predicted Move (Next Day) Min : 5%
  4. Options Type: Weekly or Monthly if that lines up with the two to three-week lead-time for entering the trade

Strategy Guideline:

  1. Buy a Straddle at or close to the money two to three weeks pre-EA.
  2. Sell the position either the night before the EA when the company announces earnings pre-market, or during the EA day when it announces post-market.
  3. Expiration date should generally be the closest expiry immediately after the EA.
  4. Straddle price should not be more 60% of predicted move.

Predicted Move (Volatility)

Similar to Implied Volatility in Options. Expected volatility % based on our Proprietary Volatility Predication Model. We are expecting that stock price will likely to reach % in either direction by the end of next trading session after Earnings are released and not necessarily the closing volatility %.

Why is it important?

    This indicator helps

  1. Knowing expected volatility in stocks after Earnings helps to decide trading stocks before Earnings Announcement.
  2. Taking Advantage of volatility collapse following Earnings Results by using Advance Options strategies such as Spread and Straddles.

Since Last Earnings

Change in share price since last Earnings release.

Why is it Important?

When share has gained more than 10% since it's last Earning release, it tends to over react to minor bad news and give up some gains if not all. So, it contains more downside volatility than upside When share has dropped more than 10% since it's last Earning release, it tends to over react to minor good news and recover some drops if not all. So, it contains more upside volatility than downside.

EPS Surprise (%)

Occurs when a company's reported quarterly or annual profits are above or below analysts' expectations. Here is the formula to derive % EPS Surprice:

Actual EPS - Estimated EPS
------------------------------------- x 100
Estimated EPS

Why is it Important?

Earnings surprises can have a huge impact on a company's stock price. Several studies suggest that positive earnings surprises not only lead to an immediate hike in a stock's price, but also to a gradual increase over time. Hence, it's not surprising that some companies are known for routinely beating earning projections. A negative earnings surprise will usually result in a decline in share price.

Next Day Price Change (%)

Next Regular trading session Closing price following Earnings result.

For After Market Close Earnings, It is a next trading day closing price. For Before Market Open Earnings, It is the same trading day closing price.

Why is it Important?

Next Day price change is a reaction of Earnings result.

Jefferies’ Record Quarter Reveals 5 Risks Beneath the Surface

Posted on Sep 29, 2026 by Grayson Cavern

Jefferies’ Record Quarter Reveals 5 Risks Beneath the Surface

There is a funny thing about record quarters. Sometimes the earnings report tells you exactly what happened. Other times, it tells you which part of the report everyone is looking at.

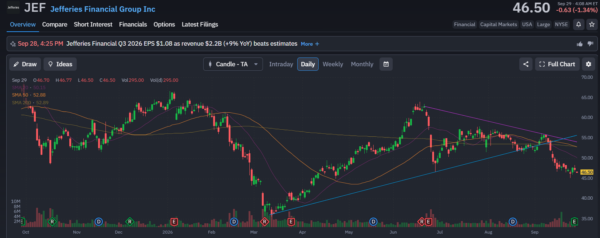
Jefferies Financial Group (NYSE:JEF)  just produced its best-ever investment-banking quarter, pushed quarterly net revenue to $2.22 billion and generated $1.08 in diluted EPS. Equities revenue hit a record $626 million, while investment banking reached $1.33 billion, and the stock sits around $46.50.

But that doesn’t make the quarter bad. Investment banking really is booming, equities had a monster quarter, and Jefferies is benefiting from a capital-markets environment that has opened up considerably. But walking the numbers from revenue to profit, from profit to returns, and finally to what management did with shareholder capital leaves five contradictions underneath the “record” label.

1. Record Revenue, Almost No Improvement In Returns


Jefferies increased quarterly net revenue from $2.05 billion to $2.22 billion, an 8.5% increase, while net earnings attributable to common shareholders climbed 16% to $261 million. Adjusted diluted EPS rose from $1.01 to $1.08. Yet return on adjusted tangible shareholders’ equity was 13.5%, versus 13.6% a year ago. That’s almost no movement after the business just produced its strongest investment-banking quarter ever.

Adjusted tangible book value per fully diluted share also increased from $33.38 to $35.21, meaning Jefferies is generating more revenue while supporting the business with a larger tangible-equity base.

For a financial company, revenue growth eventually has to show up in the returns earned on the capital behind it. Jefferies hasn’t produced that improvement yet.

2. The Revenue Boom Is Getting More Expensive

The people producing that record investment-banking revenue are taking a larger piece of it. Compensation and benefits increased to $1.19 billion, roughly 10% above last year, against 8.5% revenue growth. Compensation therefore consumed 53.7% of net revenue, up from 52.9%. That is the economics of a human-capital-heavy investment bank showing itself. When advisory and underwriting explode, the bankers generating those fees become more valuable too, and some of that incremental revenue follows them into compensation.

So the problem isn’t that 53.7% is catastrophic. It is that the ratio moved higher during a quarter that was supposed to demonstrate operating leverage. Revenue grew 8.5%. Compensation grew faster. And that leads directly into the next contradiction, because the additional revenue isn’t translating into pretax profit at the same pace.

3. EPS Looks Better Than The Operating Business

Pretax income increased just 5.8%, from $331.8 million to $351.0 million. Net earnings attributable to common shareholders, however, jumped roughly 16%, from $224.0 million to $260.6 million. The tax provision fell to $87.0 million from $89.3 million, allowing more of the pretax income to reach the bottom line. So the EPS number is improving considerably faster than the underlying operating profit.

That doesn’t make the $1.08 figure meaningless either. But I’d rather see the pretax earnings start catching up before treating the EPS growth as evidence of a much more powerful earnings engine.

4. The “Record” Quarter Has A Very Specific Shape

Investment banking produced $1.33 billion of revenue, with advisory at $817.8 million, equity underwriting at $305.5 million and debt underwriting at $177.1 million. Equities contributed another $626.2 million, up roughly 29% year over year. Then fixed income went the other way, falling to $176 million from $237 million.

Asset-management net revenue fell even harder, from $176.8 million to $85.6 million, with Jefferies citing lower management and performance fees and weaker performance across several strategies. This is what the record quarter actually looks like when you stop looking at the aggregate number: dealmaking and equities are firing, while fixed income and asset management are pulling in the opposite direction.

That isn’t unusual for an investment bank. M&A and underwriting can create enormous fee pools when markets open, while other businesses lag. The problem for Jefferies is proving that the strength in its best businesses can become durable enough to carry the weaker ones when the capital-markets cycle eventually cools.

5. Jefferies Bought Its Own Stock Much Higher

The shareholder-return table adds another wrinkle. Jefferies repurchased 1.3 million shares for $70 million during Q3 at an average of $52.54 per share. Over nine months, it bought back 8.3 million shares for $441 million at an average of $53.25. JEF is now around $46.50. So the company spent hundreds of millions buying its own shares around $53 while the market has since marked those purchases down by roughly 13%.

I wouldn’t call that automatically wrong. The buyback reduced the share count, and management was making those decisions with the information available at the time. But the price action makes the decision worth examining alongside the stagnant ROATE and rising compensation ratio.

The chart has also broken its rising trendline, with JEF below the $50.15 20-day SMA and the $52.88 50-day and 200-day averages. Those are the levels I’d want to see the stock reclaim before treating the stock’s decline as disconnected from the earnings story.

For now, I’m sitting on the sidelines of the “record” headline. Jefferies has earned the right to call investment banking revenue a record. But it hasn’t yet shown the same improvement in return.
jefferies - StockEarnings

Join over 1.2M+ investors/traders who receive daily and weekly notable earnings alerts with predicted move