Netflix (NASDAQ: NFLX) hasn’t given investors much to cheer about lately. Shares have fallen more than 14% in September and more than 26% this year, as concerns about viewer engagement have raised questions about the streaming giant’s growth.
But Deutsche Bank believes the selloff has created an opportunity. Analyst Bryan Kraft upgraded NFLX to Buy from Hold, even as he lowered his price target to $95 from $100.
At first glance, Kraft’s decision might seem confusing. If he thinks the stock is worth less than he previously estimated, why recommend buying it now?
The answer comes down to price.
A company can have a slightly weaker outlook and still become a more attractive investment if its shares fall far enough. Think of it this way: Something you considered too expensive a few months ago might look appealing after a substantial discount.
That appears to be the thinking behind Deutsche Bank’s upgrade. Kraft’s lower target reflects a more cautious valuation, but the stock’s decline leaves considerable room between its recent trading price and his estimate of its value.
Why Investors Are Worried
The biggest concern is engagement, or how much time people spend watching Netflix.
That matters because subscribers need a reason to keep paying. If viewers struggle to find something they want to watch, they may become more willing to cancel or switch to another service. Less viewing could also limit advertising opportunities. Advertisers generally want access to audiences that show up regularly and spend time on a platform.
Earlier this month, Wells Fargo downgraded Netflix to Underweight, pointing to troubling engagement trends. That offers a reminder that Wall Street is divided about what comes next.
Investors are trying to determine whether softer viewing reflects a temporary shortage of compelling releases or a more persistent problem. Those are very different situations, and the answer could shape the stock’s next move.
Netflix’s International Business Deserves Attention
Kraft believes investors are overlooking an important advantage: Netflix’s international production network. According to his analysis, more than 60% of the company’s production now takes place outside the United States. That gives Netflix access to a broad range of stories, creative talent, and audiences.
The investment argument is easy to understand. Netflix doesn’t have to depend entirely on Hollywood to keep its service appealing. Producing entertainment across different countries can help the company connect with local viewers. It also creates opportunities for a show developed in one market to attract fans elsewhere.
That doesn’t mean every international production will become a hit. Entertainment remains unpredictable, and spending heavily on content doesn’t guarantee success.
A Bigger Role in Entertainment
Kraft also sees Netflix becoming a broader entertainment platform.
In plain English, his argument is that Netflix’s value extends beyond the movies and television shows it produces. Its brand, subscriber base, and operating experience could help it expand the ways it connects audiences with entertainment.
Netflix still needs appealing content, whatever approach it takes. But Kraft’s view suggests its established audience and global reach could provide additional ways to grow over time.
The opportunity depends on execution. Expanding the service only creates shareholder value if it attracts customers, keeps them engaged, and produces worthwhile financial returns.
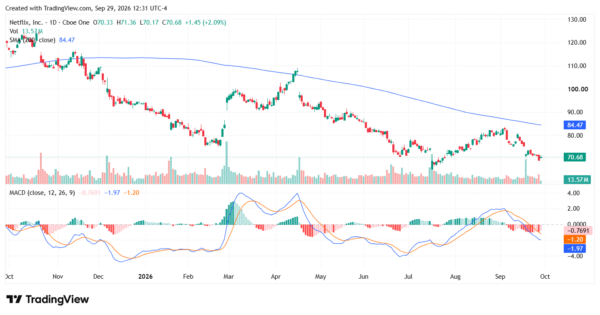
NFLX Stock Chart Signals More Downside Risk
NFLX stock remains under technical pressure despite its 2% gain on Sept. 29. Shares closed at $70.68, well below the declining 200-day moving average at $84.47, indicating that the longer-term trend remains weak. The stock’s recent rebound toward the low-$80s was rejected, sending shares back toward the $70 area.
Momentum is also deteriorating. The MACD has moved below its signal line, while the histogram has turned increasingly negative, suggesting bearish momentum is building. The $70 area is an important near-term level to watch; a sustained break below it could put the recent lows around the upper-$60s back in focus.
On the upside, NFLX would first need to reclaim the $80-$84 area, including its 200-day moving average, to signal a meaningful improvement in its technical picture. Until then, the chart suggests investors are still dealing with a broader downtrend.
What Investors Should Watch Next
The upgrade gives investors a reason to reconsider Netflix, but its next results will matter more than one analyst’s recommendation.
Watch whether engagement improves, revenue continues growing, and management keeps content spending under control. Profitability and cash generation will help show whether Netflix is turning its global reach into a stronger business.
The bullish case is that recent disappointment has overshadowed advantages built over many years. If Netflix can improve viewing trends while maintaining financial discipline, the stock could regain support. For patient investors, the selloff may offer an opening.