ajax loader

Loading...


Ride-the-Wave Strategy – Best for Stock Traders

Ride-the-Wave targets multi-day price momentum following a company’s earnings announcement (EA). With this strategy:

  1. Buy a stock one day post-EA if a stock reacts positively post-earnings:
    1. Near the close of trading the EA-day for a pre-market-EA
    2. Near the close of the following day for a post-market-EA
  2. Sell-to-close after 7-10 days, or possibly earlier if a desired price target is reached

Similarly,

  1. short a stock one day post-EA if a stock reacts negatively post-earnings:
    1. near the close of trading the EA-day for a premarket-EA
    2. near the close of the following day for a post-market-EA
  2. then buy-to-close after 7-10 days, or possibly earlier if a desired price target is reached

Important: Ride-the-Wave is predicated on significant price momentum triggered by an EA. The 7-10 day scenario is the maximum trade hold-time. If you see post EA-momentum is halted or reversed by a significant opposite move, re-evaluate your presence in the trade.

This popular StockEarnings screen below will give you a list of stocks that historically exhibit significant price momentum following an EA for the next seven days:

  1. Stocks exhibiting positive post-EA price moves are buy-candidates
  2. Stocks exhibiting negative post-EA price moves are sell/short-candidates

The screen includes those stocks whose Earnings just came out in last two days.

Screen criteria:

  1. Earnings Date Start Date : Current Date + -1 Day
  2. Earnings Date End Date : Current Date + -2 Days
  3. Predicted Move (Next Day) Max : 7%
  4. Predicted Move (On 7th Day) Min : 7%

Strategy Guideline:

  1. Buy the stock if stock has reacted positively. Short the stock if stock has reacted negatively (see above).
  2. Close the position in 7-10 days, or possibly earlier based on price move.

Volatility Crush Strategy - Best for Options Traders

The Volatility Crush strategy is used with stocks that typically experience relatively low-to-moderate price moves (≤4%) following their Earnings Announcements (EA). The basic trade idea is to sell put or call options right before the EA, collecting a credit when options premium is very high due to elevated implied volatility (IV). You then close the position right after the EA by buying the option back much cheaper due to the significant drop in IV that occurs after the mystery of the EA disappears. In assessing this trade, you need to do your homework to ensure you collect sufficient premium to make the trade worthwhile.

This trade is practical due to the low-to-moderate price-move after the EA, which generally won’t significantly affect the options price, unlike an “action” stock, which experience great price moves post-EA. With these symbols, if you’re on the right side of the price move, that’s a great thing. But if you’re on the wrong side of the move, not so great. Consequently, by minimizing the effect of the post-EA price move, you have a much better chance to profit from the reduction in IV without it being ruined by a violent price move.

For this trade, open the position either (1) the night before the EA when the company announces earnings or (2) during the EA day when it announces post-market, generally capturing IV at or close to its peak.

For this trade, open the position either (1) the night before the EA when the company announces earnings or (2) during the EA day when it announces post-market, generally capturing IV at or close to its peak.

This popular stockearnings screen will give you a list of stocks which do not react more than 4% fpost-EA. It includes only those stocks whose earnings are releasing next day.

Screen criteria:

  1. Earnings Date Start Date : Current Date + 1
  2. Earnings Date End Date : Current Date + 1
  3. Predicted Move (Next Day) Max : 4%
  4. Options Type: Weekly

Strategy Guideline:

  1. Options Strategy: Sell Call and Put
  2. Options Strike Price: Current Stock Price – (% Predicated Move x 2)
  3. Expiration Date: It should generally be the closest expiry immediately after the EA.
  4. Buy Insurance: Buying back Call and Put at Strike price which 10% lower than Sell Strike Price is optional but recommended.

Watch Video for More Detail

Volatility Rush Strategy - Best for Options Traders

The Volatility Rush takes advantage of increasing options premiums into earnings announcements (EA) caused by an anticipated rise in Implied Volatility (IV). With this strategy, Buy a Call and Put at-the-money (a long straddle) 2-3 weeks before the EA when IV is lower. Sell the position either (1) the night before the EA when the company announces earnings pre-market, or (2) during the EA day when it announces post-market, generally capturing IV at or close to its peak.

This popular screen will give you a list of stocks whose Options premiums tend to rise into Earnings. It includes only those stocks whose Earnings are at least two weeks away from today.

Screen criteria:

  1. Earnings Date Start Date : Current Date + 15 Days
  2. Earnings Date End Date : Current Date + 30 Days
  3. Predicted Move (Next Day) Min : 5%
  4. Options Type: Weekly or Monthly if that lines up with the two to three-week lead-time for entering the trade

Strategy Guideline:

  1. Buy a Straddle at or close to the money two to three weeks pre-EA.
  2. Sell the position either the night before the EA when the company announces earnings pre-market, or during the EA day when it announces post-market.
  3. Expiration date should generally be the closest expiry immediately after the EA.
  4. Straddle price should not be more 60% of predicted move.

Predicted Move (Volatility)

Similar to Implied Volatility in Options. Expected volatility % based on our Proprietary Volatility Predication Model. We are expecting that stock price will likely to reach % in either direction by the end of next trading session after Earnings are released and not necessarily the closing volatility %.

Why is it important?

    This indicator helps

  1. Knowing expected volatility in stocks after Earnings helps to decide trading stocks before Earnings Announcement.
  2. Taking Advantage of volatility collapse following Earnings Results by using Advance Options strategies such as Spread and Straddles.

Since Last Earnings

Change in share price since last Earnings release.

Why is it Important?

When share has gained more than 10% since it's last Earning release, it tends to over react to minor bad news and give up some gains if not all. So, it contains more downside volatility than upside When share has dropped more than 10% since it's last Earning release, it tends to over react to minor good news and recover some drops if not all. So, it contains more upside volatility than downside.

EPS Surprise (%)

Occurs when a company's reported quarterly or annual profits are above or below analysts' expectations. Here is the formula to derive % EPS Surprice:

Actual EPS - Estimated EPS
------------------------------------- x 100
Estimated EPS

Why is it Important?

Earnings surprises can have a huge impact on a company's stock price. Several studies suggest that positive earnings surprises not only lead to an immediate hike in a stock's price, but also to a gradual increase over time. Hence, it's not surprising that some companies are known for routinely beating earning projections. A negative earnings surprise will usually result in a decline in share price.

Next Day Price Change (%)

Next Regular trading session Closing price following Earnings result.

For After Market Close Earnings, It is a next trading day closing price. For Before Market Open Earnings, It is the same trading day closing price.

Why is it Important?

Next Day price change is a reaction of Earnings result.

2026 Midterm Elections: 3 Ways to Trade Potential Stock Market Volatility

Posted on Oct 06, 2026 by Ian Cooper

2026 Midterm Elections: 3 Ways to Trade Potential Stock Market Volatility

The 2026 midterm elections could shake up the stock market as investors weigh what changes in Congress might mean for taxes, government spending, and business regulations.

With the election roughly a month away, JPMorgan (NYSE: JPM) is considering three possible outcomes:

  • A divided Congress, with each party controlling one chamber.
  • A Democratic sweep, with Democrats taking both the House and Senate.
  • Republicans keeping control of both chambers.

Each outcome could create different stock market winners as investors adjust their expectations for Washington’s next moves. Take the energy sector as one example. Should the Democrats take control of Congress, it’s likely that renewable energy stocks such as Brookfield Renewable Partners (NYSE: BEP) and Enphase Energy (NASDAQ: ENPH) may get a lift.

On the other hand, if the GOP retains control of even one chamber of Congress, the big oil trade is likely to continue. That bodes well for names like Chevron (NYSE: CVX) and refiners like Valero (NYSE: VLO).

But traders have another way to approach the election: watching for a potential increase in market volatility.

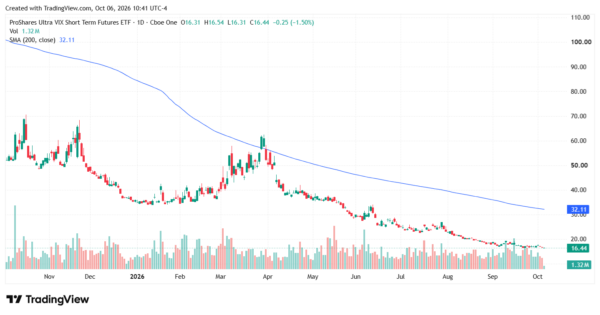
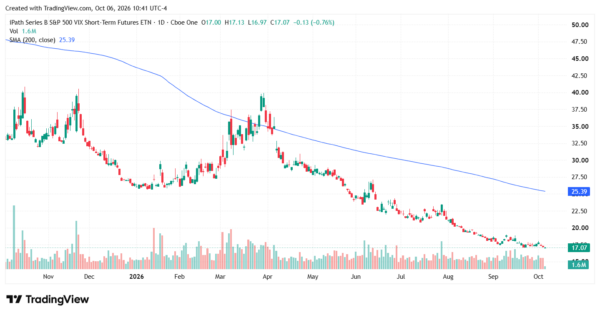
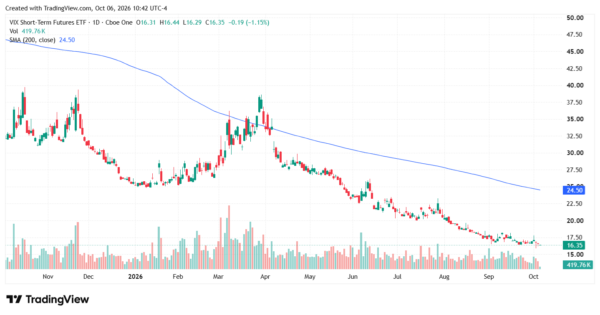
In fact, ETFs and ETNs, such as the ProShares Ultra VIX Short-Term Futures ETF (BATS: UVXY), Barclays iPath Series B S P 500 VIX Short Term Futures ETN Series B (BATS: VXX), and the ProShares VIX Short-Term Futures ETF (BATS: VIXY), can help offer exposure to volatility.

Why Market Volatility Deserves Attention


Election season gives investors plenty of headlines to digest. A surprising poll, a major policy announcement, or uncertainty about the final results could change the market’s mood quickly.

One way to monitor that mood is through the Volatility Index, better known as the VIX. Often called Wall Street’s “fear gauge,” the VIX uses S&P 500 options prices to measure how much investors expect the market to move over the next 30 days.

  • Ahead of the midterm elections in 1990, VIX jumped from 16 to 36
  • Ahead of the midterm elections in 1994, the VIX jumped from 11 to 18
  • Ahead of the midterm elections in 1998, the VIX jumped from 16 to 45
  • Ahead of the midterm election in 2002, the VIX jumped from 19 to about 44.
  • Ahead of the midterm elections in 2006 and 2010, the VIX fell
  • Ahead of the midterm elections in 2014, the VIX jumped from 12 to 40
  • Ahead of the midterm elections in 2018, the VIX slipped
  • Ahead of the midterm elections in 2022, the VIX jumped from 19 to 34

To trade potential spikes, we can use the ETFs and ETNs we mentioned just a moment ago. 

UVXY Offers Leveraged Exposure to VIX Futures 

The UVXY offers the most aggressive exposure of the three products discussed here because it uses leverage. The fund seeks 1.5 times the daily performance of the S&P 500 VIX Short-Term Futures Index, before fees and expenses. 

If the benchmark gains 10% in one day, UVXY aims to gain approximately 15% before costs. A falling benchmark can produce similarly amplified losses. Over several days, daily compounding means returns can differ from simply multiplying the benchmark’s total move by 1.5.
midterm elections - StockEarnings

VXX Provides Direct Exposure to Short-Term VIX Futures 

VXX offers another way to gain exposure to short-term VIX futures. Its returns are linked to the S&P 500 VIX Short-Term Futures Index Total Return, subject to applicable fees. There is an important difference in its structure: VXX is an exchange-traded note, or ETN. Investors also face issuer credit risk, meaning they depend on Barclays meeting its obligations.
midterm elections - StockEarnings

VIXY Offers Unleveraged Volatility Exposure

VIXY provides unleveraged exposure to the S&P 500 VIX Short-Term Futures Index. Its benchmark holds monthly VIX futures with a weighted average of approximately one month until expiration.

The key points: It seeks to match its benchmark before fees and expenses. It does not use UVXY’s 1.5x leverage.  For traders comparing these products, VIXY offers less aggressive exposure than UVXY. That does not make it a low-risk investment.
midterm elections - StockEarnings

Understand Contango Before Trading Volatility ETFs

All three products require attention to futures pricing.

When later-dated futures cost more than nearer-dated contracts, maintaining exposure can create a drag on returns. This condition, called contango, can hurt investors who buy too early and wait for volatility to arrive.

Before entering a trade, consider:

  • What event could drive volatility higher?
  • How long will you hold the position?
  • What loss would trigger an exit?
  • When would you take profits?

In the end, the 2026 midterm elections could give traders opportunities as Wall Street reacts to shifting expectations about Congress. 

For experienced traders, UVXY, VXX, and VIXY offer ways to position for rising volatility through futures exposure. The key is understanding what each product does, keeping the position manageable, and deciding when to exit before putting money at risk. 

Over the last 26 years, he’s taught thousands of investors how to trade news flow and herd mentality using a unique blend of technical and fundamental analysis. Cooper was among the few analysts to spot the financial crisis of 2008, the top of subprime and Alt-A, the death of Lehman Brothers, Bear Stearns, and New Century Financial, and even the Dow’s collapse to 6,500, as well as its recovery. He even called for gold to rally well above $1.500 when it traded under $600. At the moment, Cooper makes use of technical, fundamental and news analysis, to help individual investors grow their wealth. He’s a firm believer that hard work and thorough research will lead to investment success.

Join over 1.2M+ investors/traders who receive daily and weekly notable earnings alerts with predicted move