Goldman Sachs (NYSE: GS) sees opportunity in five stocks heading into their upcoming reports: Disney (NYSE: DIS), Baker Hughes (NASDAQ: BKR), Nu (NYSE: NU), UPS (NYSE: UPS), and Omnicom (NYSE: OMC). Each, according to Goldman Sachs, has an opportunity to improve earnings.
Disney Stock Offers a Long-Term Earnings Growth Story
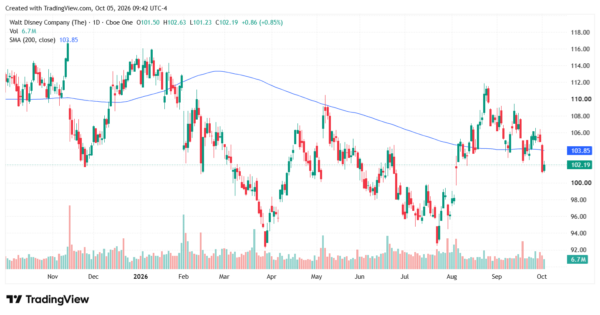
Disney remains a favorite of Goldman analyst Michael Ng, who sees several years of earnings growth ahead. His argument reaches across Disney’s businesses, including theme parks, entertainment, and sports. Goldman believes the company is still early in an investment cycle that could strengthen its offerings and support future profits.
Ng estimates earnings per share could grow at a compound annual rate of roughly 13% over the period covered by his outlook. That means he expects earnings to build on themselves over time, although growth won’t necessarily follow a straight line. He lowered his price target to $140 from $144 but maintained his positive stance.
Baker Hughes Stock Could Benefit From Its Chart Industries Deal
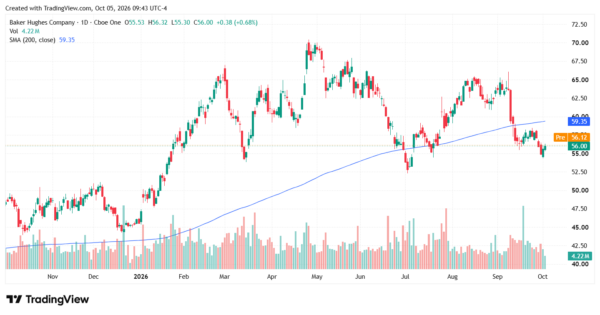
With Baker Hughes, Goldman analyst Neil Mehta reinstated coverage with a Buy rating following the company’s acquisition of Chart Industries. He sees opportunities for the combined business to increase revenue and improve profit margins.
The reasoning is straightforward. Combining operations could reduce overlapping expenses, while a broader geographic reach could help the company sell more products and services to more customers. Goldman sees several ways for earnings to expand through 2030, suggesting its investment case extends well beyond the next quarterly report.
Nu Stock Has Room to Expand in U.S. Consumer Lending
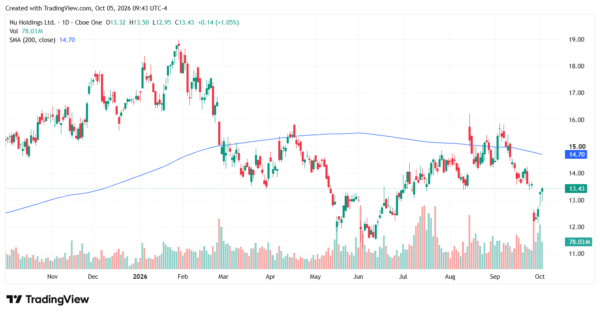
Nu Holdings has attracted Goldman’s attention for its potential expansion into U.S. consumer lending. Analyst Tito Labarta believes the Latin American financial technology company’s digital approach could help it compete. The appeal centers on keeping operating costs low while making financial services convenient for customers. Goldman also points to Nu’s ability to expand without allowing expenses to rise at the same pace.
That combination could be valuable in a new market, although the U.S. lending business is highly competitive. Winning customers is only part of the challenge. Nu would also need to manage lending risks and expansion costs.
Labarta maintained a Buy rating and a $23 price target. Notably, Goldman’s estimates include some initial U.S. expansion expenses without incorporating the potential upside.
UPS Stock Could Gain as Cost Cuts Improve Profitability
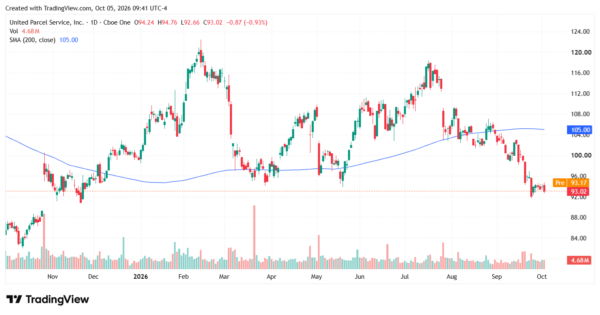
UPS has been reducing Amazon package volume and adjusting its costs accordingly. That transition can weigh on results while the business reshapes its delivery network. Goldman believes profit growth could become more consistent as that process concludes. The bank expects a leaner domestic operation, greater automation, and a more profitable mix of shipments to improve the business.
The important distinction is that package volume and profitability don’t always move together. Delivering more packages isn’t necessarily better if those shipments generate limited profit.
Investors will want evidence that cost reductions are keeping pace with volume changes and that the remaining business can produce stronger returns.
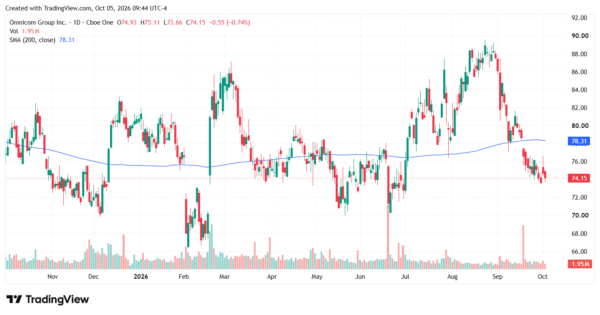
Goldman believes Wall Street may be underestimating Omnicom’s underlying revenue growth.
Its optimism centers on the advertising company’s media business, where it expects continued double-digit growth. The bank also highlighted a valuation of roughly six times estimated 2027 earnings in its cited analysis. That could attract investors if upcoming results support its growth expectations.
These Five Stocks Have Earnings Catalysts to Watch
These five stocks offer different paths to stronger earnings. Disney is investing in its businesses, Baker Hughes is looking to benefit from an acquisition, and Nu has opportunities to reach new customers. Meanwhile, UPS is working to improve profitability, and Omnicom could benefit if its growth proves stronger than Wall Street expects.
What makes this group interesting is that each company has something specific investors can watch. Are investments translating into higher profits? Are cost cuts improving margins? Is expansion bringing in enough business to justify the expense? The upcoming earnings reports should help show how much progress these companies are making.
Of course, a Buy rating from Goldman Sachs doesn’t guarantee a stock will rise. Expectations matter, too, and even a solid quarter can disappoint investors who were looking for more. That’s why management’s outlook deserves just as much attention as the headline earnings numbers.
For investors building a watchlist, these five names provide a useful starting point. The next step is to see whether their results—and the price investors are being asked to pay—support the optimism.