Betting on Alaska Airlines (NYSE: ALK) or any of its peers is simply a high-risk endeavor; there’s just no denying this harsh reality. Since the start of the year, ALK stock is down more than 21%, and I’d say for good reason. With macroeconomic pressures and geopolitical concerns translating into energy cost anxieties, Alaska just doesn’t provide much confidence for bullish, debit-side options traders.
However, it’s also generally true that extended streaks — whether of the optimistic or pessimistic variety — often create exploitable opportunities. Mechanically, that’s because extended selling or buying can change positioning, liquidity and how participants perceive the security. In turn, this change in perception may potentially alter what happens next to the equity in question.
Consider someone who comes across a supposedly gently used Italian sports car in the second-hand market, selling for a ridiculously low price of $20,000. If all other things were equal, you’d be hard-pressed not to make the purchase. But let’s then suppose that you found that the vehicle was caught in a flash flood.
In this analogy, the vehicle itself did not change, but the value proposition certainly did. What seemed like a killer deal no longer is so based on this new information. It’s a similar principle to what we have with ALK stock.
Right now, Alaska Airlines stock is not viewed by the market in the broader sense of being a reliable airline. No, right now, Wall Street’s overwhelmingly dominant view is that its equity is mired in technical troubles. Because of this negative perception, the probability of where ALK heads next has also shifted.
Nevertheless, the common argument — that ALK stock may continue to tumble — might not be accurate. Because so much bad news has been baked into the share price, there may be heightened upside risk; that is, Alaska could be more susceptible to a bounce higher.
Still, we’re going to quantify this hypothesis rather than merely accepting the presupposition.
Taking What the Market Will Give You with ALK Stock
Before even starting an analysis, you should know that the market has been incredibly pessimistic about Alaska Airlines stock recently. Earlier, in my YouTube channel, I posted a video explanation about an ALK options trade expiring Nov. 20. At the time, the ticker price was $38.70.
On Friday, ALK stock moved up to $39.53, yet both the November and December monthly option chains both offer asymmetric risk-reward payouts. I believe part of the “generosity,” for lack of a better word, stems from the security’s volatility skew. For these two chains, along with the October monthly, traders appear to be paying higher premiums for downside risk protection.
That doesn’t mean that there isn’t pricing for upside convexity, as the December monthly currently shows. Still, it does seem quite obvious that the smart money doesn’t believe it’s prudent not to have some insurance against the threat of extreme volatility. On the surface, such hedging doesn’t seem to endorse optimism for Alaska Airlines stock.
But this might be a case where you simply take what the market will give you. In this example, the $45 strike price is the lowest strike available for a multi-leg options trade that still offers a favorably asymmetric payout for the debit-side trader. I believe there’s good reason to take this bet.
Yes, a move to $45 requires a roughly 14% move from the current level, which may seem astronomical for ALK stock. We’re talking about an equity that only has a 1.33 60-month beta. That might not seem enough to overcome a 14% gap. However, this is a comparison across a five-year period. I would propose that under certain, specific circumstances, the beta could be much, much higher.
Calculating the Odds for Alaska Airlines Stock
Let’s look at the 42.50/45 bull call spread expiring Dec. 18, which is about 11 weeks away. At a quick glance, the trade seems asymmetrically attractive. You risk $95 for the chance to profit $155, with the bull spread offering a maximum payout of over 163% should ALK stock rise through and trigger the $45 strike on expiration.
The problem? While the wager may be enticing, the odds aren’t compelling. Wall Street’s options pricing mechanism pegs the probability of profit (breakeven) at only 34.6% — and that’s for the transaction to draw dead even at $43.45 on expiration.
To actually find out the odds of Alaska Airlines stock hitting $45 on Dec. 18, we would need to turn to OptionCharts.io’s Probability Distribution screener. Here, the distribution curve pegs the probability at only 25.96%.
Under expected value (EV) calculations, this wager as presented would almost certainly not be recommended by most financial experts. According to OddsJam.com, the $95 wager associated with the 42.50/45 bull spread above will have an EV of $30.09 below parity. Since you’re only projected to break even about 35% of the time, this options bet does not seem very practical.
Nevertheless, we must also remember that the unknown future is, by definition, unknown. As such, we must question the presupposition that goes into calculating the above probabilities.
Using a Markov Chain Analysis
To get a potentially better read on the dilemma, we may use some of the principles associated with Markov chains. Basically, in a Markov process, the transition to a future state depends on the current state. In our case, with ALK stock being mired in a deeply pessimistic Markov state, we want to know what the probability of transition is to an optimistic state.
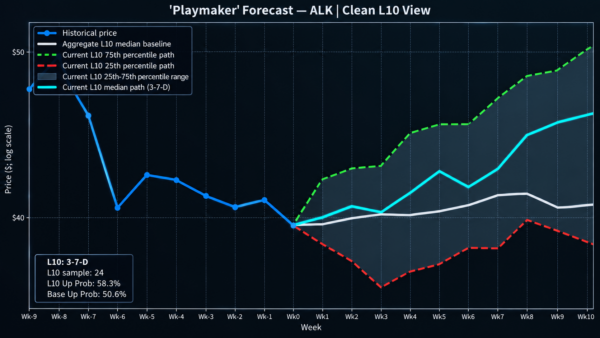
In the last 10 weekly candlesticks, ALK stock had printed only three up weeks, which means that 70% of the unit-wise volume of the defined period was net bearish. Since January 2022, this particular Markov state, which I’ll abbreviate as 3-7-D (three up weeks, seven down weeks, downward slope) has only materialized 24 times on a rolling basis.
Of this figure, we have seen Alaska Airlines stock exceed the equivalent of the $45 strike price 14 times on week 10 — one full week ahead of the Dec. 18 expiration date. Under this axiomatic framework, we can say that the odds of ALK triggering full profitability of the 42.50/45 bull spread stand at about 58.3%, minus a small penalty for a potential early exit.
Either way, that’s a much better proposal than 25.96%.
Of course, a Markov-based framework is still a presupposition, much like the Black-Scholes framework that undergirds standard option-pricing models. But because the future is inherently ambiguous, we’re not beholden to one universal model. Instead, I’m proposing that under certain circumstances were state-to-state transitions are more likely, a Markov chain analysis may be more instructive.
If you share this belief, Alaska Airlines stock deserves a closer look.