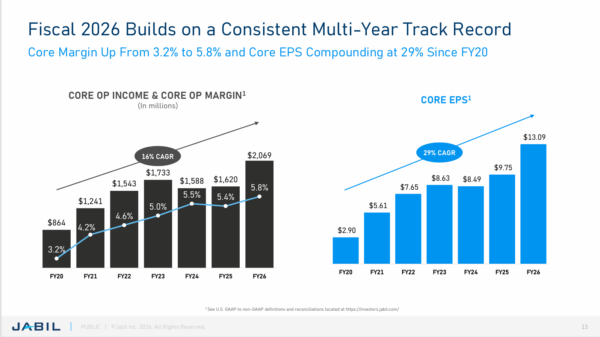
Jabil Inc. (NYSE: JBL) is moving deeper into the part of the hardware cycle where the biggest manufacturing commitments get made, and its FY27 numbers show what that shift looks like in dollars: revenue is expected to rise from $35.95 billion to $44.5 billion ($8.55 billion increase) while core EPS climbs from $13.09 to $17.55.
The striking part is where that $8.5 billion of additional revenue is coming from. Almost all of it comes from Intelligent Infrastructure, where Jabil is getting involved earlier in the design of data-center systems, before those designs turn into factory orders.
The $8.5 Billion Increase Has A Very Specific Shape
Jabil’s fourth quarter already showed the direction of travel, with revenue climbing 29% year over year to $10.62 billion, while core operating income reached $675 million and core EPS jumped to $4.40 from $3.29. Intelligent Infrastructure grew 56% during the quarter and carried a 6.5% core margin, compared with 5.8% for Regulated Industries and 7.1% for Connected Living & Digital Commerce.
Then the FY27 buildout puts some very specific numbers behind that acceleration. Intelligent Infrastructure is projected to move from $17.9 billion to $25.6 billion, adding $7.7 billion by itself. Within that segment, Cloud & Data Center Infrastructure contributes $6.0 billion of growth, Capital Equipment adds $1.2 billion, and Networking & Comms another $500 million.
That $7.7 billion Intelligent Infrastructure increase represents roughly 91% of Jabil’s $8.5 billion companywide revenue expansion. Regulated Industries adds another $900 million, while Intelligent Devices & Robotics declines by $100 million, bringing the total bridge to the full $44.5 billion target. The shape of the forecast is therefore unusually concentrated, as most of the incremental revenue is coming from the infrastructure businesses tied to data centers, compute, power, cooling, and networking.
Jabil Is Getting Into The Build Before The Factory Order
The more revealing number is buried in Jabil’s description of how those infrastructure programs are won: four of its six largest data-center wins in FY26 began as design engagements. The company has more than 9,000 engineers working with customers earlier in their decision cycles, providing design and process support before manufacturing begins.
Now that changes the economic sequence. A manufacturer that enters after a customer has already finalized a product can compete primarily for production. But Jabil is describing a model where its engineers are involved while the customer is still deciding how the system gets built, allowing Jabil to work across compute, networking, power, and cooling before the production footprint is locked in.
And you can also see the result inside the capacity numbers as well. Jabil says new capacity across its more than 120 facilities worldwide is beginning to fill with committed customer programs, while FY27 growth includes ramps across compute, power, liquid cooling, modular power and related services.
Put those pieces together and the $7.7 billion Intelligent Infrastructure increase stops looking like a single-year sales target. A customer enters through engineering, the relationship expands into a broader system, production requirements follow, and Jabil adds capacity against programs it already has visibility into. Four of the six largest data-center wins following that path in FY26 gives the model some actual operating evidence.
More Volume Is Reaching The Cash Register
Understand that Jabil does not need to pour capital into that growth at the same rate as revenue. FY26 produced $1.532 billion of adjusted free cash flow, while net capital expenditures were just 1.3% of revenue, while net capital expenditures were only 1.3% of revenue.
That gives the expansion a useful financial characteristic: Jabil can add manufacturing capability while still producing substantial cash for shareholders. The company returned $1.06 billion through buybacks during FY26 and has authorized another $1.5 billion repurchase program, while its longer-term framework calls for net capex of 1.5%–2% of revenue and 100%+ adjusted free-cash-flow conversion.
There is also a useful margin clue here. Core operating margin was 5.8% in FY26 and is expected at 6.1% in FY27, only a 30-basis-point improvement. Jabil therefore does not need an enormous margin expansion to produce the earnings growth embedded in its numbers. The bulk of the earnings increase is coming from putting substantially more revenue through the existing operating model.
A Strong Business And A Chart That Needs A Reset
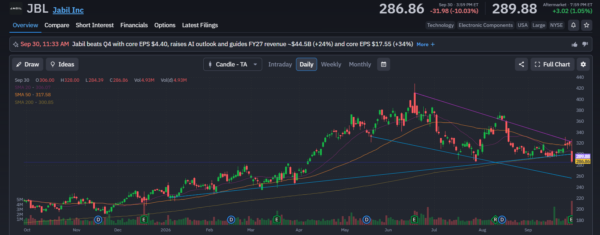
The stock closed September 30 at $286.86 after falling 10.03%, putting it beneath its 20-day moving average around $306, its 50-day around $318, and its 200-day around $301. The price has also broken beneath the descending trend structure that developed from the summer highs, bringing the stock back towards the high-$280, where the chart shows a rising support line
That creates two very different pieces of information. The earnings presentation shows a business preparing for another substantial expansion in infrastructure revenue, while the chart shows investors aggressively repricing the shares after the report. I would treat roughly $280 as the line that needs to hold before calling the current decline a deeper technical breakdown. Above that, a reclaim of 300–307 would put the stock back above the 20-day average, with 317–320 becoming the next area to watch around the 50-day average. JBL is a nice buy at $286, but I would size it around the chart rather than chase the earnings-day volatility.