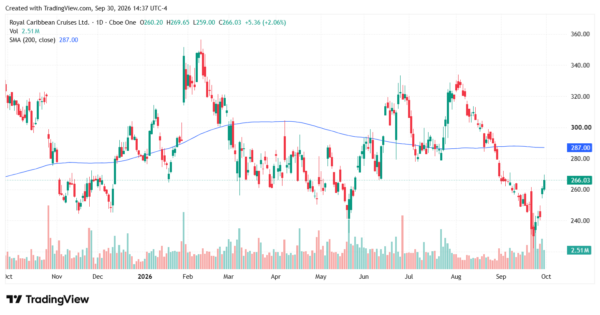
Keep an eye on oversold shares of Royal Caribbean (NYSE: RCL). Royal Caribbean stock has attracted fresh attention from Wall Street after Bank of America and Deutsche Bank upgraded the shares to Buy following a sharp pullback.
Bank of America (NYSE: BAC) maintained its $330 price target, while Deutsche Bank (NYSE: DB) kept its target at $299. Their argument is straightforward: The shares have become cheaper, while demand for the company’s vacations appears to be holding up.
That combination of a lower valuation and resilient travel demand is the foundation of the bullish case. But investors still need to consider whether Royal Caribbean can maintain strong pricing, manage rising capacity, and turn its Sandals investment into another source of growth.
RCL Stock Offers a Lower Price for a Strong Business
Bank of America believes the underlying business remains strong. Its analysts pointed to returns on invested capital in the high teens and EBITDA margins approaching 40%. Those figures suggest Royal Caribbean is generating substantial earnings from its operations and putting the money invested in its business to productive use.
The company also has an investment-grade balance sheet, another point in its favor. That matters in an industry where building ships requires enormous amounts of capital and weaker travel demand can put pressure on cash flow.
For RCL stock, the significance is that investors are getting exposure to a business with strong operating economics at a lower share price than before the recent selloff. The question is whether those economics can remain intact as the cruise industry adds capacity.
Travelers Are Still Spending
Perhaps the most encouraging part of the analysts’ case is that consumers still appear willing to spend on travel. Bank of America said travel spending has grown at a mid- to high-single-digit rate since February. Cruise spending showed even stronger momentum, accelerating to growth in the mid-teens during July and August.
For Royal Caribbean, those trends support the idea that the stock’s decline may reflect investor worries more than a meaningful deterioration in vacation demand. Still, spending across the industry does not guarantee the same results for every operator.
Comments from Royal Caribbean at a recent Bank of America conference also gave the bank confidence in the company’s outlook. Its analysts expect fourth-quarter 2026 net yield growth of at least 4%, which they believe would lead the industry.
Looking ahead, Bank of America believes Royal Caribbean could guide for 2027 net yield growth of 2% to 3%, consistent with its historical framework.
Sandals Could Add Another Growth Catalyst
There is also a new piece to the growth story: Royal Caribbean’s announced $3 billion investment for a 50% stake in Sandals Resorts. Bank of America estimates the transaction could add 3% to 4% to EBITDA in the near term. Beyond that initial contribution, the bank sees opportunities for Royal Caribbean to help improve the resort business through its pricing experience, purchasing capabilities, and loyalty program.
The idea is that Royal Caribbean could apply some of its operating strengths to Sandals, helping the business generate more profit from its existing properties. Customer relationships could also offer opportunities to introduce travelers to different vacation options.
Bank of America estimates the venture could deliver annual EBITDA growth in the low- to mid-teens through 2030, potentially lifting Sandals’ EBITDA from about $600 million to $900 million. Those are projections, however, and realizing them will depend on execution.
Rising Cruise Capacity Could Pressure RCL Stock
Of course, there are reasons the shares became cheaper.
Competing cruise capacity in the Caribbean is expected to increase by a high-single-digit percentage in 2027, according to the firm. More available cabins could make it harder to raise prices if demand fails to keep pace. Fuel costs remain another concern, although Royal Caribbean has hedged more than half of its 2027 fuel exposure. That provides some protection, but it does not eliminate the risk of higher costs.
The capacity issue may be the biggest test of the bullish thesis. Royal Caribbean can benefit from strong demand, but if industrywide capacity grows faster than bookings, pricing power and net yields could come under pressure.
Is Royal Caribbean Stock a Buying Opportunity?
Even with those risks, the upgrades suggest both banks see a more appealing balance between potential rewards and possible setbacks after the selloff.
For investors, the key question is whether Royal Caribbean can keep growing earnings while managing competition and costs. If demand remains resilient and management delivers, the lower valuation could prove attractive. The opportunity rests on that performance, and upcoming bookings, pricing, and guidance will help investors judge whether the analysts’ optimism is justified.
In other words, the Royal Caribbean stock story now comes down to execution. Strong travel demand, healthy net yields, and potential growth from Sandals provide several catalysts, while rising cruise capacity and costs remain important risks to monitor.