Micron Technology (NASDAQ: MU) generated $43.97 billion of operating cash flow in the fourth quarter, then spent $10.77 billion on net capex and still had $33.20 billion of adjusted free cash flow left over.
A memory company throwing off that kind of cash can do something it couldn’t do during the last cycle: build capacity while the shortage is still paying for it. Micron finished FY2026 with $89.68 billion of operating cash flow and $62.31 billion of adjusted free cash flow, and management is already raising its FY2027 capital spending plans.
The Q4 numbers themselves were just as aggressive, with revenue reaching $54.23 billion, adjusted EPS hitting $33.42 and gross margin climbing to 87%.
But the cash is where I think the earnings story gets more useful. Micron is taking the profits created by today’s memory shortage and putting them into the fabs that will create tomorrow’s supply, while customers are already putting billions down to secure that future capacity.
The Memory Shortage Is Paying For The Next Memory Cycle
Monday’s pre-earnings work established how extreme the pricing environment had become. In Q3, DRAM revenue rose 67% sequentially to $31.3 billion even though bit shipments grew only in the low-single digits, while DRAM ASPs rose in the low-60% range. NAND revenue climbed to $9.9 billion as ASPs jumped in the mid-80% range.
Q4 kept that engine running, although the product mix is getting more important. DRAM revenue increased 27% sequentially to $39.77 billion, with bit shipments up in the mid-single digits and ASPs up in the high-teens. NAND revenue rose 42% to $14.10 billion, with shipments up roughly 10% and ASPs around 30%.
Core Data Center revenue jumped 56% to $18 billion and reached a 90% gross margin, while data-center SSD revenue approached $10 billion, more than ten times the year-ago quarter. Put another way, Micron is getting paid more for scarce memory while moving more of its business toward AI infrastructure products that require higher capacity and performance.
Customer Commitments Changed The Math
Our Monday article had 16 strategic customer agreements covering roughly 20% of DRAM volume and one-third of NAND volume, with 14 agreements carrying about $100 billion of minimum-price revenue commitments.
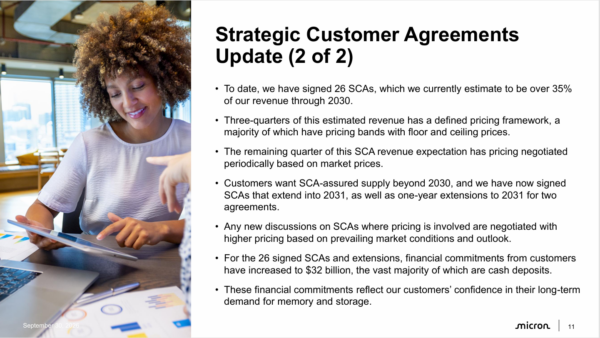
The Q4 presentation now shows 26 agreements, expected to represent more than 35% of company revenue through 2030. Customer financial commitments have risen to $32 billion, with the vast majority in cash deposits, while three-quarters of expected SCA revenue has a defined pricing framework.
I like this development because it gives Micron something unusual for a memory company heading into a giant capacity expansion: visibility. The company expects fiscal 2027 capex to rise from previous plans, with much of the additional construction aimed at bringing cleanroom space online from late 2028. Management also says it has no clear line of sight to when DRAM supply and demand return to balance.
The old memory-cycle script is familiar: high prices create high profits, high profits create capacity, capacity eventually overwhelms demand, and margins collapse. Micron is trying to get customers to commit to that capacity before it arrives.
How Much Of The Cycle Has Changed
The first test is already in the guide. Micron expects Q1 revenue of $61.5 billion, adjusted EPS of $38.15 and gross margin of roughly 86.25%. Management expects Q1 to be the gross-margin floor for FY2027 and margins to rise through the year even as the rate of price increases moderates.
That is a much more useful signal than another quarter of extraordinary ASP growth. If Micron can keep expanding earnings while memory pricing becomes less explosive, the combination of mix, HBM, data-center SSDs and contracted demand is doing some of the work that shortage pricing has been doing so far.
The balance sheet gives it plenty of ammunition. FY2026 operating cash flow reached $89.68 billion and adjusted free cash flow reached $62.31 billion after $27.37 billion of net capex. Cash, marketable investments and restricted cash ended the year at $73.48 billion.
A Fair Buy?
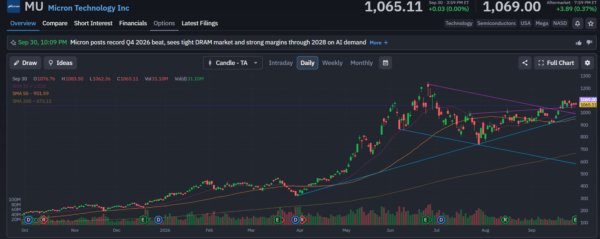
MU closed September 30 at $1,065.11 after trading as high as $1,083.50. The 20-day moving average is around $1,010, the 50-day sits near $952, and the 200-day is around $673.
That leaves the stock above all three averages and above the $1,000 level we marked before earnings. The recent structure remains constructive, but there is a clear ceiling overhead: the June peak around $1,220 and the descending trendline running from that high.
The $1,000 area is now important because it is sitting underneath the post-earnings breakout and close to the 20-day average. If MU holds there, the chart gives buyers room to work toward the $1,100 area and eventually the $1,220 peak. A sustained move through $1,100 would put the stock directly against that descending trendline, so I would expect some resistance there rather than assuming another straight-line move higher.
The other side is just as clean. Losing $1,000 would weaken the breakout, and a break below roughly $952 would put the 50-day average in play and give me a reason to stop chasing the move.
I like MU here. I’d call it a fair buy, rather than a stock I would aggressively chase after such a violent run. The fundamentals have earned a premium with Micron converting today’s shortage into cash, locking customers into future capacity and using that cash to build the next supply wave. With the stock above $1,000 and the 20-day average still rising underneath it, I’d be comfortable buying some here and adding on a clean hold above $1,100 or a controlled pullback that respects $1,000.