D-Wave Quantum (NASDAQ: QBTS) is beginning to collect commercial proof that its quantum computers can solve problems businesses are willing to pay to fix. But its third-quarter earnings report shows how much work remains before that traction becomes a scalable revenue engine.
Third-quarter revenue increased 21% year over year to $4.51 million, while diluted loss per share narrowed to 13 cents from 41 cents. The more striking figures sit outside the income statement. Nine-month bookings climbed 611% to $37.4 million, and remaining performance obligations surged 1,221% to $38.3 million. D-Wave has customers moving quantum applications into production, but investors still need to see those commitments translate into a much larger stream of recognized revenue.
Commercial Pipeline Is Finally Producing Tangible Wins
The most persuasive part of D-Wave’s latest update is the growing evidence that customers are moving beyond experimentation and putting its annealing technology to work in operating environments. NTT DOCOMO, Japan’s largest mobile operator, deployed its second production application powered by D-Wave’s hybrid quantum technology, using it to optimize tracking-area lists across multiple network regions.
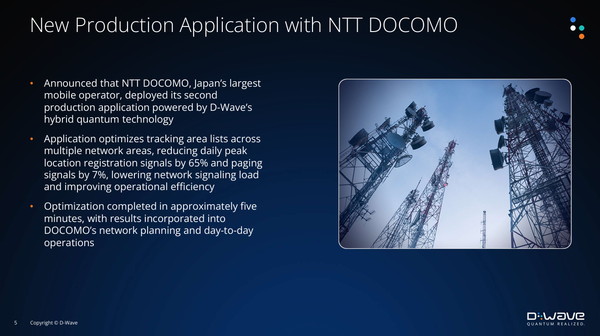
The application reduced daily peak location-registration signals by 65.3% and paging signals by 7%, with a representative problem involving 333 base stations completed in approximately five minutes. Those results give D-Wave a concrete enterprise use case with measurable operational benefits.
The commercial pipeline also includes a two-year, $10 million engagement with a Fortune 100 customer to develop multiple quantum applications, with the first application already in production. Separately, D-Wave secured a $20 million system sale to Florida Atlantic University, which management expects to deliver in the fourth quarter. Those two contracts help explain the surge in bookings, although they also show why investors should look beyond the headline growth rate.
Nine-month bookings rose from $5.3 million in 2025 to $37.4 million in 2026, but the figure includes $2.3 million in Quantum Circuits bookings completed just before its acquisition in January. The $20 million FAU order also represents a substantial portion of the total. Remove that single transaction and bookings still show growth, but the underlying pace is less explosive than the 611% headline suggests. Meanwhile, third-quarter bookings actually declined approximately 19% year over year to $1.9 million, illustrating how much individual large transactions can influence quarterly results.
The Backlog Is Growing At Record Pace
D-Wave’s $38.3 million in remaining performance obligations offers another measure of commercial momentum because it represents revenue attached to non-cancellable orders for services that have not yet been performed. Management expects approximately 59% of that balance to become revenue within 12 months and 71% within 24 months.
That implies roughly $22.6 million and $27.2 million, respectively, could be recognized over those periods, assuming the expected timing holds. For a company that generated just $10.45 million in revenue during the first nine months of 2026, the potential conversion is substantial.
The revenue mix is also shifting toward services and cloud access. Third-quarter QCaaS revenue increased to approximately $2.2 million from $1.4 million a year earlier, while professional-services revenue rose to $2 million from $500,000. System-sales revenue, however, declined by $1.5 million year over year. This mix suggests D-Wave is developing more ways to monetize its technology after the initial hardware sale, although professional services carry lower margins and cannot become the dominant source of growth if the company wants a scalable commercial model.
That is the central test for QBTS. CEO Alan Baratz has described professional services as a way to help customers move applications toward production, rather than the business D-Wave ultimately wants to become. The company needs those engagements to lead to recurring QCaaS contracts, additional system sales and wider deployments. NTT DOCOMO’s second production application is encouraging evidence of that progression, but a handful of customer wins does not yet establish a repeatable sales engine.
Rising Costs Keep The Progress In Perspective
D-Wave is investing heavily to build that business, and the expense is visible in its operating results. Third-quarter operating expenses increased 84% year over year to $55.9 million, while revenue grew 21%. GAAP gross margin fell to 52.9% from 71.4%, partly because professional services accounted for a larger share of revenue. Adjusted EBITDA loss widened 83% to $37.7 million, reflecting increased spending on product development and go-to-market initiatives.
Liquidity gives D-Wave room to continue investing, but the runway is not unlimited. Cash and marketable investment securities totaled $503.4 million at September 30, down from $884.5 million at the end of 2025. Operating activities consumed $109 million during the first nine months, compared with $53.6 million in the prior-year period. The company has also finalized an agreement providing access to up to $100 million in CHIPS and Science Act funding, distributed in installments after specified milestones and conditions are met. That funding supports its development plans, but it should not be treated as unrestricted cash already received.
QBTS Still Needs To Win Back Its Chart
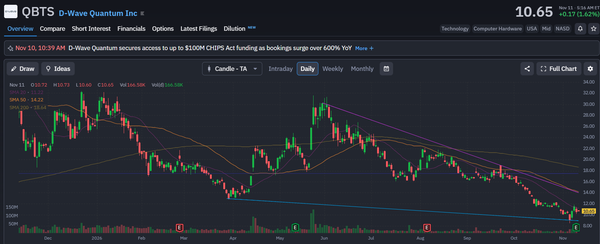
As of this moment, the stock is in a sustained downtrend, trading at $10.65 and below its 20-day moving average of $11.22, 50-day average of $14.22, and 200-day average of $18.64. The descending trendline from the June peak near $30 remains intact, while the recent price action has pushed QBTS toward the 8–10 area. A move above the 20-day average would be an initial improvement, but reclaiming the 50-day average would provide a more meaningful sign that buyers are regaining control.
Does the Business Justify a Buy?
D-Wave’s commercial progress gives the business a credible opportunity to grow, and the backlog provides a measurable pool of potential near-term revenue. However, widening operating losses, cash consumption, and the stock’s damaged technical structure leave little room for execution missteps.
I’m cautiously bullish on the business’ commercial opportunity, but staying away from QBTS at its current technical position. The next earnings reports need to show that bookings are converting into revenue and that customer deployments can expand beyond a small number of major contracts before the stock can justify a sustained recovery.

