Retail stocks got an early holiday spark this week, just ahead of a busy stretch of retail earnings. Costco Wholesale (NASDAQ: COST) jumped about 2% on Nov. 11 after announcing a $30-per-share special dividend. The payout is scheduled for Dec. 4 to shareholders of record on Nov. 24.
The board also reauthorized a $4 billion share repurchase program. Together, the moves signal confidence in Costco’s ability to generate cash.
Still, the 2% move needs context. COST stock has climbed about 15% over the last three months. That run suggests many investors were already pricing in a special dividend. Costco has a long history of rewarding shareholders this way, and the market knew it.
Costco is likely to post solid numbers when it reports earnings on Dec. 10. But investors won’t have to wait that long for a read on retail earnings. Walmart, Target, and TJX Companies all report next week.
Each retailer brings a different story into its report. One is a bellwether for the consumer. One is defending a massive rally. One is trying to prove a stumble was temporary.
For investors looking for a stock to put under their own tree this holiday season, those differences matter. Here’s what to watch from each.
Walmart Gives Investors a Real-Time Read on the Consumer
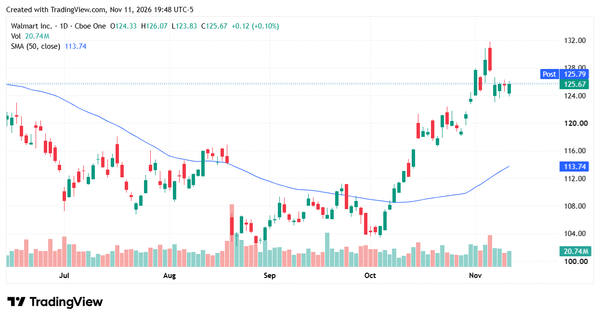
Walmart (NASDAQ: WMT) reports before the market opens on Nov. 19, capping a busy week of retail earnings. Few companies offer a clearer window into the health of the U.S. consumer.
Right now, that window shows two different shoppers. Lower-income households remain stretched and are still hunting for value. At the same time, more higher-income consumers are shopping at Walmart for groceries and essentials. That second group has helped offset pressure at the low end.
Analysts expect earnings of about 63 cents per share, up from 62 cents a year ago. Walmart has topped the consensus estimate in seven of its last eight quarters.
The challenge is valuation. WMT stock is up about 12.8% in 2026. Based on the consensus price target, analysts see only about 4.5% upside from here. It also trades at around 45x earnings, which is a premium to its own history as well as to the broader market.
That doesn’t make Walmart a bad stock. It does mean a good report may already be priced in. Investors may need a clear beat-and-raise to push shares meaningfully higher.
Target Will Show Investors Whether the Rally Has Room to Run
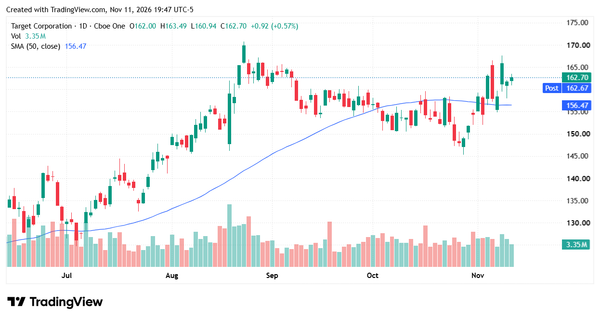
Target (NYSE: TGT) was the darling of the last retail earnings season. In August, the company beat estimates and raised guidance. Investors rewarded it handsomely.
In fact, TGT stock is now up more than 66% in 2026. That’s a remarkable turnaround for a retailer that posted declining sales for much of 2025.
Now comes the harder part. Target must deal with the privilege of expectations. Analysts expect earnings of about $2.08 per share when it reports on Nov. 18. That compares with $1.78 a year ago, and the bar is higher than it has been in years.
The key question is whether the easy gains are over. Much of the 2026 rally came from improving sentiment off a low base. Further gains will likely require proof that traffic and comparable sales are improving sustainably.
Investors should listen closely to holiday-quarter guidance. Target leans more on discretionary categories like home and apparel than Walmart does. That leaves it more exposed if middle-income shoppers pull back.
A solid report could keep the momentum going. But after a 66% run, even a modest disappointment could trigger profit-taking.
TJX Offers Investors the Most Upside If the Rebound Arrives
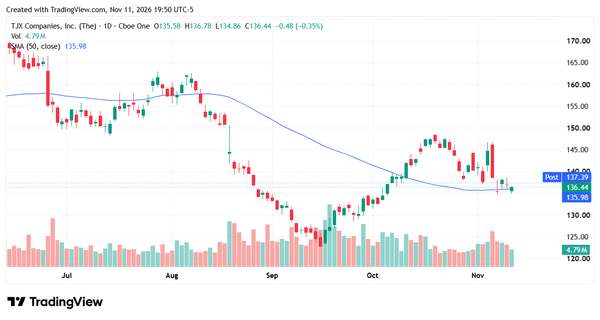
TJX Companies (NYSE: TJX) has been the laggard of this group. The stock is down about 11% in 2026.
Most of that decline came after the company’s second-quarter report in August. Marmaxx, its largest U.S. segment, underperformed. Investors focused on that weakness, and the stock has drifted lower since.
That reaction may have created an opportunity. Management forecast a rebound in the coming quarters. TJX reports before the open on Nov. 18. Analysts expect earnings of $1.33 per share, up from $1.28 a year ago.
TJX also has a strong track record of clearing the bar. It has beaten the consensus earnings estimate in each of its last eight quarters.
The off-price model fits this environment. TJX benefits when consumers want brand names at lower prices. It also benefits when other retailers have excess inventory to sell cheaply.
If the report shows Marmaxx getting back on track, the stock could be repriced quickly. With shares starting from a lower base, TJX may offer the most upside of the three.
Dividends Pay Investors to Wait Out a Tough Market
There’s a contrarian case to weigh before buying any of these names. Even with solid retail earnings, consumer-facing stocks are likely to remain under pressure. Elevated prices and cautious shoppers are real headwinds heading into 2027.
In that light, Walmart, Target and TJX may simply be the best houses in a bad neighborhood. Strong execution can’t fully offset a weak backdrop.
That’s where dividends help. All three companies pay a regular dividend. Walmart and Target are both long-tenured dividend raisers, and TJX has steadily grown its payout as well.
A dividend won’t prevent a sell-off. But it does pay investors to wait while the consumer picture comes into focus.
The Best Present Investors Can Give Themselves This Season
Costco’s special dividend is a welcome gift for shareholders. But with the stock up about 15% in three months, much of that good news looks priced in.
Next week’s retail earnings will offer a fresher read on retail stocks. Walmart is a quality name with limited upside. Target has to defend a huge rally.
TJX stands out as the best risk-reward setup. Expectations have reset lower, management has guided to a rebound and the company rarely misses. If Marmaxx delivers, TJX may be the best present investors can give themselves this holiday season.

