USA Rare Earth (NASDAQ: USAR) delivered a third-quarter 2026 report that tested short-term traders more than long-term holders. Monday’s Q3 report showed just $3 million in revenue, against a consensus estimate of $6.5 million. The company posted a $19.9 million gross loss and an adjusted loss of 44 cents a share. GAAP net income was positive only because of a $137 million gain on financial instruments.
The miss landed on a stock that had already pulled back sharply. USAR shares closed Monday at $8.76. They fell about 10% in early trading Tuesday, to near $7.90. That likely marks a fresh 52-week low. The stock now sits roughly 75% below its early-June high near $32. It also trades more than 55% below its 200-day moving average of $18.55.
Still, the headline numbers capture a company caught between phases. Its Stillwater, Oklahoma, plant recorded its first commercial magnet sales in Q3. Serra Verde, the Brazilian mine added through a completed merger, began commercial-scale shipments in October. Sales under its 15-year offtake started in November. Almost none of that shows up in Q3 revenue. That makes the fourth quarter the first real look at what USA Rare Earth can earn.
For long-term holders, that timing was always part of the plan. USAR was never a get-rich-quick story. The selloff may simply be flushing out weak hands. Now the story shifts from national security to revenue, margins, and execution.
USA Rare Earth Must Turn Strategic Importance Into Revenue
It does have $1.2 billion in cash to execute with. But this is a stock priced on strategic importance, not on current sales.
That gap between perception and fundamentals explains the stock’s wild year. Shares spiked toward $32 twice, in January and June. Each surge rode headlines about Chinese export controls and Washington’s push for domestic supply. Neither rally was tied to revenue.
As the headlines cooled, so did the stock. Patient investors bought the mission knowing the business would take years to build. Now that business is starting to take shape.
Heavy Rare Earths Are the Real Asset
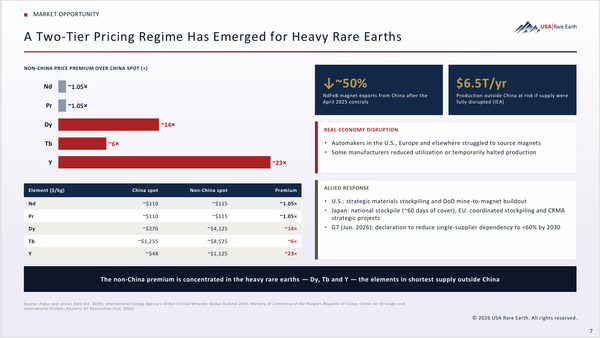
The strongest part of the bull case sits in a pricing slide. Outside China, light rare earths trade near Chinese prices. Neodymium and praseodymium carry only about a 5% premium. Heavy rare earths tell a very different story.
Citing Argus data from late October, the company puts non-China dysprosium near $4,125 per kilogram. That compares with about $270 inside China, roughly a 14-fold premium. Terbium carries about a 6x premium, and yttrium about 23x. Management says Serra Verde is the only meaningful heavy rare earth producer outside Asia.
Serra Verde’s offtake adds a safety net. Floor prices sit at $110/kg for NdPr, $575/kg for dysprosium and $2,050/kg for terbium. Those floors rise 2% each January. Serra Verde also keeps 70% of any market price above the floors, less separation costs.
USA Rare Earth’s Q4 Results Could Change the Narrative
Management expects to sell 325 tonnes of total rare earth oxide (TREO) from Serra Verde in Q4. It pegs the average basket value at about $43/kg at floor prices. At market prices, that rises to about $97/kg.
Simple math frames the opportunity. At floor prices, 325 tonnes implies roughly $14 million in Q4 sales. At market prices, the figure nears $32 million. Realized revenue should land in between, given the 70% sharing and separation costs. This is a rough estimate, not company guidance. Even the low end would nearly match the $14.5 million booked through nine months.
High Costs and Legacy Contracts Will Delay Profitability
Profits will take time, which long-term holders already expect. The Less Common Metals (LCM) unit in the U.K. is on track to lift 2026 volumes nearly 90%. However, it is still delivering on legacy contracts at lower prices and margins. Those run through Q2 2027, when repricing takes effect.
Spending is heavy, too. Capital expenditures and equipment deposits totaled $190.9 million through September. Projects include a second Stillwater line, a 6,400-tpa magnet plant in South Carolina and a metals plant in France.
The Cash Cushion Comes With Conditions
The $1.2 billion figure includes restricted cash. Management also cites more than $3.3 billion in committed and proposed government support. The fine print matters. A $500 million revolver is an unfunded commitment letter. Some grants remain subject to negotiation or final approval. Commerce Department funds depend on hitting milestones.
Serra Verde also brings debt with restrictive covenants. The company warns those terms could limit access to cash within its own structure. Its risk factors also flag potential dilution from future equity raises.
USA Rare Earth’s 2027 Milestones Will Test Execution
Investors need to watch whether the milestones turn into revenue through 2027. Management’s own timeline offers a scorecard:
- By year-end 2026: Finished magnet sales to multiple Stillwater customers
- Q1 2027: Serra Verde S-K 1300 technical report
- Q2 2027: Stillwater Line 1b doubles magnet capacity to 1,200 tpa; Serra Verde hits a 4,000-tpa run rate
- Q3 2027: Round Top S-K 1300 report; Serra Verde Stage 2 commissioning begins
- By year-end 2027: Serra Verde reaches a 6,400-tpa run rate
Commercial demand looks real but unproven. The company reports about 2,500 tonnes of signed magnet LOIs and MOUs. Round Top has seven MOUs covering more than 1,300 tpa. All are non-binding. Converting them into purchase orders is the test that matters.
USAR Stock Still Needs to Prove It Has Found a Bottom
The technical picture remains weak. Monday’s close left the MACD line just above its signal line. Tuesday’s drop likely erases that tentative crossover. Both lines sit well below zero, a sign sellers still control the trend. The 200-day moving average is rolling over near $18.55.
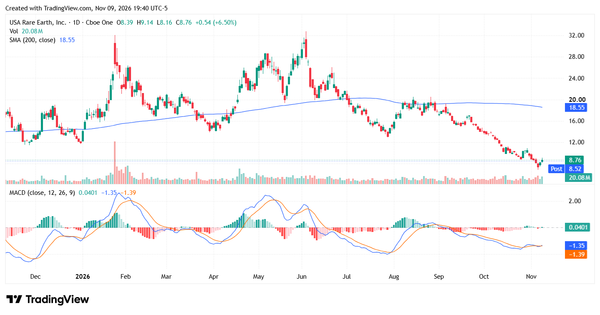
A durable recovery would need higher highs, ideally on rising volume. Until then, the USAR stock chart favors patient accumulation over bottom-fishing.
The Investment Thesis Now Depends on Execution
USA Rare Earth’s Q3 report won’t silence the skeptics. Revenue missed, gross margin was negative, and GAAP profit relied on an accounting gain. Tuesday’s slide shows short-term holders heading for the exits.
Perception has swung from strategic champion to cash burner. Yet the assets are now producing, and management says non-China heavy rare earth prices sit at record highs. For patient investors, that gap between perception and progress is the opportunity. Q4 revenue will show which view the fundamentals support.

