ajax loader

Loading...


Ride-the-Wave Strategy – Best for Stock Traders

Ride-the-Wave targets multi-day price momentum following a company’s earnings announcement (EA). With this strategy:

  1. Buy a stock one day post-EA if a stock reacts positively post-earnings:
    1. Near the close of trading the EA-day for a pre-market-EA
    2. Near the close of the following day for a post-market-EA
  2. Sell-to-close after 7-10 days, or possibly earlier if a desired price target is reached

Similarly,

  1. short a stock one day post-EA if a stock reacts negatively post-earnings:
    1. near the close of trading the EA-day for a premarket-EA
    2. near the close of the following day for a post-market-EA
  2. then buy-to-close after 7-10 days, or possibly earlier if a desired price target is reached

Important: Ride-the-Wave is predicated on significant price momentum triggered by an EA. The 7-10 day scenario is the maximum trade hold-time. If you see post EA-momentum is halted or reversed by a significant opposite move, re-evaluate your presence in the trade.

This popular StockEarnings screen below will give you a list of stocks that historically exhibit significant price momentum following an EA for the next seven days:

  1. Stocks exhibiting positive post-EA price moves are buy-candidates
  2. Stocks exhibiting negative post-EA price moves are sell/short-candidates

The screen includes those stocks whose Earnings just came out in last two days.

Screen criteria:

  1. Earnings Date Start Date : Current Date + -1 Day
  2. Earnings Date End Date : Current Date + -2 Days
  3. Predicted Move (Next Day) Max : 7%
  4. Predicted Move (On 7th Day) Min : 7%

Strategy Guideline:

  1. Buy the stock if stock has reacted positively. Short the stock if stock has reacted negatively (see above).
  2. Close the position in 7-10 days, or possibly earlier based on price move.

Volatility Crush Strategy - Best for Options Traders

The Volatility Crush strategy is used with stocks that typically experience relatively low-to-moderate price moves (≤4%) following their Earnings Announcements (EA). The basic trade idea is to sell put or call options right before the EA, collecting a credit when options premium is very high due to elevated implied volatility (IV). You then close the position right after the EA by buying the option back much cheaper due to the significant drop in IV that occurs after the mystery of the EA disappears. In assessing this trade, you need to do your homework to ensure you collect sufficient premium to make the trade worthwhile.

This trade is practical due to the low-to-moderate price-move after the EA, which generally won’t significantly affect the options price, unlike an “action” stock, which experience great price moves post-EA. With these symbols, if you’re on the right side of the price move, that’s a great thing. But if you’re on the wrong side of the move, not so great. Consequently, by minimizing the effect of the post-EA price move, you have a much better chance to profit from the reduction in IV without it being ruined by a violent price move.

For this trade, open the position either (1) the night before the EA when the company announces earnings or (2) during the EA day when it announces post-market, generally capturing IV at or close to its peak.

For this trade, open the position either (1) the night before the EA when the company announces earnings or (2) during the EA day when it announces post-market, generally capturing IV at or close to its peak.

This popular stockearnings screen will give you a list of stocks which do not react more than 4% fpost-EA. It includes only those stocks whose earnings are releasing next day.

Screen criteria:

  1. Earnings Date Start Date : Current Date + 1
  2. Earnings Date End Date : Current Date + 1
  3. Predicted Move (Next Day) Max : 4%
  4. Options Type: Weekly

Strategy Guideline:

  1. Options Strategy: Sell Call and Put
  2. Options Strike Price: Current Stock Price – (% Predicated Move x 2)
  3. Expiration Date: It should generally be the closest expiry immediately after the EA.
  4. Buy Insurance: Buying back Call and Put at Strike price which 10% lower than Sell Strike Price is optional but recommended.

Watch Video for More Detail

Volatility Rush Strategy - Best for Options Traders

The Volatility Rush takes advantage of increasing options premiums into earnings announcements (EA) caused by an anticipated rise in Implied Volatility (IV). With this strategy, Buy a Call and Put at-the-money (a long straddle) 2-3 weeks before the EA when IV is lower. Sell the position either (1) the night before the EA when the company announces earnings pre-market, or (2) during the EA day when it announces post-market, generally capturing IV at or close to its peak.

This popular screen will give you a list of stocks whose Options premiums tend to rise into Earnings. It includes only those stocks whose Earnings are at least two weeks away from today.

Screen criteria:

  1. Earnings Date Start Date : Current Date + 15 Days
  2. Earnings Date End Date : Current Date + 30 Days
  3. Predicted Move (Next Day) Min : 5%
  4. Options Type: Weekly or Monthly if that lines up with the two to three-week lead-time for entering the trade

Strategy Guideline:

  1. Buy a Straddle at or close to the money two to three weeks pre-EA.
  2. Sell the position either the night before the EA when the company announces earnings pre-market, or during the EA day when it announces post-market.
  3. Expiration date should generally be the closest expiry immediately after the EA.
  4. Straddle price should not be more 60% of predicted move.

Predicted Move (Volatility)

Similar to Implied Volatility in Options. Expected volatility % based on our Proprietary Volatility Predication Model. We are expecting that stock price will likely to reach % in either direction by the end of next trading session after Earnings are released and not necessarily the closing volatility %.

Why is it important?

    This indicator helps

  1. Knowing expected volatility in stocks after Earnings helps to decide trading stocks before Earnings Announcement.
  2. Taking Advantage of volatility collapse following Earnings Results by using Advance Options strategies such as Spread and Straddles.

Since Last Earnings

Change in share price since last Earnings release.

Why is it Important?

When share has gained more than 10% since it's last Earning release, it tends to over react to minor bad news and give up some gains if not all. So, it contains more downside volatility than upside When share has dropped more than 10% since it's last Earning release, it tends to over react to minor good news and recover some drops if not all. So, it contains more upside volatility than downside.

EPS Surprise (%)

Occurs when a company's reported quarterly or annual profits are above or below analysts' expectations. Here is the formula to derive % EPS Surprice:

Actual EPS - Estimated EPS
------------------------------------- x 100
Estimated EPS

Why is it Important?

Earnings surprises can have a huge impact on a company's stock price. Several studies suggest that positive earnings surprises not only lead to an immediate hike in a stock's price, but also to a gradual increase over time. Hence, it's not surprising that some companies are known for routinely beating earning projections. A negative earnings surprise will usually result in a decline in share price.

Next Day Price Change (%)

Next Regular trading session Closing price following Earnings result.

For After Market Close Earnings, It is a next trading day closing price. For Before Market Open Earnings, It is the same trading day closing price.

Why is it Important?

Next Day price change is a reaction of Earnings result.

Is a Post-Earnings Dutch Bros (BROS) Stock Option Worth Your Time?

Posted on Nov 10, 2026 by Joshua Enomoto

Is a Post-Earnings Dutch Bros (BROS) Stock Option Worth Your Time?

If options traders’ main objective were simply to place a binary wager on Dutch Bros (NYSE: BROS) — essentially that BROS stock would rise higher against the current spot price — the trade would arguably be an incredibly straightforward one. We’re not talking about a complicated business model here. The company provides delectable, drive-thru coffee and similar pick-me-up beverages.

In a hectic world, we can all use a little caffeine boost. And because Dutch Bros enjoys a brand name that resonates with its core (and growing) customers, the idea that BROS stock will move higher isn’t far-fetched in the least. But it’s also an expected outcome, which means we shouldn’t expect to be rewarded that handsomely for an obvious idea.

Plus, the options market isn’t exactly a philanthropic enterprise. It wants to take your money. Your job, then, is to limit the number of variables to the point where you’re mathematically comfortable in taking the risk.

Let’s start with what we know. Fundamentally, Dutch Bros stock has found itself struggling, most recently due to concerns related to the underlying company’s third-quarter earnings report (released on Nov. 4). Per Google Finance’s summary sheet, while the drive-thru barista slightly beat revenue expectations, it fell short on earnings per share. Perhaps more importantly, macroeconomic headwinds dragged on customer growth, contributing to a sharp selloff post-disclosure.

Technically, much damage has been done to the charts, with BROS stock suffering a loss of 11.25% in the trailing month. On a year-to-date basis, the ticker is down nearly 45%. It goes without saying that smart money traders have clear incentives to hedge against further downside volatility.

There’s a wrinkle to this narrative, however, and that’s the theory of mean reversion. Generally, contrarians are going to look for a reversal of fortunes when sentiment is currently weighted heavily on one side. Because the business is simple and relevant, such reversion may be plausibly applied to Dutch Bros stock.

Mean Reversion Isn’t Just a Random Idea for BROS Stock


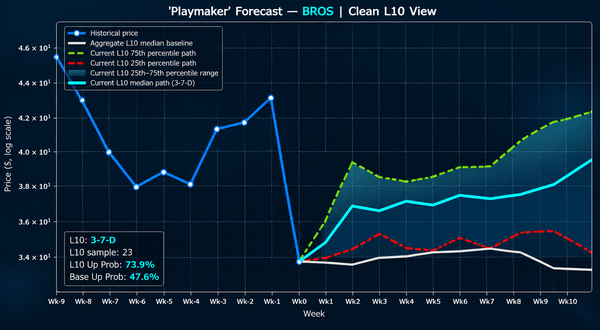
We have one more fact that we must consider before we get into the speculative lane. For Dutch Bros stock, mean reversion isn’t just a hot take: there are data points that back the theory. We know that when the tally of positive weekly candlesticks greatly outnumbers negative candlesticks over a rolling 10-week period, a tendency exists for BROS to rise higher than the random aggregate 10-week performance would suggest.

Why is that the case? It would appear that equities trading resembles Markov chain axiomatic transitions, where the probability of transition to a future state depends on the current state. In this case, BROS stock is structured in a deeply negative state, one where it has printed only three up weeks over the last 10 weeks. Statistically, the appearance of this negative state leads to an outsized performance relative to the random baseline expectation for BROS.

In terms of raw numbers, over the next 10 weeks, it’s possible that BROS stock can gradually rise toward a median endpoint price of around $40. The problem, though, is the compounded volatility. Currently, BROS commands a 60-month beta of 1.97 — twice as volatile as the benchmark S&P 500.
bros stock - StockEarnings

So yes, statistically, if we were to extrapolate how the Markov transition from bearish-to-bullish states would look mathematically, the 37/40 bull call spread expiring Jan. 15 would seem quite attractive. With only a $90 net debit at risk, you’d be anticipating that Dutch Bros stock can trigger the $40 strike on expiration. The probability would be estimated at 47.8%.

Now, we have to be super-careful here with specific ratios like 47.8%. That’s an empirical but naïve observation, which assumes that the environment in which BROS stock would be trading under is relatively static. However, if highly dynamic or variable events were to materialize over this 10-week period beyond what is historically observed for BROS, the inference could be way off.

Stated differently, the January monthly trade would reduce time-to-expiration risk but at the expense of much higher event risk.

Dutch Bros Stock Isn’t Limited to Just One Pathway

If you don’t like the idea of excessive event risk, you could go the other way; that is, you can lower the strike price target that BROS stock must exceed but trim the time to expiration. Here, I’m going to highlight the incredibly speculative (but mathematically rational) 35/37 bull call spread expiring Nov. 20.

As you might notice off the bat, it’s crazy risky. You only have two weeks until this bad boy expires. But on the positive side, the overall stats make this idea plausibly feasible. Basically, you’re betting a net debit of $75 in the hopes that Dutch Bros stock triggers the much friendlier $37 strike on expiration. If it does, you’re looking at a maximum payout of roughly 167%.

Admittedly, from an expected value (EV) perspective, you’re not looking at the most sterling trade. However, the expectancy is in positive territory: $3.20 in the black or a return on capital of +4.27%. Yes, you might be tempted to stretch the expiration date to Dec. 18. Unfortunately, with the way the options are currently priced, the December monthly forces you to take a higher event risk than what I would consider to be justified.

Of course, the obvious problem with the November monthly is that time risk may be far too high for conservative traders. But if you’re dead-set on Dutch Bros stock, there doesn’t seem to be much mathematical wiggle room.

If positive expectancy with reasonable fundamental probability is your gold standard, then it appears you have two choices: go with a short-term wager or a longer-term bet.

Concluding Analysis

Ultimately, none of the inferences made in the above analysis can be guaranteed. Indeed, the reason why these “cheap” debit spreads offer relatively robust payouts is because of the inherent uncertainty involved. That said, we do know that BROS stock enjoys a historical tendency for mean reversion, which is potentially positive news for contrarians.

However, the big unknown — beyond whether the stock will actually move higher over these next few weeks — is the size and scale of the inference. The options market forces you to make a specific wager, and if you’re off by a little bit, that could be the difference between winning and losing.

Honestly, the best we can do is to narrow down the variables. By performing this exercise, we at least have some confidence that there are likely only two mathematically rational approaches: a tight, near-term wager or a loose, long-term wager.


Joshua Enomoto is a seasoned financial writer with a strong track record of in-depth stock analysis, offering clear, insightful commentary for retail investors across all levels of expertise. Renowned for his ability to blend analytical rigor with engaging wit, Joshua's work has been featured on leading investment platforms, including TipRanks, InvestorPlace, Barchart, Benzinga, and Fintel. He was also handpicked to spearhead high-impact initiatives such as InvestorPlace's "Trade of the Day" and Benzinga’s ETF coverage. As a frequent guest expert for CGTN America, Joshua discusses a wide range of economic, societal, and consumer market trends. A graduate of U.C. San Diego, Joshua brings a thoughtful and fresh perspective to complex financial narratives, helping enterprise clients connect with their audiences. He also composes music in his spare time.

Join over 1.2M+ investors/traders who receive daily and weekly notable earnings alerts with predicted move