The holiday season is one of the most important times for consumer-facing stocks. That’s sure to be the case in 2026, when affordability is top of mind. As consumers look for bargains, investors are also looking for undervalued stocks that offer a measure of safety from the AI trade.
One area to look for undervalued stocks is the consumer discretionary sector. While the broader sector continues to be under pressure, there have been a few stocks that have bucked the trend. Many of these names don’t get analyzed by the financial press. But each could get a lift from holiday sales.
The Curious Case of the K-Shaped Consumer
This will be known as the year when the “K-shaped economy” became part of our investing lexicon. Through the first nine months of the year, companies have confirmed what that description implies. That is, the higher-income consumers on the upper leg of the “K” are doing the majority of the spending.
But that minority is still finding a way. Credit card delinquencies remain low even as interest rates are rising, which may limit credit availability for lower-income consumers. While these consumers may be cutting out some discretionary purchases, they are responding to retailers who offer value.
That will be on full display during this holiday season, which is a time that usually proves why it’s never wise to be against the American consumer. Investors should read that again and then consider these four undervalued stocks.
Bath & Body Works: Affordable Indulgence at a Bargain Price
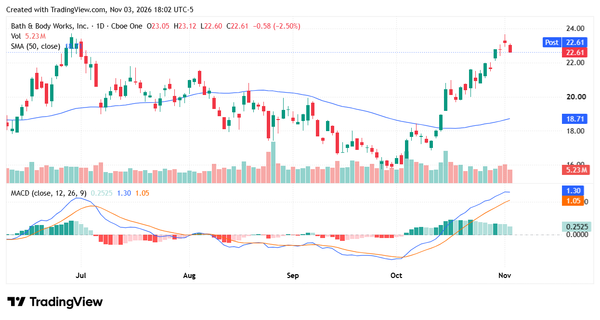
Bath & Body Works (NYSE: BBWI) checks two boxes for the holiday season. Its products are small, giftable, and priced for budget-minded shoppers. A candle or body mist makes an easy stocking stuffer. That matters in a year when consumers are hunting for value.
BBWI stock checks the value box, too. Shares trade at roughly 6x trailing earnings. That is well below the stock’s 10-year average multiple of about 11x. Investors also collect a quarterly dividend of 20 cents per share.
Still, this is a turnaround story. Net sales fell 2.3% in the second quarter. Management expects full-year sales to decline 2.5% to 4%. However, the company beat its own guidance and raised its full-year EPS outlook. Part of that beat came from roughly $80 million in tariff refunds. More encouraging, direct sales grew for the first time since 2021.
Investors noticed. The stock gained about 43% in October alone. The upcoming third-quarter report will show whether that optimism is justified heading into the holidays.
Crocs: Earnings Confirm the Demand Story
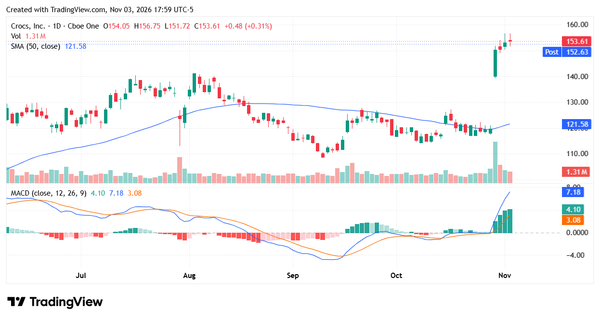
Crocs (NASDAQ: CROX) gave investors an early read on holiday demand on October 29. Third-quarter revenue rose 4.6% to $1.04 billion, topping estimates. Adjusted EPS of $3.69 beat the consensus by more than 11%. The Crocs brand posted a record third quarter, led by double-digit international growth.
The bigger story may be HEYDUDE. That brand returned to growth with revenue up 6.1%. HEYDUDE had been the main knock on the stock. Management now expects fourth-quarter revenue to rise 7% to 9%. It also raised full-year guidance for the third time this year.
Shares jumped about 19% on the news. Yet even after that move, Crocs trades below 10x its new full-year EPS guidance of $14.45 to $14.65. The company is also returning cash to shareholders. It bought back $250 million in stock during the quarter.
Mattel: Kidults Are Filling the Toy Box
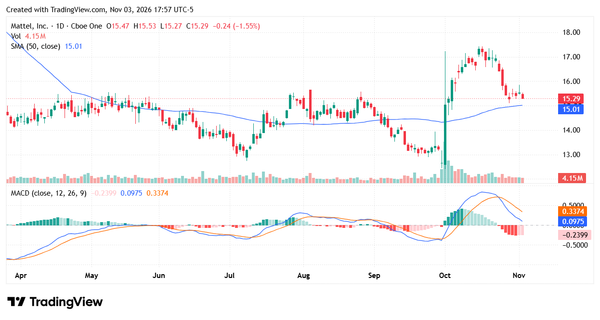
Mattel (NASDAQ: MAT) is positioned for one of the most durable trends in consumer spending. Adults are buying toys for themselves. Circana reports U.S. toy sales jumped 17% in the first half of 2026. Sales to adults rose 25%, making them the largest driver of that growth.
Mattel’s portfolio fits that buyer. Hot Wheels, Barbie, and Masters of the Universe all carry deep nostalgia. The Mattel Creations platform targets collectors with premium, limited releases. Second-quarter net sales grew 10%, with management citing adult collectors as a key contributor.
However, investors should know the story has changed. CEO Ynon Kreiz stepped down on October 1. Reports of takeover interest from Authentic Brands Group sent shares sharply higher. A major shareholder has also urged the board to pursue a strategic review.
That gives investors two ways to win. Holiday sales could support the fundamentals. A deal could unlock value outright. Shares trade near 11x trailing earnings and are down more than 20% this year. Investors will learn more when Mattel reports third-quarter results on November 5.
Signet Jewelers: Romance Works in Any Economy
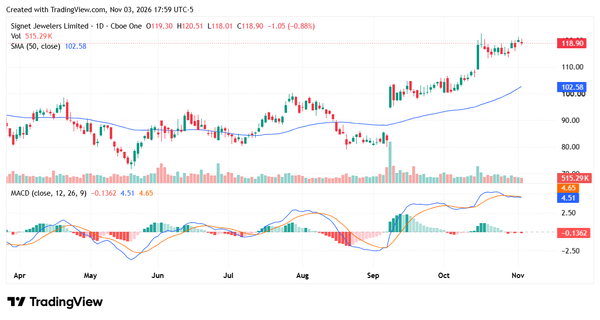
Signet Jewelers (NYSE: SIG) owns Kay, Zales, and Jared. The holiday season is its most important quarter. Engagements, anniversaries, and gifts tend to hold up even when budgets get tight. Signet also serves shoppers across income levels, which matters in a K-shaped economy.
The second quarter backed that up. Same-store sales rose 2.2%, and adjusted EPS jumped 36% to $2.19. Management raised full-year adjusted EPS guidance to $10.45 to $12.15. At the midpoint, shares trade near 10x forward earnings.
Gold is a double-edged sword for Signet. Prices above $4,000 an ounce raise input costs. But they also lift average selling prices, which rose about 6% last quarter. Signet has accelerated scrap gold recovery to capture those higher prices. It has also expanded lab-grown diamond fashion pieces under $1,000, giving value-conscious shoppers an affordable option.
SIG stock is already up more than 40% this year. But a forward multiple near 10x suggests the rally rests on earnings, not hype.
The Bottom Line on These Undervalued Stocks
None of these stocks is without risk. Bath & Body Works is still shrinking its top line. Mattel faces leadership uncertainty. Crocs and Signet have already rallied. But each trades at a modest earnings multiple, and each has a clear holiday catalyst. For investors seeking undervalued stocks outside the AI trade, that combination deserves a closer look.