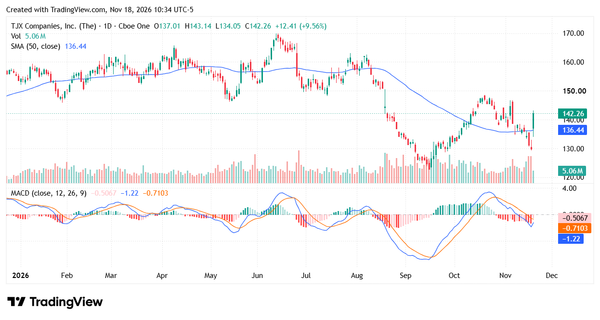
TJX (NYSE: TJX) gave investors a reason to get more optimistic heading into the holidays. The parent of TJ Maxx, Marshalls and HomeGoods reported better-than-expected third-quarter sales and lifted its full-year comparable-sales forecast to the top of its previous range.
HomeGoods and the international businesses posted strong gains, and management expects further improvement at Marmaxx, the U.S. division that includes TJ Maxx and Marshalls. That’s the part of the business worth watching most closely as holiday shopping picks up.
TJX Earnings Beat Expectations as International Sales Lead Growth
TJX brought in $15.95 billion in revenue for the fiscal third quarter ended October 31, up 5.5% from a year earlier. That was roughly $110 million above the $15.84 billion analysts expected. Comparable sales, which track sales across an established base of stores, rose 4% and were just above the 3.8% estimate.
The company’s strongest comparable-sales gains came from TJX International, which includes Europe and Australia. Sales there jumped 8%, followed by a 6% increase in Canada and a 5% gain at HomeGoods. Marmaxx grew 2% after rising 6% in the same quarter last year.
That 2% gain looks more meaningful when you consider how much business Marmaxx does. The division generated $9.33 billion in quarterly revenue, nearly 59% of the company’s total. A pickup at TJ Maxx and Marshalls can therefore make a bigger difference to the overall business than faster percentage growth in a smaller division. CEO Ernie Herrman expects Marmaxx to improve further in the fourth quarter.
Tariff Refunds Helped Earnings While Shipping Costs Jumped
The company earned $1.39 per diluted share, up from $1.28 a year earlier. Tariff refunds added a net five cents per share. Excluding that benefit, adjusted earnings came in at $1.34, up about 5% and in line with Wall Street’s estimate.
The refunds also helped lift reported gross margin to 32.9% from 32.6% a year earlier. Gross margin measures how much of each sales dollar a retailer keeps after covering the direct costs of the goods it sells. Strip out the refund benefit, and the margin falls to 32.1%, half a percentage point below the year-ago figure. TJX pointed to higher freight and fuel costs.
For investors, that matters heading into the busiest shopping season. Extra sales give TJX more dollars to work with, but higher shipping costs can eat into what the company earns on each sale. If those costs remain elevated during the holidays, an encouraging sales number could still come with a tighter margin.
TJX Is Opening Stores and Buying Back Stock
TJX generated $1.7 billion in operating cash flow during the quarter and ended it with $4.6 billion in cash. It returned $1.5 billion to shareholders through dividends and share repurchases and now expects to buy back about $3 billion of its stock in fiscal 2027.
The retailer also added a net 64 stores during the quarter, bringing its total to 5,349. That expansion gives TJX another source of revenue growth alongside higher sales from its existing stores. It also makes comparable sales worth following. The measure helps investors see whether established locations are bringing in more business as the company adds new ones.
Holiday Sales Will Test Management’s Optimism
TJX now expects comparable sales to rise 4% for the full fiscal year, up from its previous forecast of 3% to 4% growth. Its full-year earnings outlook of $5.17 to $5.20 per share still sits below the $5.23 consensus.
For the holiday quarter itself, TJX expects comparable sales to rise 2% to 3%.
Herrman said unusually warm weather in the U.S. and Canada held back demand in some categories. He expects sales to gain momentum as the holidays progress. TJX plans to bring fresh merchandise into stores and add products online several times a week, giving shoppers who still have gifts to buy a reason to check back.
That changing assortment is a big part of the appeal. A shopper who comes in for a gift may find something else worth picking up, and a shopper who leaves empty-handed may have a reason to return. During the holidays, when people are buying for several people at once, those extra visits can add up.
The third quarter showed that TJX can grow across several businesses at once. The holiday quarter will show whether its biggest U.S. division can pick up the pace and whether those extra sales translate into stronger profits. After Wednesday’s rally, that combination would give investors a firmer reason to expect better earnings ahead.