ajax loader

Loading...


Ride-the-Wave Strategy – Best for Stock Traders

Ride-the-Wave targets multi-day price momentum following a company’s earnings announcement (EA). With this strategy:

  1. Buy a stock one day post-EA if a stock reacts positively post-earnings:
    1. Near the close of trading the EA-day for a pre-market-EA
    2. Near the close of the following day for a post-market-EA
  2. Sell-to-close after 7-10 days, or possibly earlier if a desired price target is reached

Similarly,

  1. short a stock one day post-EA if a stock reacts negatively post-earnings:
    1. near the close of trading the EA-day for a premarket-EA
    2. near the close of the following day for a post-market-EA
  2. then buy-to-close after 7-10 days, or possibly earlier if a desired price target is reached

Important: Ride-the-Wave is predicated on significant price momentum triggered by an EA. The 7-10 day scenario is the maximum trade hold-time. If you see post EA-momentum is halted or reversed by a significant opposite move, re-evaluate your presence in the trade.

This popular StockEarnings screen below will give you a list of stocks that historically exhibit significant price momentum following an EA for the next seven days:

  1. Stocks exhibiting positive post-EA price moves are buy-candidates
  2. Stocks exhibiting negative post-EA price moves are sell/short-candidates

The screen includes those stocks whose Earnings just came out in last two days.

Screen criteria:

  1. Earnings Date Start Date : Current Date + -1 Day
  2. Earnings Date End Date : Current Date + -2 Days
  3. Predicted Move (Next Day) Max : 7%
  4. Predicted Move (On 7th Day) Min : 7%

Strategy Guideline:

  1. Buy the stock if stock has reacted positively. Short the stock if stock has reacted negatively (see above).
  2. Close the position in 7-10 days, or possibly earlier based on price move.

Volatility Crush Strategy - Best for Options Traders

The Volatility Crush strategy is used with stocks that typically experience relatively low-to-moderate price moves (≤4%) following their Earnings Announcements (EA). The basic trade idea is to sell put or call options right before the EA, collecting a credit when options premium is very high due to elevated implied volatility (IV). You then close the position right after the EA by buying the option back much cheaper due to the significant drop in IV that occurs after the mystery of the EA disappears. In assessing this trade, you need to do your homework to ensure you collect sufficient premium to make the trade worthwhile.

This trade is practical due to the low-to-moderate price-move after the EA, which generally won’t significantly affect the options price, unlike an “action” stock, which experience great price moves post-EA. With these symbols, if you’re on the right side of the price move, that’s a great thing. But if you’re on the wrong side of the move, not so great. Consequently, by minimizing the effect of the post-EA price move, you have a much better chance to profit from the reduction in IV without it being ruined by a violent price move.

For this trade, open the position either (1) the night before the EA when the company announces earnings or (2) during the EA day when it announces post-market, generally capturing IV at or close to its peak.

For this trade, open the position either (1) the night before the EA when the company announces earnings or (2) during the EA day when it announces post-market, generally capturing IV at or close to its peak.

This popular stockearnings screen will give you a list of stocks which do not react more than 4% fpost-EA. It includes only those stocks whose earnings are releasing next day.

Screen criteria:

  1. Earnings Date Start Date : Current Date + 1
  2. Earnings Date End Date : Current Date + 1
  3. Predicted Move (Next Day) Max : 4%
  4. Options Type: Weekly

Strategy Guideline:

  1. Options Strategy: Sell Call and Put
  2. Options Strike Price: Current Stock Price – (% Predicated Move x 2)
  3. Expiration Date: It should generally be the closest expiry immediately after the EA.
  4. Buy Insurance: Buying back Call and Put at Strike price which 10% lower than Sell Strike Price is optional but recommended.

Watch Video for More Detail

Volatility Rush Strategy - Best for Options Traders

The Volatility Rush takes advantage of increasing options premiums into earnings announcements (EA) caused by an anticipated rise in Implied Volatility (IV). With this strategy, Buy a Call and Put at-the-money (a long straddle) 2-3 weeks before the EA when IV is lower. Sell the position either (1) the night before the EA when the company announces earnings pre-market, or (2) during the EA day when it announces post-market, generally capturing IV at or close to its peak.

This popular screen will give you a list of stocks whose Options premiums tend to rise into Earnings. It includes only those stocks whose Earnings are at least two weeks away from today.

Screen criteria:

  1. Earnings Date Start Date : Current Date + 15 Days
  2. Earnings Date End Date : Current Date + 30 Days
  3. Predicted Move (Next Day) Min : 5%
  4. Options Type: Weekly or Monthly if that lines up with the two to three-week lead-time for entering the trade

Strategy Guideline:

  1. Buy a Straddle at or close to the money two to three weeks pre-EA.
  2. Sell the position either the night before the EA when the company announces earnings pre-market, or during the EA day when it announces post-market.
  3. Expiration date should generally be the closest expiry immediately after the EA.
  4. Straddle price should not be more 60% of predicted move.

Predicted Move (Volatility)

Similar to Implied Volatility in Options. Expected volatility % based on our Proprietary Volatility Predication Model. We are expecting that stock price will likely to reach % in either direction by the end of next trading session after Earnings are released and not necessarily the closing volatility %.

Why is it important?

    This indicator helps

  1. Knowing expected volatility in stocks after Earnings helps to decide trading stocks before Earnings Announcement.
  2. Taking Advantage of volatility collapse following Earnings Results by using Advance Options strategies such as Spread and Straddles.

Since Last Earnings

Change in share price since last Earnings release.

Why is it Important?

When share has gained more than 10% since it's last Earning release, it tends to over react to minor bad news and give up some gains if not all. So, it contains more downside volatility than upside When share has dropped more than 10% since it's last Earning release, it tends to over react to minor good news and recover some drops if not all. So, it contains more upside volatility than downside.

EPS Surprise (%)

Occurs when a company's reported quarterly or annual profits are above or below analysts' expectations. Here is the formula to derive % EPS Surprice:

Actual EPS - Estimated EPS
------------------------------------- x 100
Estimated EPS

Why is it Important?

Earnings surprises can have a huge impact on a company's stock price. Several studies suggest that positive earnings surprises not only lead to an immediate hike in a stock's price, but also to a gradual increase over time. Hence, it's not surprising that some companies are known for routinely beating earning projections. A negative earnings surprise will usually result in a decline in share price.

Next Day Price Change (%)

Next Regular trading session Closing price following Earnings result.

For After Market Close Earnings, It is a next trading day closing price. For Before Market Open Earnings, It is the same trading day closing price.

Why is it Important?

Next Day price change is a reaction of Earnings result.

Royal Caribbean (RCL) Stock Offers an Intriguing Growth Trade

Posted on Sep 22, 2026 by Joshua Enomoto

Royal Caribbean (RCL) Stock Offers an Intriguing Growth Trade

Among large-capitalization companies, Royal Caribbean (NYSE: RCL) happens to be one of the worst performers over the trailing month on a percentage basis. Specifically, RCL stock has slipped 14.54% over the past 30 days (ending Sep. 18). At the same time, the cruise ship operator could be a possible candidate for a recovery trade.

Interestingly, out of the 200 worst large-cap losers on Friday, 49 of these deflated names flashed what I would call the “3-7-D sequence.” That is, in the last 10 weeks, only three of the weekly candlesticks were positive sessions, which naturally means that 70% of the defined period was dominated by net selling pressure. That’s an awfully bearish behavioral state that will likely have an impact on both the perception of RCL stock and its eventual forward trajectory.

However, I’m not presupposing that just because the 3-7-D sequence flashed, Royal Caribbean stock will move higher. That would be an example of affirming the consequent. Instead, I want to ask a deeper question. Of the 49 stocks that flashed this signal, how many of them actually saw a positive variance between the targeted outcome and the aggregate baseline performance?

Among the handful of names that actually popped to a sizable degree, RCL stock may be the most compelling. It’s not just about the statistical fact that RCL tends to move noticeably higher following the signal. Rather, the desired options strategy to potentially take advantage of the projected pricing discrepancy is asymmetrically favorable to the debit-side trader.
rcl - StockEarnings

In other words, speculators may be able to put down a relatively limited amount of money to generate a disproportionately large profit should circumstances pan out favorably for Royal Caribbean stock. While the trade itself may be risky, the juice could be worth the squeeze.

Presenting the Statistical Framework for RCL Stock


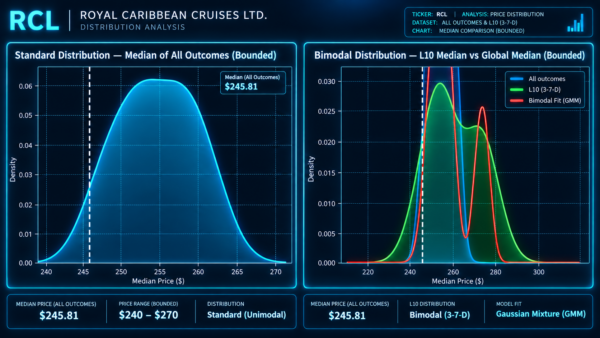
On average, when Royal Caribbean stock had flashed the 3-7-D sequence (on a rolling basis) going back to January 2019, the average outcome of RCL ranged between $220 and $300 over the next 10 weeks. In contrast, the average outcome as an aggregate of all histories of rolling 10-week sequences is a range between $240 and $270.

Basically, while the risk tail expands under the signal, the reward tail expands that much more. Subsequently, volatility-tolerant traders are incentivized — all other things being equal — to consider taking a shot on RCL stock.

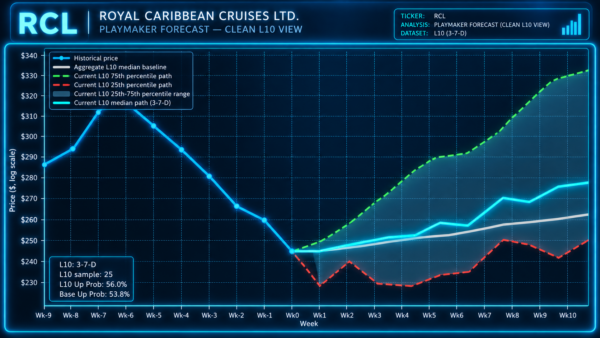
However, when we look at a week-by-week forecast, much of the bullishness is projected to materialize in the later weeks. Given that most of the strike-selection diversity is typically prevalent on monthly options chains, the ideal date to exploit a possible mispricing in RCL stock would be for the Nov. 20 expiration date. This target aligns with week 9 of the forecast.
rcl - StockEarnings

For that time period, the median terminal expectation is approximately a 12.3% move up. If so, that would put the 260/270 bull call spread expiring Nov. 20 in possible contention. Speculators would pay a net debit (cash outlay) of $390. Should Royal Caribbean stock trigger the $270 second-leg strike price on expiration, the maximum profit would be $610, a payout of over 156%.

On paper, this risk-reward asymmetry — risk $390 for the chance to gain $610 — is quite alluring. However, the odds of RCL stock actually triggering the necessary threshold in time are very modest.

Questioning the Presupposition Baked into Royal Caribbean Stock

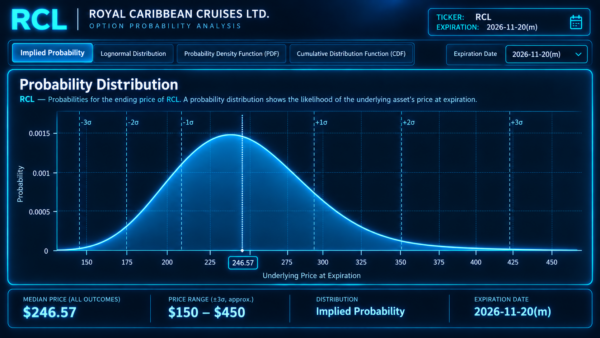
According to Wall Street’s options pricing mechanism, the probability of the 260/270 bull spread breaking even at a price of $263.90 (on Nov. 20) is defined at only 34.2%. Worse yet, OptionCharts’ Probability Distribution screener identifies the chance of RCL stock hitting $270 on expiration at only 28.31%.
rcl - StockEarnings

If you ran a quick expected-value calculation, you would realize the core dilemma. If you ran this identical trade over the theoretical long run, your portfolio will quickly sink as the number of losses outpaces the number of wins. If the statistical best outcome you can hope for is to break even at around 34%, this trade would simply not be worth pursuing.

However, the avoidance of this idea would largely center on acceptance of the presupposition that undergirded the above probabilities. What people often don’t realize is that any argument about the future is necessarily presuppositional. As such, it makes sense to consider the premise that most likely aligns with market reality.

For the RCL stock example above, the probabilities were derived from the Black-Scholes family of calculations. This system presupposes that RCL will undergo a random walk between now and the selected expiration date, with the current implied volatility serving as a risk-neutral constant across the journey.

One of the mathematical consequences of this framework is that the future is independent of the past; that is, it doesn’t matter the path that RCL stock took to get to the current (time-of-writing) price of $245.81. However, most of us believe in an entirely different presupposition — that the future is dependent on the past.

Path Dependency Undergirds Transitional Probabilistic Assumptions

While I can’t empirically prove it, I believe the case of path dependency is self-evident. Think about the path that Royal Caribbean stock took to get to nearly $246. As I mentioned earlier, RCL lost 14.54% in the trailing month. That’s going to change the perception of the cruise ship operator and where it may end up, as opposed to if RCL had enjoyed a 14.54% gain.
rcl - StockEarnings

In the latter case, there may be a risk that too much good news is baked in. With the former, it’s the opposite argument: too much bad news is baked in, which potentially increases the probability of a contrarian swing higher.

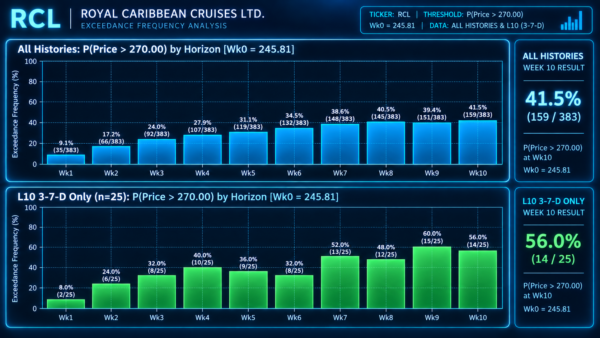
In fact, that’s what the data shows. Since January 2019, RCL stock has flashed the 3-7-D sequence a total of 25 times on a rolling basis. Of this figure, RCL has risen above the equivalent of the $270 strike price 15 times on week 9 (Nov. 20). That comes out to a hit ratio of 60%. To break even at $263.90, the probability comes out to 64%.

Granted, we are talking about small sample sizes, so that must be taken into account — we simply cannot generate true statistical confidence with this trade. However, there is reason to believe that under a path-dependent framework, the probabilities of upside for RCL stock are superior to those of a path-independent model.

Since I would make the argument that the future is likely dependent on the recent material past, it would seem that the 260/270 bull spread is conceptually mispriced.


Joshua Enomoto is a seasoned financial writer with a strong track record of in-depth stock analysis, offering clear, insightful commentary for retail investors across all levels of expertise. Renowned for his ability to blend analytical rigor with engaging wit, Joshua's work has been featured on leading investment platforms, including TipRanks, InvestorPlace, Barchart, Benzinga, and Fintel. He was also handpicked to spearhead high-impact initiatives such as InvestorPlace's "Trade of the Day" and Benzinga’s ETF coverage. As a frequent guest expert for CGTN America, Joshua discusses a wide range of economic, societal, and consumer market trends. A graduate of U.C. San Diego, Joshua brings a thoughtful and fresh perspective to complex financial narratives, helping enterprise clients connect with their audiences. He also composes music in his spare time.

Join over 1.2M+ investors/traders who receive daily and weekly notable earnings alerts with predicted move