You don’t need to search deeply to find a good reason to abandon MGM Resorts (NYSE: MGM) as the market has already done the heavy lifting. For those who aren’t aware, MGM stock suffered a severe 11% drawdown on Thursday, a result of a proposed deal being scrapped. That has naturally sent investors scrambling, reassessing the forward risk profile of the casino and resorts giant.
Specifically, billionaire Barry Diller’s company, People Inc. officially withdrew its unsolicited $48.30 per share acquisition proposal. Per Google Finance’s summary sheet, “[t]he removal of this takeover premium triggered immediate downward price pressure, removing a near-term valuation floor that had previously sustained investor optimism.”
In the interest of efficiency, I won’t waste time with tautologies about the market digesting the bad news or similar sentiments. Honestly, it would be a much more fascinating development if the market did not digest a hotly anticipated buyout but that’s just not how markets work.
Instead, whatever has been done by Diller or any other meaningful event has long been accounted for within the price discovery process of MGM Resorts stock. My opinion on the matter will simply contribute no substance to the matter at all.
So, why am I here? And why are you even reading these words? There’s a quantitative fact that the mainstream media has not reported, either because the ecosystem is not aware of it or perhaps that it’s deemed uninteresting.
If it’s the latter — and I have zero evidence of this, to be clear — then you might want to stick around. Because if you’re the gambling type, someone who has a few bucks lying around, you’re going to want to know this intriguing data point.
Is MGM Stock Total Junk? That’s What Investors Thought in the Past.
Thanks to the recent terrible news, MGM Resorts stock now finds itself in the red on a year-to-date basis, having lost roughly 8% through Thursday’s close. But prior to the meltdown, MGM was a winning hand. Obviously, a central thesis was anchored to the People Inc. proposal.
Fundamentally, though, that wasn’t the only catalyst supporting MGM stock. You do have strong core revenue and segment performances, strategic expansion opportunities (particularly in key international markets) and overall bullish consensus (though that could admittedly change following the latest disappointment).
The broader point, though, is that MGM Resorts stock isn’t a one-catalyst engine. It has other launch points of upside potential so just writing it off altogether may not be prudent.
Now, for the more intriguing component, MGM stock stands at an almost unprecedented juncture. In the last 10 weeks, the security only managed to print one net positive (weekly) candlestick. Stated differently, 90% of eligible sessions within the past two-month period suffered net negative outcomes. Naturally, the overall trend during this 10-week period (from opening price to closing price) has been negative.
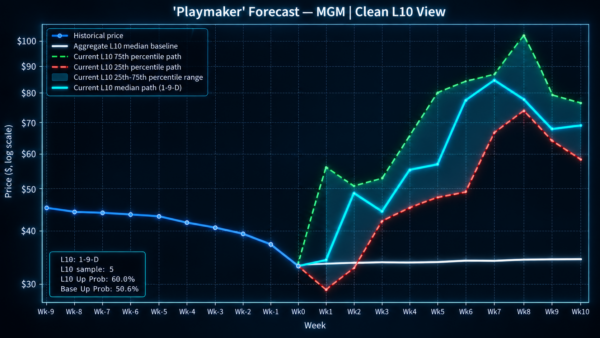
That in itself is observationally significant. Obviously, the market features both buyers and sellers. But the selling pressure in the last 10 weeks was so disjointed in the bears’ favor that the counterparty only managed one weekly session of net positive behavior.
From inductive inference, we can reasonably agree on two premises:
- The current overall perception of MGM stock is pessimistic (and deeply so).
- Because the sentiment is so poor, it will likely impact the forward trajectory of MGM stock.
From these premises, I conclude that we can exploit the difference between a standard expected outcome versus the outcome we would expect on the condition that MGM stock has suffered a severe drawdown.
Running the Calculations for MGM Resorts Stock
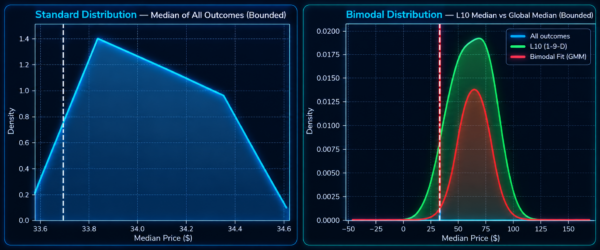
If we went back to January 2009 and collected (on a rolling basis) the performance stats of 10-week sequences, we would have 906 instances. With this data, we can then estimate where MGM stock is likely to land for a random 10-week long position — which is to say, not much higher from the starting point.
However, this calculation changes dramatically for the 1-9-D sequence: one up week, nine down weeks, downward slope. This particular behavioral state has only materialized five times in the last nearly two decades. On an independent basis, the 1-9-D may have only flashed twice.
Given the extremely small sample size, there’s no way that I can prepare a statistical case using empirical data. What I can say is that of the very few times that this sequence has materialized on the technical chart, MGM stock has historically enjoyed an explosive move higher.
If we were to take Thursday’s closing price of $33.69 as the starting point and project the inductive inference forward, we would be looking at a target of just shy of the $70 price level for the Nov. 20 expiration date. So, if you’re looking at all the bull call spreads that have maximum payouts of 500%, just know that they’re not entirely implausible.
Let’s pause here for a second. The argument that I’m making for MGM Resorts stock is NOT that history will repeat. Frankly, I don’t know if it will repeat — or even if it will rhyme. But if it does happen to repeat, then we do have limited precedent for such a swing.
It’s like a cataclysmic earthquake. What are the chances that you personally will encounter one? Depending on where you live, the chances may be quite small. But because we have seen earthquakes that practically broke the Richter scale, it’s not impossible to assume that such an event could materialize again.
Where Does That Leave Us?
As for what traders should do with the information above, it’s really up to you. It’s honestly a gamble. If you look at the Black-Scholes model, the chances of MGM stock hitting $60 on Nov. 20 is 0.01%. I want you to think about that. Under standard random-walk math, you have a 99.99% chance of being wrong.
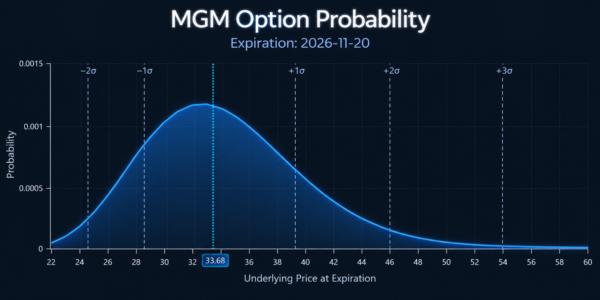
From a commonly accepted presupposition, by taking the gamble, you are effectively seeking a tax deduction.
My model doesn’t offer much of a counterargument. It’s just that historically, MGM stock tends to shoot back higher following extreme and extended bearishness. I’m not guaranteeing that history will repeat. But on the flipside, there’s no guarantee that it won’t happen either.
As of this writing, Joshua Enomoto is considering buying speculative out-the-money call options on MGM stock.