ajax loader

Loading...


Ride-the-Wave Strategy – Best for Stock Traders

Ride-the-Wave targets multi-day price momentum following a company’s earnings announcement (EA). With this strategy:

  1. Buy a stock one day post-EA if a stock reacts positively post-earnings:
    1. Near the close of trading the EA-day for a pre-market-EA
    2. Near the close of the following day for a post-market-EA
  2. Sell-to-close after 7-10 days, or possibly earlier if a desired price target is reached

Similarly,

  1. short a stock one day post-EA if a stock reacts negatively post-earnings:
    1. near the close of trading the EA-day for a premarket-EA
    2. near the close of the following day for a post-market-EA
  2. then buy-to-close after 7-10 days, or possibly earlier if a desired price target is reached

Important: Ride-the-Wave is predicated on significant price momentum triggered by an EA. The 7-10 day scenario is the maximum trade hold-time. If you see post EA-momentum is halted or reversed by a significant opposite move, re-evaluate your presence in the trade.

This popular StockEarnings screen below will give you a list of stocks that historically exhibit significant price momentum following an EA for the next seven days:

  1. Stocks exhibiting positive post-EA price moves are buy-candidates
  2. Stocks exhibiting negative post-EA price moves are sell/short-candidates

The screen includes those stocks whose Earnings just came out in last two days.

Screen criteria:

  1. Earnings Date Start Date : Current Date + -1 Day
  2. Earnings Date End Date : Current Date + -2 Days
  3. Predicted Move (Next Day) Max : 7%
  4. Predicted Move (On 7th Day) Min : 7%

Strategy Guideline:

  1. Buy the stock if stock has reacted positively. Short the stock if stock has reacted negatively (see above).
  2. Close the position in 7-10 days, or possibly earlier based on price move.

Volatility Crush Strategy - Best for Options Traders

The Volatility Crush strategy is used with stocks that typically experience relatively low-to-moderate price moves (≤4%) following their Earnings Announcements (EA). The basic trade idea is to sell put or call options right before the EA, collecting a credit when options premium is very high due to elevated implied volatility (IV). You then close the position right after the EA by buying the option back much cheaper due to the significant drop in IV that occurs after the mystery of the EA disappears. In assessing this trade, you need to do your homework to ensure you collect sufficient premium to make the trade worthwhile.

This trade is practical due to the low-to-moderate price-move after the EA, which generally won’t significantly affect the options price, unlike an “action” stock, which experience great price moves post-EA. With these symbols, if you’re on the right side of the price move, that’s a great thing. But if you’re on the wrong side of the move, not so great. Consequently, by minimizing the effect of the post-EA price move, you have a much better chance to profit from the reduction in IV without it being ruined by a violent price move.

For this trade, open the position either (1) the night before the EA when the company announces earnings or (2) during the EA day when it announces post-market, generally capturing IV at or close to its peak.

For this trade, open the position either (1) the night before the EA when the company announces earnings or (2) during the EA day when it announces post-market, generally capturing IV at or close to its peak.

This popular stockearnings screen will give you a list of stocks which do not react more than 4% fpost-EA. It includes only those stocks whose earnings are releasing next day.

Screen criteria:

  1. Earnings Date Start Date : Current Date + 1
  2. Earnings Date End Date : Current Date + 1
  3. Predicted Move (Next Day) Max : 4%
  4. Options Type: Weekly

Strategy Guideline:

  1. Options Strategy: Sell Call and Put
  2. Options Strike Price: Current Stock Price – (% Predicated Move x 2)
  3. Expiration Date: It should generally be the closest expiry immediately after the EA.
  4. Buy Insurance: Buying back Call and Put at Strike price which 10% lower than Sell Strike Price is optional but recommended.

Watch Video for More Detail

Volatility Rush Strategy - Best for Options Traders

The Volatility Rush takes advantage of increasing options premiums into earnings announcements (EA) caused by an anticipated rise in Implied Volatility (IV). With this strategy, Buy a Call and Put at-the-money (a long straddle) 2-3 weeks before the EA when IV is lower. Sell the position either (1) the night before the EA when the company announces earnings pre-market, or (2) during the EA day when it announces post-market, generally capturing IV at or close to its peak.

This popular screen will give you a list of stocks whose Options premiums tend to rise into Earnings. It includes only those stocks whose Earnings are at least two weeks away from today.

Screen criteria:

  1. Earnings Date Start Date : Current Date + 15 Days
  2. Earnings Date End Date : Current Date + 30 Days
  3. Predicted Move (Next Day) Min : 5%
  4. Options Type: Weekly or Monthly if that lines up with the two to three-week lead-time for entering the trade

Strategy Guideline:

  1. Buy a Straddle at or close to the money two to three weeks pre-EA.
  2. Sell the position either the night before the EA when the company announces earnings pre-market, or during the EA day when it announces post-market.
  3. Expiration date should generally be the closest expiry immediately after the EA.
  4. Straddle price should not be more 60% of predicted move.

Predicted Move (Volatility)

Similar to Implied Volatility in Options. Expected volatility % based on our Proprietary Volatility Predication Model. We are expecting that stock price will likely to reach % in either direction by the end of next trading session after Earnings are released and not necessarily the closing volatility %.

Why is it important?

    This indicator helps

  1. Knowing expected volatility in stocks after Earnings helps to decide trading stocks before Earnings Announcement.
  2. Taking Advantage of volatility collapse following Earnings Results by using Advance Options strategies such as Spread and Straddles.

Since Last Earnings

Change in share price since last Earnings release.

Why is it Important?

When share has gained more than 10% since it's last Earning release, it tends to over react to minor bad news and give up some gains if not all. So, it contains more downside volatility than upside When share has dropped more than 10% since it's last Earning release, it tends to over react to minor good news and recover some drops if not all. So, it contains more upside volatility than downside.

EPS Surprise (%)

Occurs when a company's reported quarterly or annual profits are above or below analysts' expectations. Here is the formula to derive % EPS Surprice:

Actual EPS - Estimated EPS
------------------------------------- x 100
Estimated EPS

Why is it Important?

Earnings surprises can have a huge impact on a company's stock price. Several studies suggest that positive earnings surprises not only lead to an immediate hike in a stock's price, but also to a gradual increase over time. Hence, it's not surprising that some companies are known for routinely beating earning projections. A negative earnings surprise will usually result in a decline in share price.

Next Day Price Change (%)

Next Regular trading session Closing price following Earnings result.

For After Market Close Earnings, It is a next trading day closing price. For Before Market Open Earnings, It is the same trading day closing price.

Why is it Important?

Next Day price change is a reaction of Earnings result.

Dave & Buster’s (PLAY) Q2 Earnings Show a Turnaround I’m Still Not Buying

Posted on Sep 15, 2026 by Grayson Cavern

Dave & Buster’s (PLAY) Q2 Earnings Show a Turnaround I’m Still Not Buying

Dave & Buster’s Entertainment Inc (NASDAQ: PLAY) finally gave investors some of the evidence they’ve been waiting for, but after another quarter of declining entertainment revenue, collapsing EBITDA margins and a balance sheet carrying $1.5 billion of long-term debt, I still don’t think the improving operating trend is enough to make me want to own the stock.

Revenue fell 2.4% to $544.1 million in fiscal Q2, while adjusted EPS came in at a $0.27 loss versus a $0.40 profit a year ago. Adjusted EBITDA dropped from $129.8 million to $98.9 million, pushing the margin down from 23.3% to 18.2%.

That looks ugly. But the quarter also contains something I didn’t have when I wrote about Dave & Buster’s in April: evidence that management’s turnaround efforts are beginning to work. The problem is where that improvement is showing up.

Customers Are Returning, But They Still Aren’t Playing


The most encouraging number in this report is probably the comparable-store sales trend. Comps declined 2.9% in Q2, an improvement from the 5.4% decline in Q1. Management says July improved to a 1.6% decline, with further improvement in Q3 so far. Food and beverage sales also continued growing, while special-events sales have now grown for seven consecutive quarters.

That is real progress, and it directly challenges the argument I made in my previous article on PLAY that the turnaround was still mostly a story rather than a result.

But then I looked at where the sales are actually coming from.

Entertainment revenue fell 8.8% to $332.6 million, while food and beverage revenue jumped 9.6% to $211.5 million. I’m not comfortable with this part because Dave & Buster’s isn’t fundamentally a restaurant. The games and attractions are meant to give customers a reason to visit, while food and drinks monetize the time they spend there.

If entertainment keeps shrinking while F&B grows, the company may be getting better at extracting spending from existing visitors without proving that the core experience is bringing more people through the doors. And that’s a very different turnaround.

The Business Is Replacing High-Margin Revenue With Lower-Margin Revenue

This revenue mix matters because entertainment isn’t just another line item. When entertainment revenue falls by roughly $32 million, and F&B adds about $19 million, the company isn’t replacing one dollar with another dollar of equivalent economic value. The result is visible in the profitability numbers.

Adjusted EBITDA fell nearly 24% to $98.9 million, while store operating income before depreciation and amortization declined to $127.8 million from $155.4 million. The company’s reported operating margin fell to 3.6% from 9.5%.

There is an important caveat here: management said a roughly $10 million deferred-revenue impact made the quarter’s margins look worse, so I wouldn’t treat the entire 500-basis-point EBITDA contraction as permanent operating deterioration. But even after accounting for that distortion, the fundamental mix problem remains.

PLAY is still losing the revenue stream that makes the entertainment model so attractive. That’s why I’m less impressed by the improving comps than I might have been six months ago. I need to see entertainment stabilize, not just total spending per visitor improve.

Management Is Finally Spending Less On The Wrong Problem

There is, however, a part of the turnaround I genuinely like. Dave & Buster’s has remodeled stores, introduced new games and attractions and found that remodeled locations are outperforming the broader system. Management also plans to complete two more remodels during fiscal 2026, bringing the year’s total to eight.

More importantly, the company is becoming more disciplined about capital.

Adjusted free cash flow was positive $19.5 million through the first six months of fiscal 2026, compared with negative $36.5 million a year earlier. Operating cash flow rose to $160.6 million from $129.8 million, while capital expenditures fell to $190 million from $243.8 million.

That’s a meaningful improvement, but I still have to put it against the balance sheet. Dave & Buster’s had just $16 million of cash against $1.50 billion of long-term debt at the end of Q2, with a 3.5x net total leverage ratio. Interest expense alone was $38 million for the quarter.

That leaves very little room for a turnaround that takes longer than expected.

No Reason To Rush

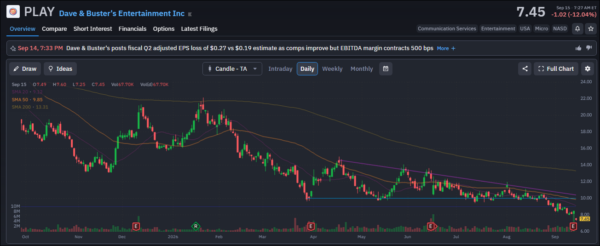
PLAY closed at $7.45, down 12% on the latest session, after spending most of the year grinding lower. The stock is below its 20-day SMA at $9.12, its 50-day SMA at $9.85 and its 200-day SMA at $13.31.

More importantly, every major recovery attempt on the chart has produced another lower high. PLAY briefly recovered toward $13–$14 in May and June, failed, and has now fallen below the $10 support zone that held through much of the summer.

At this point, $7.25–$7.50 is the level I would watch for immediate support. Lose that area, and PLAY could test $6. Above it, I would need to see PLAY reclaim $9.10–$9.20, then $9.85, before the chart begins giving me evidence that the trend has actually changed. 
play - StockEarnings

Why I’m Not Buying

I’m not interested in buying because PLAY has already fallen this far. The operating recovery is real, but the market is still waiting for evidence that Dave & Buster’s can fix the part of the business that drives its economics.

One can even argue that the comps are improving, F&B is growing, remodeled stores are outperforming, and cash generation has recovered. But entertainment revenue is still falling, EBITDA is contracting, and the company remains heavily leveraged, leaving too much risk in waiting for the turnaround to reach the games themselves.

I’d rather miss the first part of a genuine recovery than finance the waiting period while Dave & Buster’s tries to prove that customers are coming back to play, not simply coming back to eat.

Join over 1.2M+ investors/traders who receive daily and weekly notable earnings alerts with predicted move