ServiceTitan Inc (NASDAQ: TTAN) just produced the kind of quarter that should have made the stock easier to own, yet investors sent the shares down roughly 30% to $55. After digging through the numbers, I think the market may be reacting to the wrong part of the story.
The company delivered $292.8 million of revenue, up 21% year over year and ahead of expectations, while adjusted EPS came in at $0.40 versus roughly $0.35 expected. Non-GAAP operating income jumped 52% to $44.4 million, free cash flow reached $50.5 million, and full-year revenue guidance remains $1.139 billion to $1.144 billion.
So why did the stock get crushed?
ServiceTitan’s Old Growth Engine Is Cooling
What the slowdown investors are worried about is real, so I don’t want to explain away everything with AI. Gross transaction volume (GTV) rose 17% to $26.8 billion, down from 19% growth a year ago, while total revenue growth slowed from 25% to 21%. Platform revenue grew 22%, down from 26% in the comparable period.
GTV is important because it gives us a window into the underlying activity of contractors using ServiceTitan. If that number keeps slowing, the company cannot simply point at AI and pretend the core business doesn’t matter.
But profitability is moving in the opposite direction, as non-GAAP operating margin expanded from 12.1% to 15.2%, while operating cash flow climbed to $58 million from $40.3 million, and free cash flow jumped 47%.
The core business is growing more slowly but becoming substantially more profitable. And then Max enters the picture.
Max Is Growing Faster Than ServiceTitan Can Recognize
ServiceTitan exceeded its goal of doubling Max locations during Q2 and now expects more than 700 enrolled locations by the end of fiscal 2027.
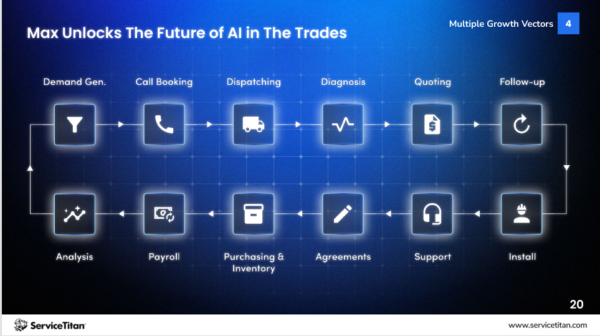
Max isn’t another small feature. ServiceTitan is trying to turn it into an agentic operating system for the trades, with AI handling parts of workflows that currently require people. The strange part is that successful Max adoption can actually make near-term revenue growth look worse.
Management explained that customers are not necessarily billed the full contract value immediately. Implementations can take multiple quarters as customers transition onto the product, creating a gap between the economic value of contracts being signed and the revenue appearing in the income statement.
ServiceTitan expects $2 million to $3 million of subscription revenue headwinds in the second half from Max revenue-recognition timing, plus roughly $2 million from waived onboarding fees for existing customers moving onto Max, which shows that the accounting is temporarily lagging the rollout.
The Economics Are Already Starting To Show
ServiceTitan is showing evidence that the business underneath the reported revenue is getting stronger.
Platform revenue reached $284.5 million, with subscription revenue up 22% to $212.4 million and usage revenue up 24% to $72.1 million. Platform gross margin improved to 78.7% GAAP and 81.1% non-GAAP.
Non-GAAP R&D spending rose 26% as ServiceTitan invests in its AI platform, yet operating leverage still pushed margins higher.
That is the combination I want from a software company entering a new product cycle: aggressive investment in the next growth engine while the existing platform produces more cash. ServiceTitan ended the quarter with $479.5 million in cash and is guiding to $152 million to $154 million of non-GAAP operating income for the full year.
The Chart Has Completely Lost Its Patience
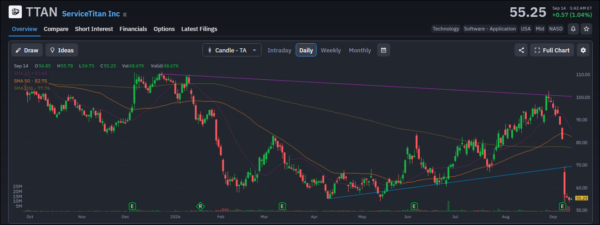
This is where I would be much more careful than the fundamentals alone suggest, because the technical damage isn’t simply a bad day after earnings. TTAN had spent months building a recovery from the April low, with a rising trendline supporting the stock through the spring and summer. That structure carried shares from the low-$50s to almost $100 by early September, but earnings broke the entire uptrend on roughly 48.7 million shares traded, the heaviest volume visible on the chart.
At $55.25, TTAN is roughly $30 below its 20-day SMA at $85.68, nearly $28 below its 50-day at $82.75 and more than $22 below its 200-day at $77.76. All three now sit above the stock, creating layers of overhead resistance.
The $54–$55 area is the first level I would watch. Lose it, and $50 becomes the obvious psychological level. But $69–$70 is more important because reclaiming the broken trendline would be the first sign that the collapse is stabilizing.
Above that, $77–$78 is the 200-day SMA, followed by $82–$86 where the 50-day and 20-day averages converge. TTAN would need to reclaim that entire zone before I would call the larger technical trend repaired.
The chart shows the market has lost confidence in the old growth trajectory. But it hasn’t yet disproved the Max thesis.
ServiceTitan Has To Prove Which Story Is Real
ServiceTitan expects Q3 revenue of $285 million to $287 million, slightly below the roughly $288 million consensus, although one fewer business day also weighs on the comparison.
If GTV continues slowing while Max fails to translate into stronger economics, the selloff will look justified. If Max keeps scaling, margins expand, and the revenue-recognition drag fades as implementations become more efficient, the current valuation could look very different.
If I’m buying this, it’s not because the chart is healthy. It isn’t. It’d be because ServiceTitan may have reached an unusual point where its old growth engine is cooling as its new AI engine accelerates, while the accounting treatment makes the near-term numbers look weaker than the underlying product adoption. But with TTAN below every major moving average, I would want $60 to hold first and $69–$70 reclaimed before adding aggressively. If those levels return, $77–$78 becomes the real confirmation that the market is starting to believe the Max transition.