ajax loader

Loading...


Ride-the-Wave Strategy – Best for Stock Traders

Ride-the-Wave targets multi-day price momentum following a company’s earnings announcement (EA). With this strategy:

  1. Buy a stock one day post-EA if a stock reacts positively post-earnings:
    1. Near the close of trading the EA-day for a pre-market-EA
    2. Near the close of the following day for a post-market-EA
  2. Sell-to-close after 7-10 days, or possibly earlier if a desired price target is reached

Similarly,

  1. short a stock one day post-EA if a stock reacts negatively post-earnings:
    1. near the close of trading the EA-day for a premarket-EA
    2. near the close of the following day for a post-market-EA
  2. then buy-to-close after 7-10 days, or possibly earlier if a desired price target is reached

Important: Ride-the-Wave is predicated on significant price momentum triggered by an EA. The 7-10 day scenario is the maximum trade hold-time. If you see post EA-momentum is halted or reversed by a significant opposite move, re-evaluate your presence in the trade.

This popular StockEarnings screen below will give you a list of stocks that historically exhibit significant price momentum following an EA for the next seven days:

  1. Stocks exhibiting positive post-EA price moves are buy-candidates
  2. Stocks exhibiting negative post-EA price moves are sell/short-candidates

The screen includes those stocks whose Earnings just came out in last two days.

Screen criteria:

  1. Earnings Date Start Date : Current Date + -1 Day
  2. Earnings Date End Date : Current Date + -2 Days
  3. Predicted Move (Next Day) Max : 7%
  4. Predicted Move (On 7th Day) Min : 7%

Strategy Guideline:

  1. Buy the stock if stock has reacted positively. Short the stock if stock has reacted negatively (see above).
  2. Close the position in 7-10 days, or possibly earlier based on price move.

Volatility Crush Strategy - Best for Options Traders

The Volatility Crush strategy is used with stocks that typically experience relatively low-to-moderate price moves (≤4%) following their Earnings Announcements (EA). The basic trade idea is to sell put or call options right before the EA, collecting a credit when options premium is very high due to elevated implied volatility (IV). You then close the position right after the EA by buying the option back much cheaper due to the significant drop in IV that occurs after the mystery of the EA disappears. In assessing this trade, you need to do your homework to ensure you collect sufficient premium to make the trade worthwhile.

This trade is practical due to the low-to-moderate price-move after the EA, which generally won’t significantly affect the options price, unlike an “action” stock, which experience great price moves post-EA. With these symbols, if you’re on the right side of the price move, that’s a great thing. But if you’re on the wrong side of the move, not so great. Consequently, by minimizing the effect of the post-EA price move, you have a much better chance to profit from the reduction in IV without it being ruined by a violent price move.

For this trade, open the position either (1) the night before the EA when the company announces earnings or (2) during the EA day when it announces post-market, generally capturing IV at or close to its peak.

For this trade, open the position either (1) the night before the EA when the company announces earnings or (2) during the EA day when it announces post-market, generally capturing IV at or close to its peak.

This popular stockearnings screen will give you a list of stocks which do not react more than 4% fpost-EA. It includes only those stocks whose earnings are releasing next day.

Screen criteria:

  1. Earnings Date Start Date : Current Date + 1
  2. Earnings Date End Date : Current Date + 1
  3. Predicted Move (Next Day) Max : 4%
  4. Options Type: Weekly

Strategy Guideline:

  1. Options Strategy: Sell Call and Put
  2. Options Strike Price: Current Stock Price – (% Predicated Move x 2)
  3. Expiration Date: It should generally be the closest expiry immediately after the EA.
  4. Buy Insurance: Buying back Call and Put at Strike price which 10% lower than Sell Strike Price is optional but recommended.

Watch Video for More Detail

Volatility Rush Strategy - Best for Options Traders

The Volatility Rush takes advantage of increasing options premiums into earnings announcements (EA) caused by an anticipated rise in Implied Volatility (IV). With this strategy, Buy a Call and Put at-the-money (a long straddle) 2-3 weeks before the EA when IV is lower. Sell the position either (1) the night before the EA when the company announces earnings pre-market, or (2) during the EA day when it announces post-market, generally capturing IV at or close to its peak.

This popular screen will give you a list of stocks whose Options premiums tend to rise into Earnings. It includes only those stocks whose Earnings are at least two weeks away from today.

Screen criteria:

  1. Earnings Date Start Date : Current Date + 15 Days
  2. Earnings Date End Date : Current Date + 30 Days
  3. Predicted Move (Next Day) Min : 5%
  4. Options Type: Weekly or Monthly if that lines up with the two to three-week lead-time for entering the trade

Strategy Guideline:

  1. Buy a Straddle at or close to the money two to three weeks pre-EA.
  2. Sell the position either the night before the EA when the company announces earnings pre-market, or during the EA day when it announces post-market.
  3. Expiration date should generally be the closest expiry immediately after the EA.
  4. Straddle price should not be more 60% of predicted move.

Predicted Move (Volatility)

Similar to Implied Volatility in Options. Expected volatility % based on our Proprietary Volatility Predication Model. We are expecting that stock price will likely to reach % in either direction by the end of next trading session after Earnings are released and not necessarily the closing volatility %.

Why is it important?

    This indicator helps

  1. Knowing expected volatility in stocks after Earnings helps to decide trading stocks before Earnings Announcement.
  2. Taking Advantage of volatility collapse following Earnings Results by using Advance Options strategies such as Spread and Straddles.

Since Last Earnings

Change in share price since last Earnings release.

Why is it Important?

When share has gained more than 10% since it's last Earning release, it tends to over react to minor bad news and give up some gains if not all. So, it contains more downside volatility than upside When share has dropped more than 10% since it's last Earning release, it tends to over react to minor good news and recover some drops if not all. So, it contains more upside volatility than downside.

EPS Surprise (%)

Occurs when a company's reported quarterly or annual profits are above or below analysts' expectations. Here is the formula to derive % EPS Surprice:

Actual EPS - Estimated EPS
------------------------------------- x 100
Estimated EPS

Why is it Important?

Earnings surprises can have a huge impact on a company's stock price. Several studies suggest that positive earnings surprises not only lead to an immediate hike in a stock's price, but also to a gradual increase over time. Hence, it's not surprising that some companies are known for routinely beating earning projections. A negative earnings surprise will usually result in a decline in share price.

Next Day Price Change (%)

Next Regular trading session Closing price following Earnings result.

For After Market Close Earnings, It is a next trading day closing price. For Before Market Open Earnings, It is the same trading day closing price.

Why is it Important?

Next Day price change is a reaction of Earnings result.

AMD 10/16 Call Spreads are Priced So Cheaply, It Seems Too Good to be True

Posted on Sep 17, 2026 by Joshua Enomoto

AMD 10/16 Call Spreads are Priced So Cheaply, It Seems Too Good to be True

There’s no such thing as a free lunch, and that especially applies to Wall Street. So, when I came across a compellingly discounted debit-side call spread for Advanced Micro Devices (NASDAQ: AMD), my first response was skepticism. And while I still believe the following proposition is risky, there’s an empirical case to consider for AMD stock.

Let’s set up the play. For the mid-September session, market makers were offering the 510/520 bull call spread expiring Oct. 16 (roughly five weeks away) for only $460. Should AMD stock rise through the $520 second-leg strike on expiration, the maximum profit would come out to $540. This would translate to a payout of over 117% — not bad for a month’s worth of “labor.”

It gets even more enticing, at least on paper. For Advanced Micro Devices stock to hit the full-profitability target ($520 on Oct. 16), the ticker would only need to rise 3.13% from Tuesday’s close. I don’t want to sound presumptuous, but that seems like a very reasonable forecast, considering the underlying boom in artificial intelligence.

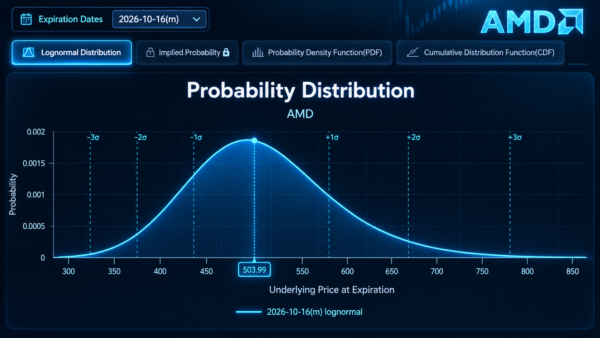
But there’s a catch — of course there is. Based on the Street’s options pricing mechanism, the probability of merely breaking even on the above call spread at $23.30 is only 44.5%. It’s not the worst ratio out there, but it does make you pause since we’re talking about a coin flip just to get a draw.
amd - StockEarnings

Worse yet, under the Black-Scholes model, the probability of AMD stock triggering the $520 level on expiration is only 39.5%. If you were to run an expected value calculation, your portfolio would quickly sink as the number of losses would eventually exceed the number of wins.

Therefore, many speculators would likely be convinced — based on the probabilistic evidence — to walk away from the trade. But what if I told you that you don’t necessarily need to abide by the first presupposition you encounter?

Prosecute the Claims Before Deciding on AMD Stock


Imagine for a moment that you’re enjoying a leisurely stroll on the beach trail. Suddenly, an apologist from Religion X admonishes you and says that you’re destined for perdition unless you exclusively worship their deity. Chagrined, you go a bit further until another apologist — this time for Religion Y — makes another exclusive claim about their faith.

Once you hear the same message from a representative of Religion Z, it should become readily apparent that there are three basic conclusions: one of these religions is telling the truth, some are telling partial truths, or they’re all unfounded.

Either way, if you’re intellectually curious, you’re going to investigate the claims. You wouldn’t just accept the truth claims of one of the three religions. This healthy auditing should then apply to Black-Scholes. Yes, they have presented a mathematical case for the likelihood that Advanced Micro Devices stock will hit certain thresholds. That by itself doesn’t mean the model is the exclusive arbiter of truth.

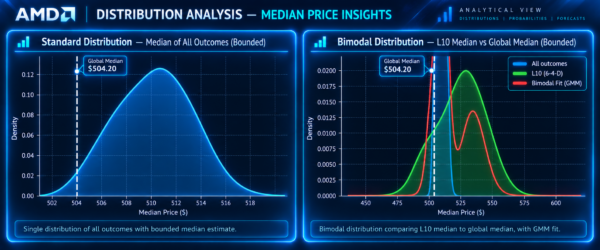
Arguably, the most problematic presupposition undergirding Black-Scholes is the random walk. Basically, the core driver of future price discovery under this model is that AMD stock will trade randomly between now and the expiration date. If it is true that future valuations are primarily derived from a random, risk-neutral environment, then yes, the aforementioned probabilities are legitimate.
amd - StockEarnings

But it should be this presupposition of a random walk that needs to be demonstrated. Because what necessarily follows from this setup is that the future is independent of the (material) past. However, I don’t find this argument compelling because there would be no reason to read investment and trading articles.

Think about any finance article ever published. They all reference something that happened in the past to make an inference about the future. That’s not a random walk — that’s very much a nonrandom walk.

Nobody ‘Really’ Believes in Black-Scholes

At the core, a technical analyst believes that past price patterns embed probabilistic information about the future. A fundamental analyst believes that past financial trends help forecast a forward-looking outcome. And a quantitative analyst believes unique signals within past empirical data provide a composite picture about the future trajectory.

What’s the common thread? Practitioners of these disciplines believe that the future is dependent on the past. Quants in particular believe in path dependency. Basically, they assume that the path that got a security to its present level matters in attempting to decipher where it may go next.

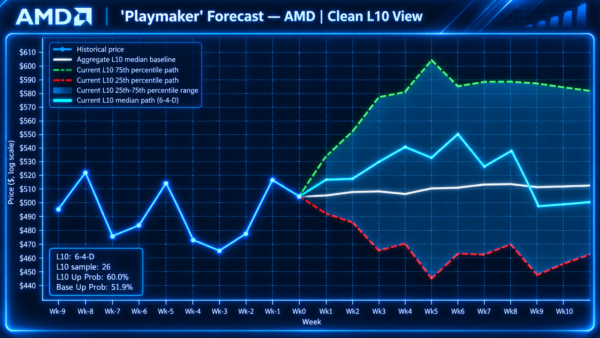
That’s the primary reason why I dispute the random-walk framework. In the case of AMD stock, in the last 10 weeks, the ticker managed to print six up weeks. Ordinarily, a bullish order flow imbalance would suggest an overall upward slope across the total defined period. However, AMD found itself in a rather unique situation where the overall slope was downward.
amd - StockEarnings

How rare is this 6-4-D (6 up, 4 down, downward slope) sequence? Going back to January 2009, this structural state has only materialized 26 times on a rolling basis. Over the next five weeks (again, roughly coinciding with the Oct. 16 expiration date), the median terminal expectation is for Advanced Micro Devices stock to hit $531.

Subsequently, there is a case — under this model — for speculators to consider the 520/530 bull spread, which currently features a maximum payout of nearly 141%. Wall Street sees such a move (to $530 on Oct. 16) as unlikely, assigning it a 34.6% probability.

Under the presupposition of a nonrandom walk, the odds could actually be 50%. Not great, obviously, but significantly better than 34.6%.

Why the $520 Strike is Intriguing

Despite the higher payout of the 520/530 spread, I still find the 510/520 spread more intriguing between the two. In part, that’s because the low sample size of 26 occurrences of the signal is not large enough to engender much confidence. Because of this reality, a more conservative exposure would seem to be ideal.

Usually, though, when you do become more conservative in the spread choice, the potential reward becomes heavily capped. That’s not necessarily the case for AMD stock when stepping down to the $520 strike.
amd - StockEarnings

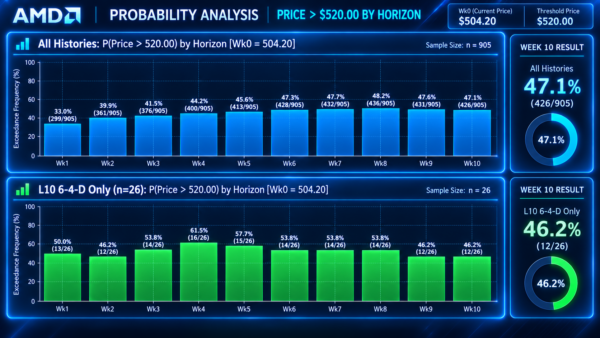
Under my nonrandom model, the odds of hitting the above target on expiration improve to 57.7% (or 15 hits out of 26 occurrences). That’s close to a 60% success ratio, which arguably alters the risk perception of AMD stock.

No one’s claiming that Advanced Micro is a no-brainer at this juncture. But when observing the situation from a presuppositional lens that more likely aligns with market reality, it’s difficult not to get excited about AMD stock.

Joshua Enomoto is a seasoned financial writer with a strong track record of in-depth stock analysis, offering clear, insightful commentary for retail investors across all levels of expertise. Renowned for his ability to blend analytical rigor with engaging wit, Joshua's work has been featured on leading investment platforms, including TipRanks, InvestorPlace, Barchart, Benzinga, and Fintel. He was also handpicked to spearhead high-impact initiatives such as InvestorPlace's "Trade of the Day" and Benzinga’s ETF coverage. As a frequent guest expert for CGTN America, Joshua discusses a wide range of economic, societal, and consumer market trends. A graduate of U.C. San Diego, Joshua brings a thoughtful and fresh perspective to complex financial narratives, helping enterprise clients connect with their audiences. He also composes music in his spare time.

Join over 1.2M+ investors/traders who receive daily and weekly notable earnings alerts with predicted move