ajax loader

Loading...


Ride-the-Wave Strategy – Best for Stock Traders

Ride-the-Wave targets multi-day price momentum following a company’s earnings announcement (EA). With this strategy:

  1. Buy a stock one day post-EA if a stock reacts positively post-earnings:
    1. Near the close of trading the EA-day for a pre-market-EA
    2. Near the close of the following day for a post-market-EA
  2. Sell-to-close after 7-10 days, or possibly earlier if a desired price target is reached

Similarly,

  1. short a stock one day post-EA if a stock reacts negatively post-earnings:
    1. near the close of trading the EA-day for a premarket-EA
    2. near the close of the following day for a post-market-EA
  2. then buy-to-close after 7-10 days, or possibly earlier if a desired price target is reached

Important: Ride-the-Wave is predicated on significant price momentum triggered by an EA. The 7-10 day scenario is the maximum trade hold-time. If you see post EA-momentum is halted or reversed by a significant opposite move, re-evaluate your presence in the trade.

This popular StockEarnings screen below will give you a list of stocks that historically exhibit significant price momentum following an EA for the next seven days:

  1. Stocks exhibiting positive post-EA price moves are buy-candidates
  2. Stocks exhibiting negative post-EA price moves are sell/short-candidates

The screen includes those stocks whose Earnings just came out in last two days.

Screen criteria:

  1. Earnings Date Start Date : Current Date + -1 Day
  2. Earnings Date End Date : Current Date + -2 Days
  3. Predicted Move (Next Day) Max : 7%
  4. Predicted Move (On 7th Day) Min : 7%

Strategy Guideline:

  1. Buy the stock if stock has reacted positively. Short the stock if stock has reacted negatively (see above).
  2. Close the position in 7-10 days, or possibly earlier based on price move.

Volatility Crush Strategy - Best for Options Traders

The Volatility Crush strategy is used with stocks that typically experience relatively low-to-moderate price moves (≤4%) following their Earnings Announcements (EA). The basic trade idea is to sell put or call options right before the EA, collecting a credit when options premium is very high due to elevated implied volatility (IV). You then close the position right after the EA by buying the option back much cheaper due to the significant drop in IV that occurs after the mystery of the EA disappears. In assessing this trade, you need to do your homework to ensure you collect sufficient premium to make the trade worthwhile.

This trade is practical due to the low-to-moderate price-move after the EA, which generally won’t significantly affect the options price, unlike an “action” stock, which experience great price moves post-EA. With these symbols, if you’re on the right side of the price move, that’s a great thing. But if you’re on the wrong side of the move, not so great. Consequently, by minimizing the effect of the post-EA price move, you have a much better chance to profit from the reduction in IV without it being ruined by a violent price move.

For this trade, open the position either (1) the night before the EA when the company announces earnings or (2) during the EA day when it announces post-market, generally capturing IV at or close to its peak.

For this trade, open the position either (1) the night before the EA when the company announces earnings or (2) during the EA day when it announces post-market, generally capturing IV at or close to its peak.

This popular stockearnings screen will give you a list of stocks which do not react more than 4% fpost-EA. It includes only those stocks whose earnings are releasing next day.

Screen criteria:

  1. Earnings Date Start Date : Current Date + 1
  2. Earnings Date End Date : Current Date + 1
  3. Predicted Move (Next Day) Max : 4%
  4. Options Type: Weekly

Strategy Guideline:

  1. Options Strategy: Sell Call and Put
  2. Options Strike Price: Current Stock Price – (% Predicated Move x 2)
  3. Expiration Date: It should generally be the closest expiry immediately after the EA.
  4. Buy Insurance: Buying back Call and Put at Strike price which 10% lower than Sell Strike Price is optional but recommended.

Watch Video for More Detail

Volatility Rush Strategy - Best for Options Traders

The Volatility Rush takes advantage of increasing options premiums into earnings announcements (EA) caused by an anticipated rise in Implied Volatility (IV). With this strategy, Buy a Call and Put at-the-money (a long straddle) 2-3 weeks before the EA when IV is lower. Sell the position either (1) the night before the EA when the company announces earnings pre-market, or (2) during the EA day when it announces post-market, generally capturing IV at or close to its peak.

This popular screen will give you a list of stocks whose Options premiums tend to rise into Earnings. It includes only those stocks whose Earnings are at least two weeks away from today.

Screen criteria:

  1. Earnings Date Start Date : Current Date + 15 Days
  2. Earnings Date End Date : Current Date + 30 Days
  3. Predicted Move (Next Day) Min : 5%
  4. Options Type: Weekly or Monthly if that lines up with the two to three-week lead-time for entering the trade

Strategy Guideline:

  1. Buy a Straddle at or close to the money two to three weeks pre-EA.
  2. Sell the position either the night before the EA when the company announces earnings pre-market, or during the EA day when it announces post-market.
  3. Expiration date should generally be the closest expiry immediately after the EA.
  4. Straddle price should not be more 60% of predicted move.

Predicted Move (Volatility)

Similar to Implied Volatility in Options. Expected volatility % based on our Proprietary Volatility Predication Model. We are expecting that stock price will likely to reach % in either direction by the end of next trading session after Earnings are released and not necessarily the closing volatility %.

Why is it important?

    This indicator helps

  1. Knowing expected volatility in stocks after Earnings helps to decide trading stocks before Earnings Announcement.
  2. Taking Advantage of volatility collapse following Earnings Results by using Advance Options strategies such as Spread and Straddles.

Since Last Earnings

Change in share price since last Earnings release.

Why is it Important?

When share has gained more than 10% since it's last Earning release, it tends to over react to minor bad news and give up some gains if not all. So, it contains more downside volatility than upside When share has dropped more than 10% since it's last Earning release, it tends to over react to minor good news and recover some drops if not all. So, it contains more upside volatility than downside.

EPS Surprise (%)

Occurs when a company's reported quarterly or annual profits are above or below analysts' expectations. Here is the formula to derive % EPS Surprice:

Actual EPS - Estimated EPS
------------------------------------- x 100
Estimated EPS

Why is it Important?

Earnings surprises can have a huge impact on a company's stock price. Several studies suggest that positive earnings surprises not only lead to an immediate hike in a stock's price, but also to a gradual increase over time. Hence, it's not surprising that some companies are known for routinely beating earning projections. A negative earnings surprise will usually result in a decline in share price.

Next Day Price Change (%)

Next Regular trading session Closing price following Earnings result.

For After Market Close Earnings, It is a next trading day closing price. For Before Market Open Earnings, It is the same trading day closing price.

Why is it Important?

Next Day price change is a reaction of Earnings result.

Salesforce Reinvents Microsoft’s Domination In Q1 2027 Earnings Report

Posted on May 28, 2026 by Grayson Cavern

Salesforce Reinvents Microsoft’s Domination In Q1 2027 Earnings Report

Back in the early 2000s, people constantly mocked Microsoft Corp (NASDAQ: MSFT) products. Outlook froze. Internet Explorer became a meme before memes even existed. Employees complained about Windows every chance they got. Yet corporations stayed locked inside Microsoft’s ecosystem because replacing it would have wrecked workflows across entire organizations already built around the software.

I think investors should look at Salesforce Inc (NYSE: CRM) through that exact lens right now.

Salesforce reported first-quarter fiscal 2027 earnings, with earnings per share coming in hot at $3.88 and revenue of $11.13 billion, both ahead of Wall Street estimates. Fine. Everybody already knows that part. What interests me now is the growing gap between how the market talks about Salesforce and what the figures actually suggest about customer behavior underneath the surface.

Customers Keep Committing More Future Dollars Despite AI Threat


Start with the figure that changes the entire quarter once you connect it to the broader software environment: current remaining performance obligations rose 12% year over year while revenue grew 13%.

Subscription and support revenue climbed another 9% year over year, while Salesforce closed 98 deals worth more than $1 million in annual contract value during the quarter. That is important because large enterprises usually cut experimental software spending first when budgets tighten. The numbers here suggest Salesforce still sits inside the “mission-critical” category for many organizations.

Even with such hard figures and facts, investors still analyze Salesforce like consumers choosing apps on a phone. Large corporations do not operate that way. Entire sales operations, customer databases, support systems, compliance workflows, and internal automations often sit inside Salesforce after years of customization and integration work. Replacing it becomes expensive, political, disruptive, and risky across multiple departments at once.

Why Governments Trust Industry Monarchs Over Unproven Startups

Now connect those figures to the company’s recent partnerships and contracts because they support the same thesis from another angle.

Salesforce expanded its Formula 1 partnership around Agentforce. The U.S. Department of Labor adopted Agentforce to support citizen services. Then the U.S. Army awarded Salesforce a $5.6 billion contract tied to military modernization and Department of War readiness initiatives.

Most people will skim those headlines and move on because they do not sound as flashy as AI chip announcements or trillion-dollar infrastructure spending stories. 

But you see, large institutions do not hand sensitive workflows, operational systems, or citizen interactions to unproven AI startups with no track record. They lean toward vendors, the industry Monarchs, already embedded inside their infrastructure, because trust matters more once critical systems get involved. Salesforce understands this. The company is trying to position itself as the trusted AI layer sitting inside existing enterprise operations before the software landscape shifts further.

And honestly, I think the market still underestimates how powerful incumbency becomes during periods of technological transition. AI may eventually weaken software moats over time, but right now, it may actually strengthen the largest enterprise incumbents first because enterprises prefer familiar vendors handling sensitive data and workflow automation.

The Relentless Doubting Thomases

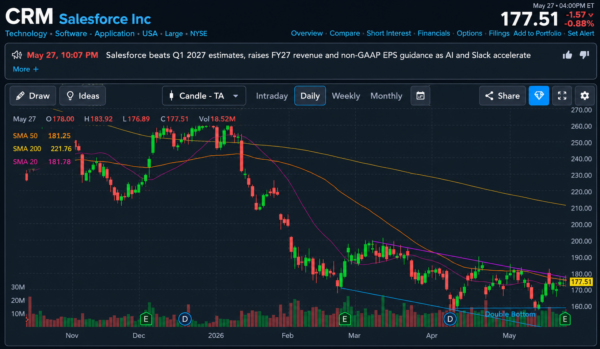
Look at the chart, and you can already feel the hesitation around Salesforce (NYSE: CRM). The company beat earnings, raised guidance, pushed AI partnerships harder, and still the stock closed at $177.51, down 0.88% after trading nearly 18.52 million shares. That reaction tells you investors still do not fully trust the story.

And honestly, I understand the skepticism. CRM has spent months trapped below its declining 50-day and 200-day moving averages after getting crushed from the $260 zone earlier this year. Every rally attempt keeps running into sellers, which usually happens when institutions are still questioning whether AI can genuinely reaccelerate growth or merely defend the existing business.

Still, despite all the volatility, the stock keeps defending the mid-$150s area while building a possible double bottom structure. That does not look like panic liquidation anymore. It looks more like a market waiting for proof.
salesforce - StockEarnings

If It Looks, Acts, And Moves Like  A Mature Company… Maybe it is

The rest of the quarter reinforces the same transition.

Operating cash flow reached $6.5 billion while free cash flow came in at $6.3 billion. Non-GAAP operating margin expanded to 32.3%, and management announced a $25 billion accelerated share repurchase, the largest buyback program in company history.

The more I think about it, the more Salesforce looks like a mature enterprise platform extracting more profit, more cash flow, and more operating leverage from an already entrenched customer base. Hypergrowth software companies usually prioritize expansion and aggressive reinvestment above everything else. On the flip side, mature enterprise platforms prioritize margins, cash generation, and shareholder returns because the customer base already behaves like recurring infrastructure revenue.

That transition creates the tension around CRM now because the market still wants software companies to produce explosive AI-driven acceleration, yet Salesforce’s figures continue pointing toward something more durable and less exciting on the surface: a deeply embedded enterprise platform using AI to strengthen customer dependence before competitors can weaken it.

Remember The Threat, But Stick To The Figures

At the same time, the long-term threat remains obvious. If AI agents eventually sit above software stacks and automate workflows independently, traditional software suites could lose pricing power across the industry. Microsoft remains dangerous because it already controls productivity infrastructure while integrating AI deeper into enterprise workflows every quarter.

Still, this earnings report showed something investors probably should not ignore. Enterprises continue committing future dollars to Salesforce despite every AI headline screaming that software disruption is accelerating.

Until those figures crack, betting against Salesforce becomes harder than many investors want to admit.


Join over 1.2M+ investors/traders who receive daily and weekly notable earnings alerts with predicted move