ajax loader

Loading...


Ride-the-Wave Strategy – Best for Stock Traders

Ride-the-Wave targets multi-day price momentum following a company’s earnings announcement (EA). With this strategy:

  1. Buy a stock one day post-EA if a stock reacts positively post-earnings:
    1. Near the close of trading the EA-day for a pre-market-EA
    2. Near the close of the following day for a post-market-EA
  2. Sell-to-close after 7-10 days, or possibly earlier if a desired price target is reached

Similarly,

  1. short a stock one day post-EA if a stock reacts negatively post-earnings:
    1. near the close of trading the EA-day for a premarket-EA
    2. near the close of the following day for a post-market-EA
  2. then buy-to-close after 7-10 days, or possibly earlier if a desired price target is reached

Important: Ride-the-Wave is predicated on significant price momentum triggered by an EA. The 7-10 day scenario is the maximum trade hold-time. If you see post EA-momentum is halted or reversed by a significant opposite move, re-evaluate your presence in the trade.

This popular StockEarnings screen below will give you a list of stocks that historically exhibit significant price momentum following an EA for the next seven days:

  1. Stocks exhibiting positive post-EA price moves are buy-candidates
  2. Stocks exhibiting negative post-EA price moves are sell/short-candidates

The screen includes those stocks whose Earnings just came out in last two days.

Screen criteria:

  1. Earnings Date Start Date : Current Date + -1 Day
  2. Earnings Date End Date : Current Date + -2 Days
  3. Predicted Move (Next Day) Max : 7%
  4. Predicted Move (On 7th Day) Min : 7%

Strategy Guideline:

  1. Buy the stock if stock has reacted positively. Short the stock if stock has reacted negatively (see above).
  2. Close the position in 7-10 days, or possibly earlier based on price move.

Volatility Crush Strategy - Best for Options Traders

The Volatility Crush strategy is used with stocks that typically experience relatively low-to-moderate price moves (≤4%) following their Earnings Announcements (EA). The basic trade idea is to sell put or call options right before the EA, collecting a credit when options premium is very high due to elevated implied volatility (IV). You then close the position right after the EA by buying the option back much cheaper due to the significant drop in IV that occurs after the mystery of the EA disappears. In assessing this trade, you need to do your homework to ensure you collect sufficient premium to make the trade worthwhile.

This trade is practical due to the low-to-moderate price-move after the EA, which generally won’t significantly affect the options price, unlike an “action” stock, which experience great price moves post-EA. With these symbols, if you’re on the right side of the price move, that’s a great thing. But if you’re on the wrong side of the move, not so great. Consequently, by minimizing the effect of the post-EA price move, you have a much better chance to profit from the reduction in IV without it being ruined by a violent price move.

For this trade, open the position either (1) the night before the EA when the company announces earnings or (2) during the EA day when it announces post-market, generally capturing IV at or close to its peak.

For this trade, open the position either (1) the night before the EA when the company announces earnings or (2) during the EA day when it announces post-market, generally capturing IV at or close to its peak.

This popular stockearnings screen will give you a list of stocks which do not react more than 4% fpost-EA. It includes only those stocks whose earnings are releasing next day.

Screen criteria:

  1. Earnings Date Start Date : Current Date + 1
  2. Earnings Date End Date : Current Date + 1
  3. Predicted Move (Next Day) Max : 4%
  4. Options Type: Weekly

Strategy Guideline:

  1. Options Strategy: Sell Call and Put
  2. Options Strike Price: Current Stock Price – (% Predicated Move x 2)
  3. Expiration Date: It should generally be the closest expiry immediately after the EA.
  4. Buy Insurance: Buying back Call and Put at Strike price which 10% lower than Sell Strike Price is optional but recommended.

Watch Video for More Detail

Volatility Rush Strategy - Best for Options Traders

The Volatility Rush takes advantage of increasing options premiums into earnings announcements (EA) caused by an anticipated rise in Implied Volatility (IV). With this strategy, Buy a Call and Put at-the-money (a long straddle) 2-3 weeks before the EA when IV is lower. Sell the position either (1) the night before the EA when the company announces earnings pre-market, or (2) during the EA day when it announces post-market, generally capturing IV at or close to its peak.

This popular screen will give you a list of stocks whose Options premiums tend to rise into Earnings. It includes only those stocks whose Earnings are at least two weeks away from today.

Screen criteria:

  1. Earnings Date Start Date : Current Date + 15 Days
  2. Earnings Date End Date : Current Date + 30 Days
  3. Predicted Move (Next Day) Min : 5%
  4. Options Type: Weekly or Monthly if that lines up with the two to three-week lead-time for entering the trade

Strategy Guideline:

  1. Buy a Straddle at or close to the money two to three weeks pre-EA.
  2. Sell the position either the night before the EA when the company announces earnings pre-market, or during the EA day when it announces post-market.
  3. Expiration date should generally be the closest expiry immediately after the EA.
  4. Straddle price should not be more 60% of predicted move.

Predicted Move (Volatility)

Similar to Implied Volatility in Options. Expected volatility % based on our Proprietary Volatility Predication Model. We are expecting that stock price will likely to reach % in either direction by the end of next trading session after Earnings are released and not necessarily the closing volatility %.

Why is it important?

    This indicator helps

  1. Knowing expected volatility in stocks after Earnings helps to decide trading stocks before Earnings Announcement.
  2. Taking Advantage of volatility collapse following Earnings Results by using Advance Options strategies such as Spread and Straddles.

Since Last Earnings

Change in share price since last Earnings release.

Why is it Important?

When share has gained more than 10% since it's last Earning release, it tends to over react to minor bad news and give up some gains if not all. So, it contains more downside volatility than upside When share has dropped more than 10% since it's last Earning release, it tends to over react to minor good news and recover some drops if not all. So, it contains more upside volatility than downside.

EPS Surprise (%)

Occurs when a company's reported quarterly or annual profits are above or below analysts' expectations. Here is the formula to derive % EPS Surprice:

Actual EPS - Estimated EPS
------------------------------------- x 100
Estimated EPS

Why is it Important?

Earnings surprises can have a huge impact on a company's stock price. Several studies suggest that positive earnings surprises not only lead to an immediate hike in a stock's price, but also to a gradual increase over time. Hence, it's not surprising that some companies are known for routinely beating earning projections. A negative earnings surprise will usually result in a decline in share price.

Next Day Price Change (%)

Next Regular trading session Closing price following Earnings result.

For After Market Close Earnings, It is a next trading day closing price. For Before Market Open Earnings, It is the same trading day closing price.

Why is it Important?

Next Day price change is a reaction of Earnings result.

Despite the Turmoil, Intuitive Machines (LUNR) Stock Could Be Mispriced

Posted on Sep 18, 2026 by Joshua Enomoto

Despite the Turmoil, Intuitive Machines (LUNR) Stock Could Be Mispriced

To say that Intuitive Machines (NASDAQ: LUNR) has struggled would be an understatement. Yes, the space economy is projected to be a multi-trillion-dollar sector over the next several years. It’s also true that LUNR stock has previously benefited from a historic contractual backlog of $1.8 billion, per Google Finance’s summary sheet.

Even with those datapoints, it’s impossible to ignore the overall contradiction in the technical domain.

Just pull up a standard price chart for Intuitive Machines stock. On a year-to-date basis, the ticker is down 14.54%, which initially might not sound too bad for such a speculative name. But look at the six-month trailing loss, which comes out to almost 27% in the red. Then look at the trailing month, which has succumbed nearly 32% below parity.
lunr - StockEarnings

Conventional wisdom says to run far away from LUNR stock. While there might be a discount on the premise of mean reversion, unless this argument is demonstrated, it frankly appears like wishful thinking. Nevertheless, for those who want to take a capped-risk, capped-reward shot at LUNR, a vertical options spread expiring Oct. 23 could be interesting.

How so? There could be an unusual mispricing event.

Identifying the Opportunity in LUNR Stock (and the Risk)


What really caught my attention was the 14/15.50 bull call spread expiring Oct. 23, which is roughly six weeks out from the time of writing (Sep. 16). For a net debit (cash outlay) of $71, a speculator will be hoping for Intuitive Machines stock to trigger the $15.50 second-leg strike price at expiration. If so, the maximum profit would clock in at $79, a payout of over 111%.

From a nominal risk management perspective, I appreciate that I can slowly stagger my exposure. A few turns at $71 a pop isn’t the greatest expenditure in the world. Further, the way the spread is structured, the most that can be lost is the net debit paid per spread.

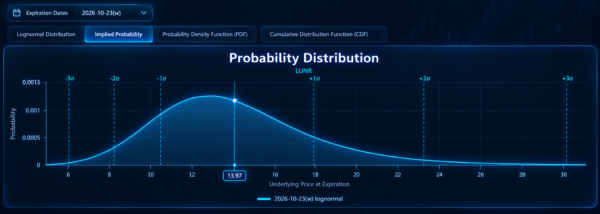
But beyond the surface-level risk that LUNR stock is historically a volatile entity is the actual probabilistic risk. Wall Street assigns a probability of breakeven at the $14.71 price point of only 41.2%. Worse yet, OptionCharts.io’s Probability Distribution screener indicates that the odds of LUNR triggering the $15.50 second-leg strike at expiration sit at only 30.62%.
lunr - StockEarnings

You don’t have to run a formal expected value calculation to immediately see the dilemma facing debit-side options traders. At these probabilities, your portfolio would quickly sink as the number of losses (both full and partial) outpaces the number of wins.

In any other circumstance, financial experts would likely recommend you avoid this idea altogether. But this seemingly pessimistic conclusion is also where the opportunity rests for LUNR stock — and that’s because you don’t have to automatically accept the underlying presupposition.

It’s All Presuppositional, and That’s the Point for Forecasting Intuitive Machines Stock

While some entities in the financial publication space may believe that their indicators represent the gospel truth of the markets, nothing could be further from the actual truth. In reality, any argument made about the unknown future requires a presupposition to move the discussion forward.

And that’s the undeserved mythology of Wall Street’s probability distributions. Yeah, they may look “scientific” because you’re seeing bell curves and standard deviations. But cutting through all the nonsense, any forward-looking model is a presupposition.

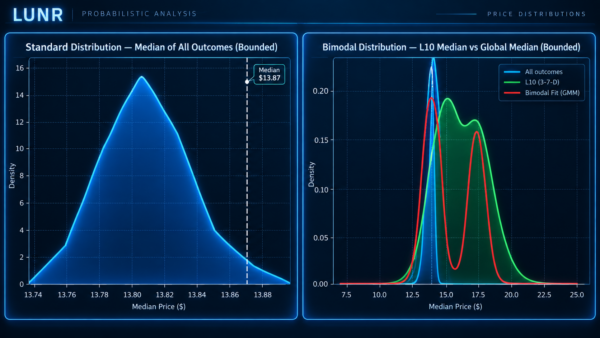
Getting back to the aforementioned probabilities — 41.2% to break even, 30.62% to full profitability — these are derived from the Black-Scholes family of calculations. They’re useful because the calculations integrate implied volatility (IV), which itself derives from actual orders. However, the output of the formula presupposes that the target security will undergo a random walk between now and the expiration date.

If such a random walk occurred, then yes, those probabilities would accurately reflect reality. But it’s this presupposition that should be challenged. Because by necessity of the underlying math of Black-Scholes, the future is treated as an independent variable relative to the past.
lunr - StockEarnings

None of us (to my knowledge) actually believes this. Fundamental analysts believe that past financial disclosures embed potential information about future trends. Technical analysts believe that past price patterns embed probabilities of future breakouts (or breakdowns). Quantitative analysts believe that conditioned trends found in past empirical data can create a composite picture of what may materialize tomorrow.

What’s the common thread? There’s a presupposition that the future is dependent on the past.

If that were the case — and I believe the data backs this up — it doesn’t make too much sense to rely on a random-walk model to help decipher LUNR stock. Let’s also keep in mind that Intuitive Machines has a 60-month beta of 1.85. Thus, it’s significantly more volatile than the benchmark S&P 500.

Combined, these factors would suggest that the future will not be random but would instead depend on past material events.

Filtering for the Identified Signal

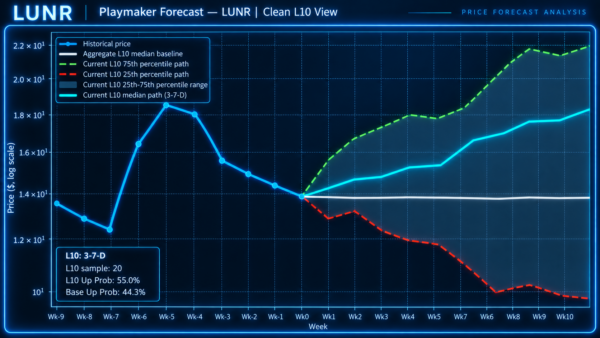
So, from a quantitative perspective, what would be the material event that occurred that may influence the near-term future of Intuitive Machines stock? I would argue that its distinctively bearish order flow balance over the last 10 weeks — where LUNR has only managed to print three up weeks — represents a key signal.

During this time, the overall slope was downward. By discretizing price action as hard, binary categories, we can come up with a 3-7-D state classification, enabling us to look back in time to tabulate how many occurrences of this signal have materialized. As it turns out, there have been 20 occurrences (on a rolling basis) since the public market debut of LUNR stock.

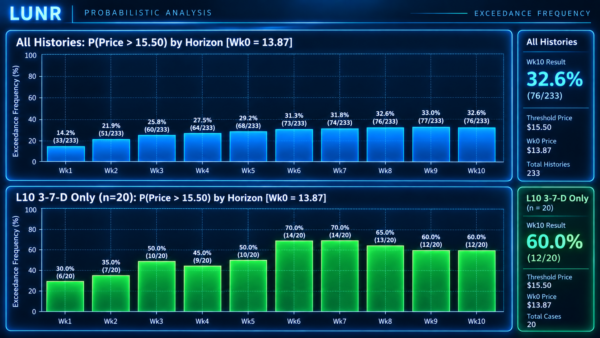
Of this figure, the ticker has exceeded the equivalent of the $15.50 strike on week 6 (coinciding with the Oct. 23 expiration date) 14 times. Granted, the sample size is extremely small, leading to potential distortions. Still, as a simple statistic in the observed period, LUNR stock is currently running a projected 70% hit ratio for the 14/15.50 bull spread.
lunr - StockEarnings

If that is indeed the case — and of course it’s a massive “if” due to the sample-size problem — there may be a serious mispricing of Intuitive Machines stock call spreads. Even if the exact projected probabilities are disputed, the observed reality is that this ticker historically enjoys a buy-the-dip rally following an extended downturn.

The major caveat is that an inductive inference cannot guarantee that prior trends will materialize as expected in the future. Still, if you have some “silly” money lying around, LUNR stock might not be a bad candidate to consider.

Finally, for a detailed, visual look at the process that undergirds my Markov chain analysis, you may watch my YouTube videos.

Joshua Enomoto is a seasoned financial writer with a strong track record of in-depth stock analysis, offering clear, insightful commentary for retail investors across all levels of expertise. Renowned for his ability to blend analytical rigor with engaging wit, Joshua's work has been featured on leading investment platforms, including TipRanks, InvestorPlace, Barchart, Benzinga, and Fintel. He was also handpicked to spearhead high-impact initiatives such as InvestorPlace's "Trade of the Day" and Benzinga’s ETF coverage. As a frequent guest expert for CGTN America, Joshua discusses a wide range of economic, societal, and consumer market trends. A graduate of U.C. San Diego, Joshua brings a thoughtful and fresh perspective to complex financial narratives, helping enterprise clients connect with their audiences. He also composes music in his spare time.

Join over 1.2M+ investors/traders who receive daily and weekly notable earnings alerts with predicted move